

Taking a side-by-side UTV from a driveway in Huntersville to a weekend trail ride in the Uwharrie National Forest moves that vehicle out of the reach of most homeowners coverage. North Carolina ATV insurance fills that gap by protecting the machine, the operator, and the owner from liability. It does so whether the rider is the owner, a visiting friend, or a teenager in the family.
For families across Charlotte, Concord, Cornelius, and Harrisburg, off-road vehicles have become a common part of weekend recreation. The insurance questions they raise are frequently misunderstood until a claim is filed.
Understanding North Carolina ATV Insurance Requirements
Off-road vehicle owners in North Carolina should carry a dedicated ATV or UTV policy that includes liability coverage, physical damage protection, and medical payments. Liability limits should be at least equal to the state's updated auto minimums of 50/100/50, which took effect July 1, 2025. Higher limits are prudent for most households.
The 50/100/50 figures represent $50,000 for bodily injury per person, $100,000 per accident, and $50,000 for property damage. These minimums apply to registered automobiles, not to every off-road machine. Industry professionals nonetheless treat them as a sensible floor for ATV and UTV liability. A trail collision that injures another rider can easily produce medical bills exceeding older, lower limits.
State law also governs how these vehicles are operated. All ATV operators on public vehicular areas must wear eye protection and a DOT-compliant safety helmet. Violations of operating rules can complicate a claim, particularly when an injury lawsuit follows. Many private trail parks also ask riders to show proof of insurance before granting access, which gives owners a practical reason to secure coverage before the season begins.
Why Your Homeowners Policy Usually Excludes Off-Premises Riding
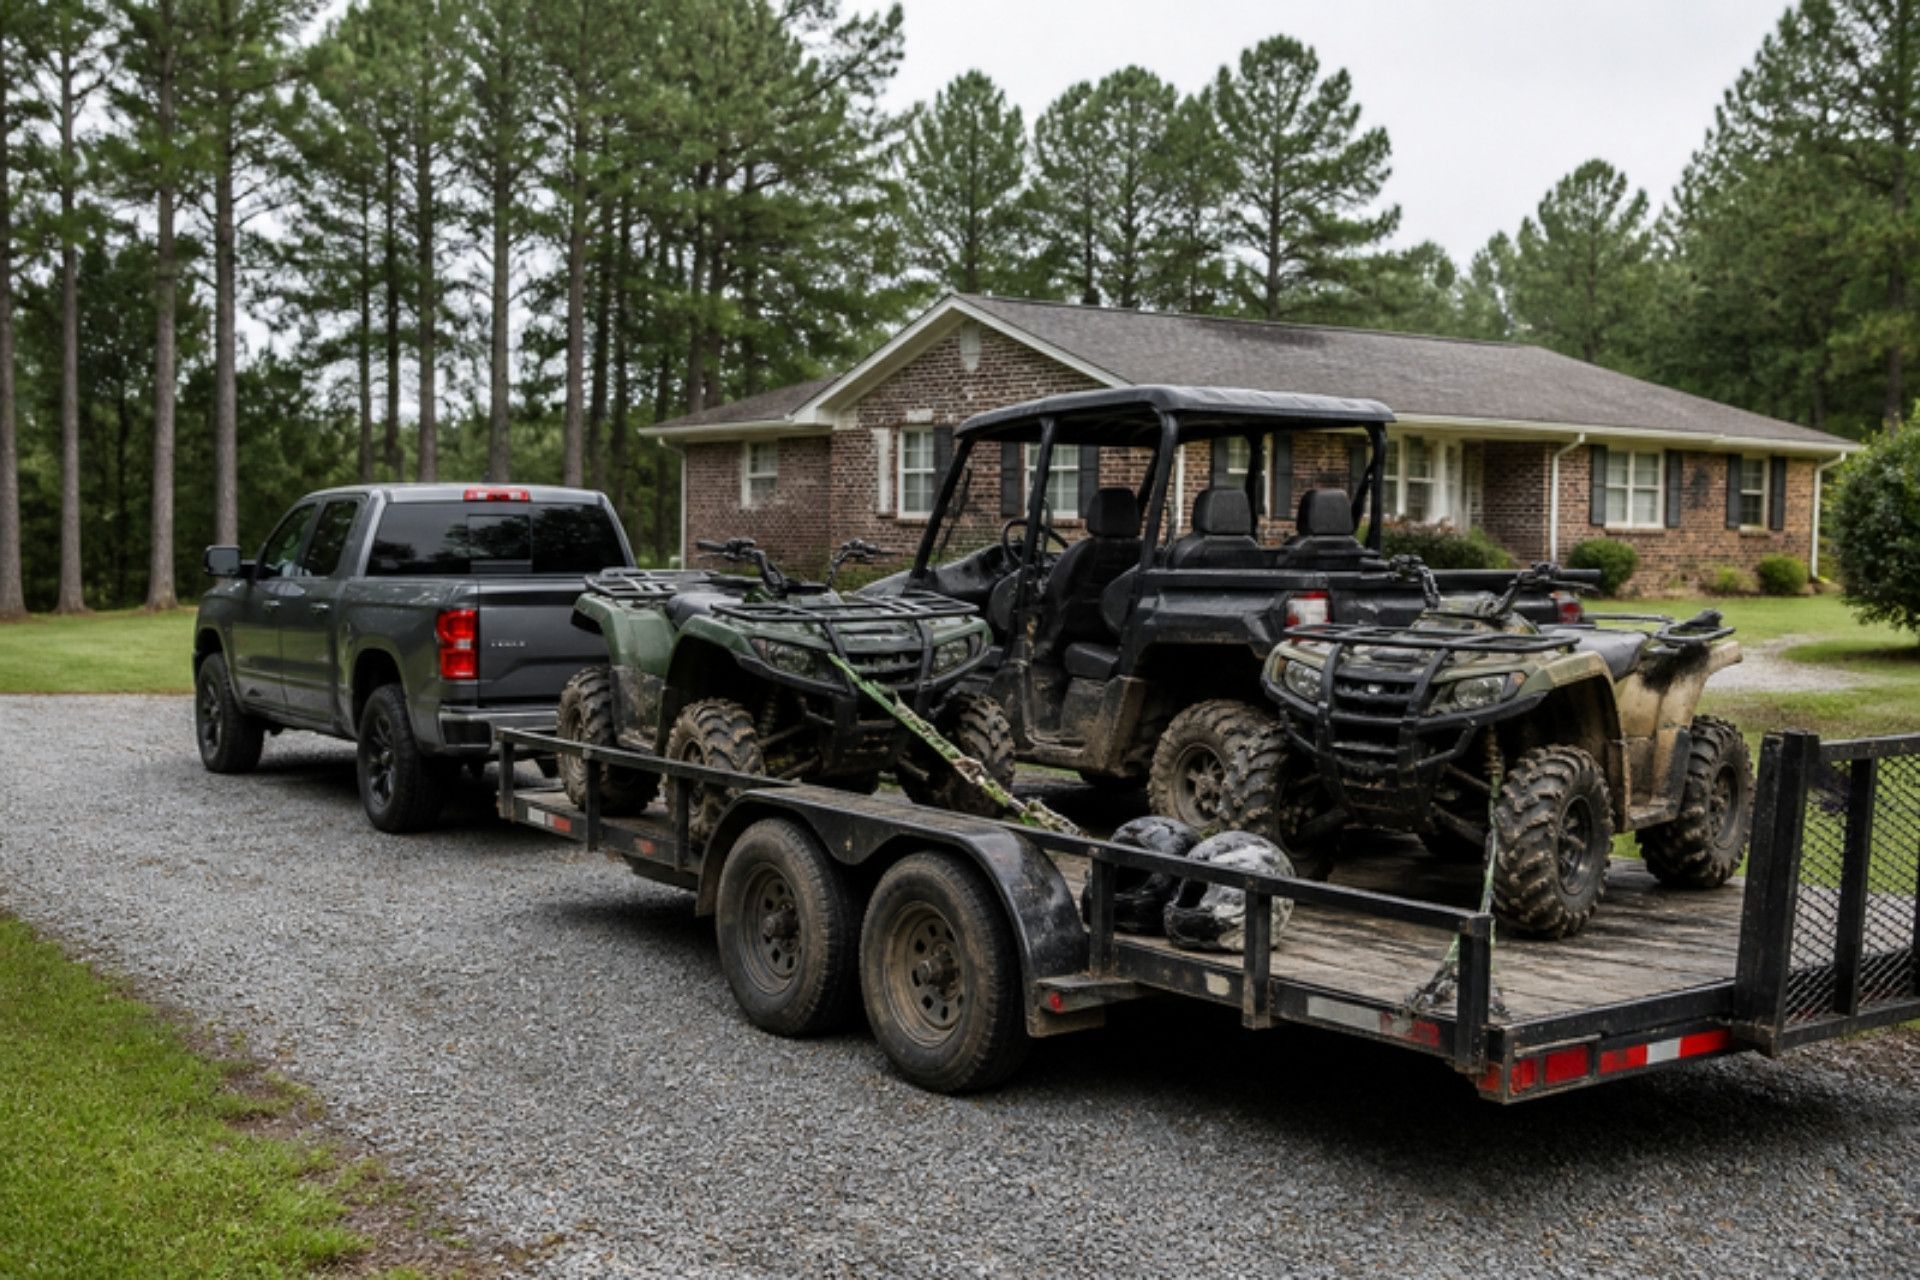
A homeowners policy may extend limited coverage to an ATV used for yard work or maintenance on the insured property. Once that vehicle leaves the property for trails such as those in Uwharrie National Forest, the policy typically provides no liability or physical damage coverage at all.
Standard homeowners policies in North Carolina typically contain exclusions for motorized vehicle liability and property coverage. The narrow exception for "residence premises" use exists so that a homeowner hauling mulch across a two-acre lot in Harrisburg is not left unprotected. That exception is written tightly, and recreational riding off the property falls outside it.
A common claim scenario illustrates the problem. An owner trailers a UTV to the Badin Lake OHV area, and a guest rolls the machine on a rocky descent, injuring a passenger. The homeowners carrier denies the bodily injury claim because the accident occurred away from the residence. The physical damage to the UTV goes unpaid as well. Even on the owner's own land, some policies exclude vehicles over a certain size or vehicles used for recreation, so the policy language deserves careful review.
Protecting Yourself from Liability for Guests and Young Riders
Owners who let friends or minors operate their ATV or UTV accept significant liability exposure. North Carolina law sets firm age and supervision rules, and violating them can make an owner or parent personally responsible for injuries. A specialized policy with strong liability limits addresses this exposure directly.
The rules for young riders are specific:
- Under 8: It is unlawful for parents to permit children under the age of 8 to operate any ATV.
- Under 16: Riders must remain under the continuous visual supervision of a person 18 or older.
- Passengers: Carrying passengers is prohibited unless the vehicle was specifically designed by the manufacturer for two or more riders.
Guest operators present a separate concern. When a neighbor's teenager takes a single-seat ATV for a ride with a friend on the back, two violations occur at once, and the injured passenger's family may pursue the owner. Policies vary in how they treat permissive operators, so owners should confirm that occasional guest riders are covered. The same passenger restriction appears in trauma prevention guidance, which reflects how often these injuries occur.
Comparing Homeowners vs. Specialized ATV Policies
| Coverage Feature | Typical Homeowners Policy | Specialized ATV/UTV Policy |
|---|---|---|
| Riding on your own land | Sometimes, limited | Yes |
| Riding on public trails | Usually excluded | Yes |
| Collision damage | Not included | Available |
| Theft away from home | Often excluded | Available |
| Guest operator liability | Rarely | Often available |
| Medical payments for riders | Limited or none | Available |
Navigating Off-Road and UTV Coverage Options
A well-designed off-road policy combines liability, collision, comprehensive, and medical payments coverage, with optional protection for accessories and safety gear. High net worth households with premium machines may be placed with specialized carriers such as Cincinnati or Hagerty, depending on eligibility and underwriting.
The core coverages generally work as follows:
- Collision: Pays to repair the vehicle after a rollover or impact with a tree, rock, or another machine.
- Comprehensive: Responds to theft, fire, vandalism, and storm damage. Specialized powersports policies offer coverage designed to protect against the high theft risk that ATVs and UTVs carry.
- Medical payments: Covers injuries to the operator and passengers regardless of fault.
- Uninsured motorist: Protects against other riders who carry no coverage.
Many owners overlook aftermarket parts. A UTV fitted with a winch, LED light bar, roof, and upgraded tires may carry thousands of dollars in additions that a base policy will not fully cover. Households with several high-value toys may also benefit from umbrella liability. Cincinnati and Hagerty may offer private client options that coordinate these exposures, though specific features depend on the policy issued.
The Benefits of Using an Independent Agent Near Me
An independent agency represents multiple carriers rather than one. It can compare ATV and UTV options side by side, so one company's underwriting preferences do not dictate the choice. That flexibility matters for families with young riders, multiple vehicles, or specialty machines. O'Connor Insurance Associates, an IIABA Best Practices Agency since 2010, follows an educational approach. The agency asks detailed questions about how, where, and by whom each vehicle is ridden before designing a program.
Common Questions About North Carolina Off-Road Coverage
Owners most often ask whether their homeowners policy is enough, whether young riders are covered, and what trail coverage requires. The short answers below address the questions Charlotte-area families raise most frequently.
Does my homeowners insurance cover my ATV on trails?
Usually not. Most homeowners policies exclude motorized vehicles once they leave the insured property.
Can my 12-year-old ride our ATV legally?
Yes, if an adult 18 or older keeps the child under continuous visual supervision. The child should also ride an age-appropriate machine.
Is a side-by-side insured the same way as an ATV?
Generally yes, though UTVs often carry higher values and seat passengers. Limits and physical damage coverage may need adjustment.
Will my policy cover a friend who borrows my UTV?
It depends on the permissive use language in the policy. Confirm this before lending the vehicle.
Do I need insurance to ride at Uwharrie?
Requirements can change, so check current rules before a trip. Carrying liability coverage is strongly advisable on any public trail system.
What if my ATV is stolen from my trailer at a campground?
Comprehensive coverage on a specialized policy typically responds. A homeowners policy often will not.
Making the Right Choice for Your Off-Road Protection
Specialized off-road coverage protects owners where homeowners policies stop. It extends to public trails and guest operators, and it applies when young riders take the controls. Matching liability to at least 50/100/50, and preferably higher, is a sound starting point for any North Carolina rider.
Reviewing North Carolina ATV insurance before the next trail weekend is far simpler than contesting a denied claim afterward. The vehicle's value, the household's riders, and the places the machine travels should all shape the policy.
O'Connor Insurance Associates is a licensed North Carolina insurance agency (license #7014004) located in Charlotte. It has served clients as an independent agency since 2000. To compare off-road and UTV coverage options, contact the agency at 704-510-8884 or visit 1973 JN Pease Place, Suite 203, Charlotte, North Carolina 28262.
Coverage descriptions are general. Policy terms, exclusions, limits and underwriting determine coverage.
Last updated:
On this page
O’Connor Insurance Associates is fully licensed to provide personal and commercial insurance solutions for individuals, families and businesses across North Carolina.
We proudly serve families and business owners from our office in Charlotte, North Carolina. As an independent, family-owned agency since 2000, our team works with more than one insurance company to make sure homeowners, drivers, contractors, landscapers, small businesses and other personal and commercial clients receive coverage that fits their real risks.

About the Author
President & Founder
I’m Terry O’Connor, President and Founder of O’Connor Insurance Associates. I grew up in Pennsylvania, earned my bachelor’s degree at Edinboro University and my master’s at Gannon University, and in 1998 I traded snow for sunshine and moved to Charlotte. In January 2000, I started this agency on my own because I wanted to help people protect what matters most to them. More than two decades later, we’ve grown into an independent agency serving families and businesses across North Carolina, and we’ve been recognized as an IIABA Best Practices Agency every year since 2010, a distinction held by fewer than 1% of agencies nationwide.
I’ve seen firsthand how the right protection can change a family’s or a business owner’s life, and that’s why I lead with empathy, education and honest advice. As an independent agent, I work for you, not for one insurance company. I take the time to explain your options in plain language, and when you call our office, you reach a real person who knows your account.
Outside the office, you’ll usually find me outdoors hunting or fishing, or on the mat coaching wrestling as an assistant varsity coach at Mallard Creek High School. I’m also a proud supporter of the arts, usually in the front row cheering on my daughter in local theater productions. I’d be glad to review your coverage with you. Call me at 704-510-8884 or email terry@oianc.com.
Relationships are the real measure
What our North Carolina clients say.
5.0 / 5
185 reviews on Google
Personal insurance
For the life you’re making.
Your home, your car, your time away. Let’s look at the whole picture.
Business insurance
For the business you’re building.
From established local companies to growing teams, we help make the coverage conversation clearer.
Your work deserves a closer look
Different businesses.
Different conversations.
We take time to understand what happens in your business every day.

Landscaping

Manufacturers

Technology Companies

HVAC Insurance

Electricians Insurance

Food Manufacturers
A little clarity goes a long way
Good questions.
Straight answers.
Have something else on your mind?
What does an independent insurance agency do?
An independent agency helps you compare options from more than one insurance company. We start with your needs, explain the differences and help you make an informed decision.
What can O’Connor help me insure?
Our team works with personal and business insurance, life and disability coverage, and Medicare options. Tell us what you need, and we’ll connect you with the right person.
Where does your agency serve clients?
We are based in Charlotte and serve clients across North Carolina. If your business operates in more than one state, call us to discuss your locations and coverage needs.
How do I get an insurance quote?
Start with the contact form or call 704-510-8884. We’ll ask about your situation and any current coverage, then review available options. Submitting a request does not bind coverage.
Can you help with an existing policy or claim?
Yes. Our Client Center page connects you with policy service, billing and claims options. You can also call during office hours for help finding the right next step.
What should I know before switching insurance?
Compare coverage, limits, exclusions and effective dates, not just the price. Speak with your agent before canceling an existing policy so you can coordinate the transition.
From our desk to yours
A little knowledge goes a long way.



Get a Quote
Let’s protect what you’re building.
Tell us a little about yourself. We’ll help you take the next step with a clearer picture of your options.
1973 J.N. Pease Place, Suite 203
Charlotte, NC 28262
Monday–Thursday · 9 AM–5 PM
Friday · 9 AM–3 PM
