
Myers Park, North Carolina
High Value Home Insurance.

Behind the stone walls and boxwood hedges of Myers Park sits some of the most complex residential property in Charlotte, and insuring it correctly requires more than a standard homeowners form. A 1920s Colonial Revival with hand-troweled plaster, a slate roof, and a century-old willow oak shading the driveway presents a combination of rebuild costs and liability exposures that conventional underwriting was never designed to measure.
Rising premiums have made accurate coverage design more pressing. North Carolina homeowners experienced a statewide average base rate increase of 7.5% effective June 1, 2026, the second phase of a two-year settlement. Separately, the North Carolina Department of Insurance reported that a 5% dwelling policy settlement saved consumers more than $268 million over what insurers had requested. For owners of historic estates, the practical question is not simply what a policy costs, but whether it would actually restore the home after a serious loss. The sections below address that question, covering historic construction, plaster and slate, the oak canopy, and the scheduling of fine art and collections.
The Unique Landscape of Myers Park North Carolina High Value Home Insurance
Myers Park homes require specialized coverage because their historic construction, period craftsmanship, and high replacement costs routinely exceed the limits and settlement methods of standard homeowners policies. O'Connor Insurance Associates, an independent agency serving Charlotte, North Carolina since 2000, designs private client programs that reflect the true cost of restoring these estates.
The neighborhood itself adds layers of complexity. Myers Park is governed by historic deed restrictions that "run with the land" and can override city zoning, including mandatory setbacks of up to 60 feet. Those restrictions can shape how, and where, a damaged home may be rebuilt, which is why ordinance and law coverage deserves careful review alongside dwelling limits.
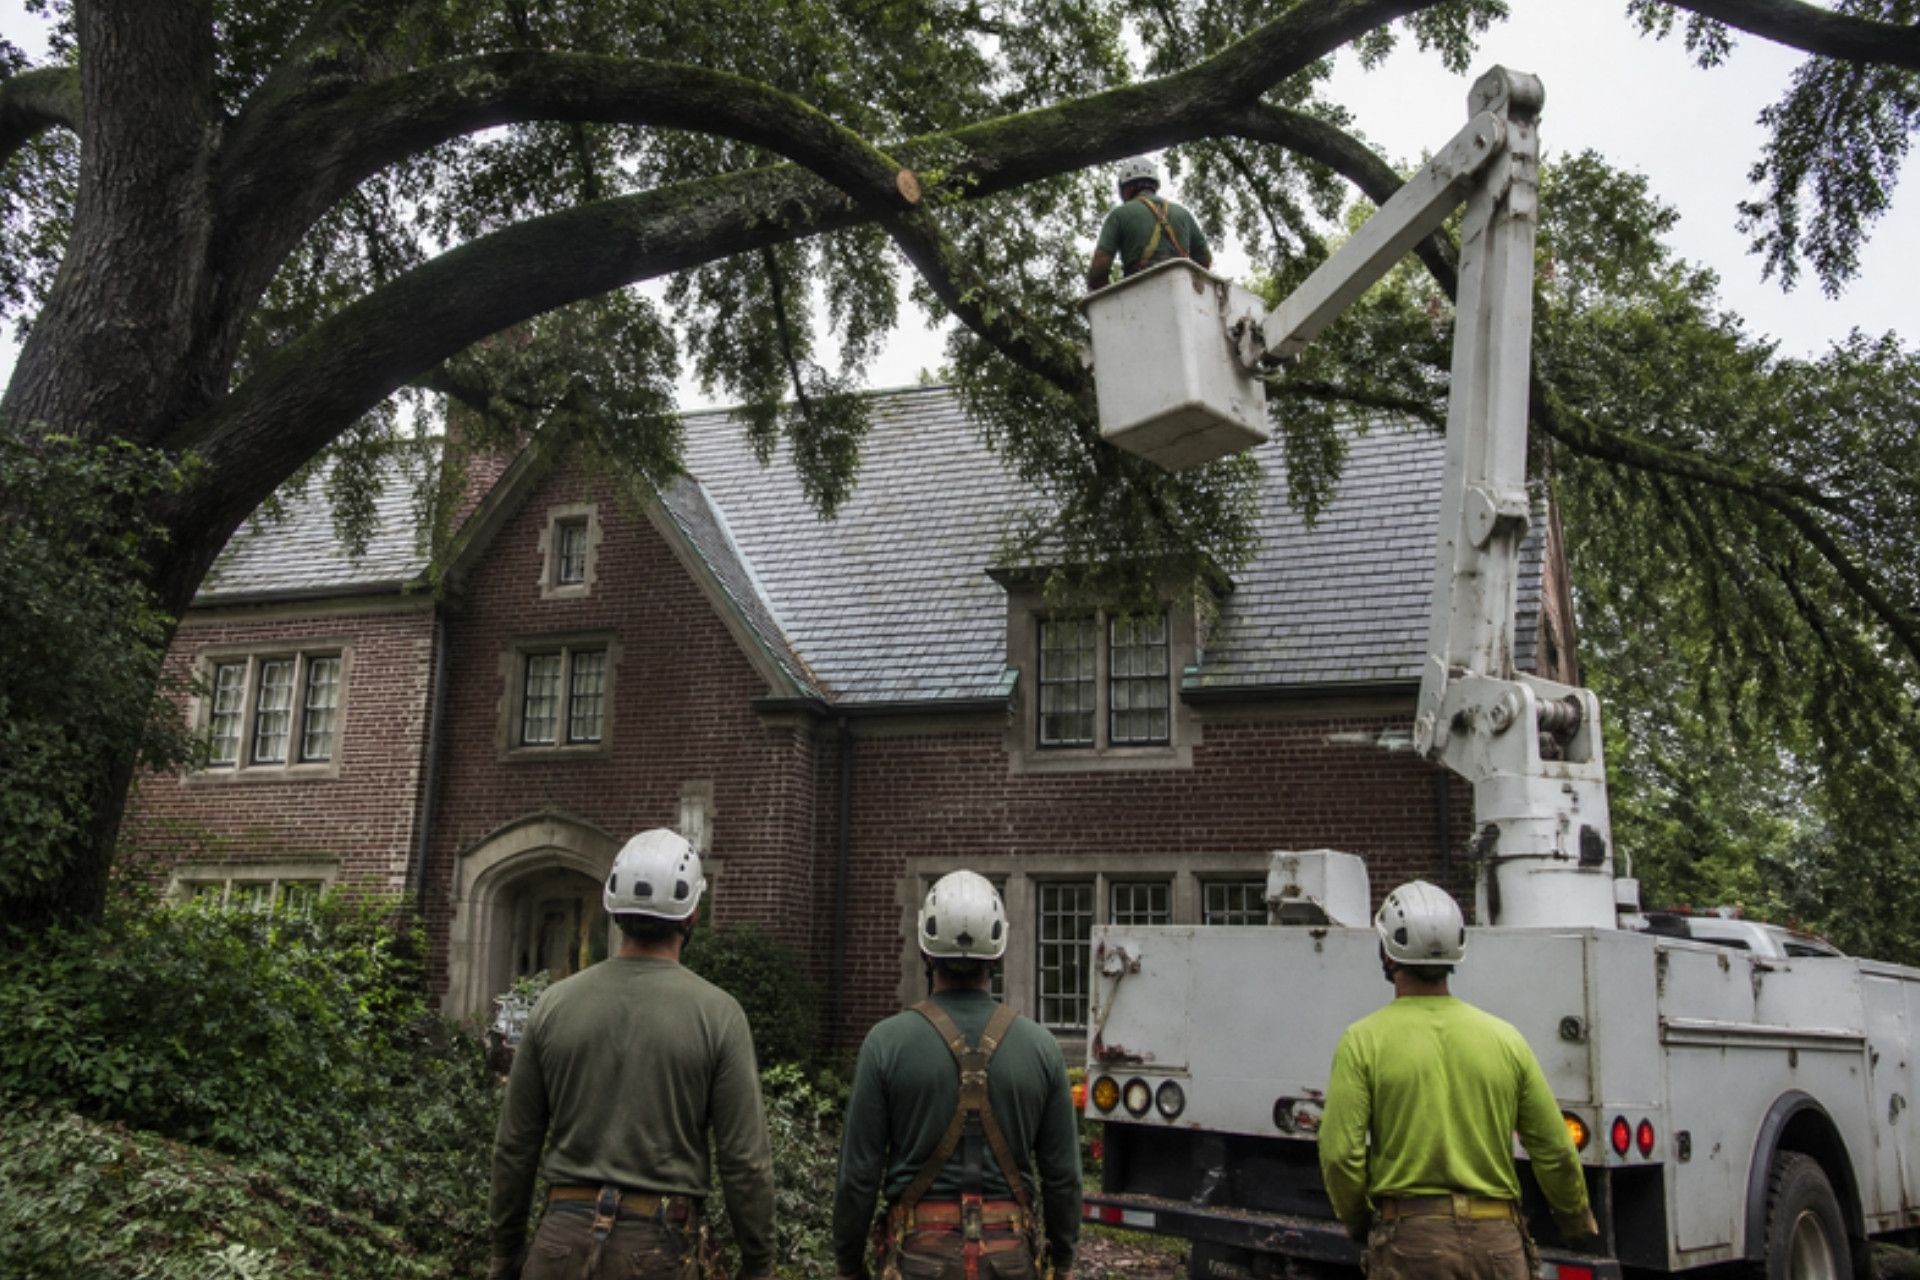
Insuring Historic 1910s to 1930s Estates
Estates built in Myers Park between the 1910s and 1930s were constructed with materials and methods that have largely disappeared from modern building: old-growth heart pine framing, solid masonry walls, custom millwork, leaded glass, and ornamental plaster moldings. When an insurer calculates replacement cost using generic per-square-foot estimates, the resulting dwelling limit often falls well short of what a qualified restoration contractor would charge.
Standard policies also tend to settle claims using "like kind and quality" language that a carrier may interpret as functionally equivalent modern materials. A homeowner expecting restored quarter-sawn oak paneling may be offered a settlement based on stock lumber instead. Several additional risks are common to homes of this era:
- Aging systems: Knob-and-tube wiring remnants, cast iron drain lines, and original plumbing can trigger water and fire losses.
- Code upgrades: Rebuilding to current code can add substantial cost that basic ordinance and law limits may not fully cover.
- Specialized labor: Artisans skilled in period restoration are scarce, which extends repair timelines and increases additional living expense needs.
A professional replacement cost appraisal, updated periodically, is the foundation of any well-designed policy for these homes.
Why Plaster and Slate Rebuild Costs Require Specialized Coverage
Authentic plaster and slate are among the most expensive building materials to repair or replace, and they often account for the largest gaps between a standard policy and an actual claim. A burst pipe in a modern home typically means cutting out and replacing drywall within days, while the same leak in a 1925 Myers Park residence may require a plasterer to rebuild lath, apply multiple coats, and recreate cornice profiles by hand.
Slate roofing presents a similar challenge. Quality slate can last a century or longer, yet replacing damaged sections demands matching stone, copper flashing, and installers trained in slate work, which few roofing crews possess. Asphalt shingles, by contrast, can be installed by most contractors quickly and at a fraction of the cost.
The protective answer is a guaranteed or extended replacement cost endorsement, which may pay above the stated dwelling limit when rebuild costs exceed expectations. Availability and terms vary by carrier, so homeowners should confirm whether the endorsement applies without a percentage cap and whether the policy explicitly commits to restoring original materials rather than substituting modern equivalents.
Managing Mature Oak Canopy Tree Claims
The willow oak canopy lining Queens Road and surrounding streets defines Myers Park, but those trees also generate some of the most frequent and costly claims in the neighborhood. A single limb failing during a summer thunderstorm or an ice event can puncture a slate roof, crush a copper gutter system, and damage plaster ceilings below, turning one tree into a five-part claim.
Debris removal limits deserve particular attention. Many standard North Carolina policies restrict tree removal coverage to a modest amount per tree and an aggregate cap per loss, and some pay only when the tree strikes a covered structure. Removing a mature oak from a tight lot often requires cranes and specialized crews whose fees can quickly exceed those limits.
Liability exposure runs in both directions. If a visibly diseased tree on one property falls onto a neighbor's home or injures a passerby, the owner may face a negligence claim. Routine arborist inspections, documented in writing, help demonstrate reasonable care, and adequate personal liability and umbrella limits provide the financial backstop when disputes arise.
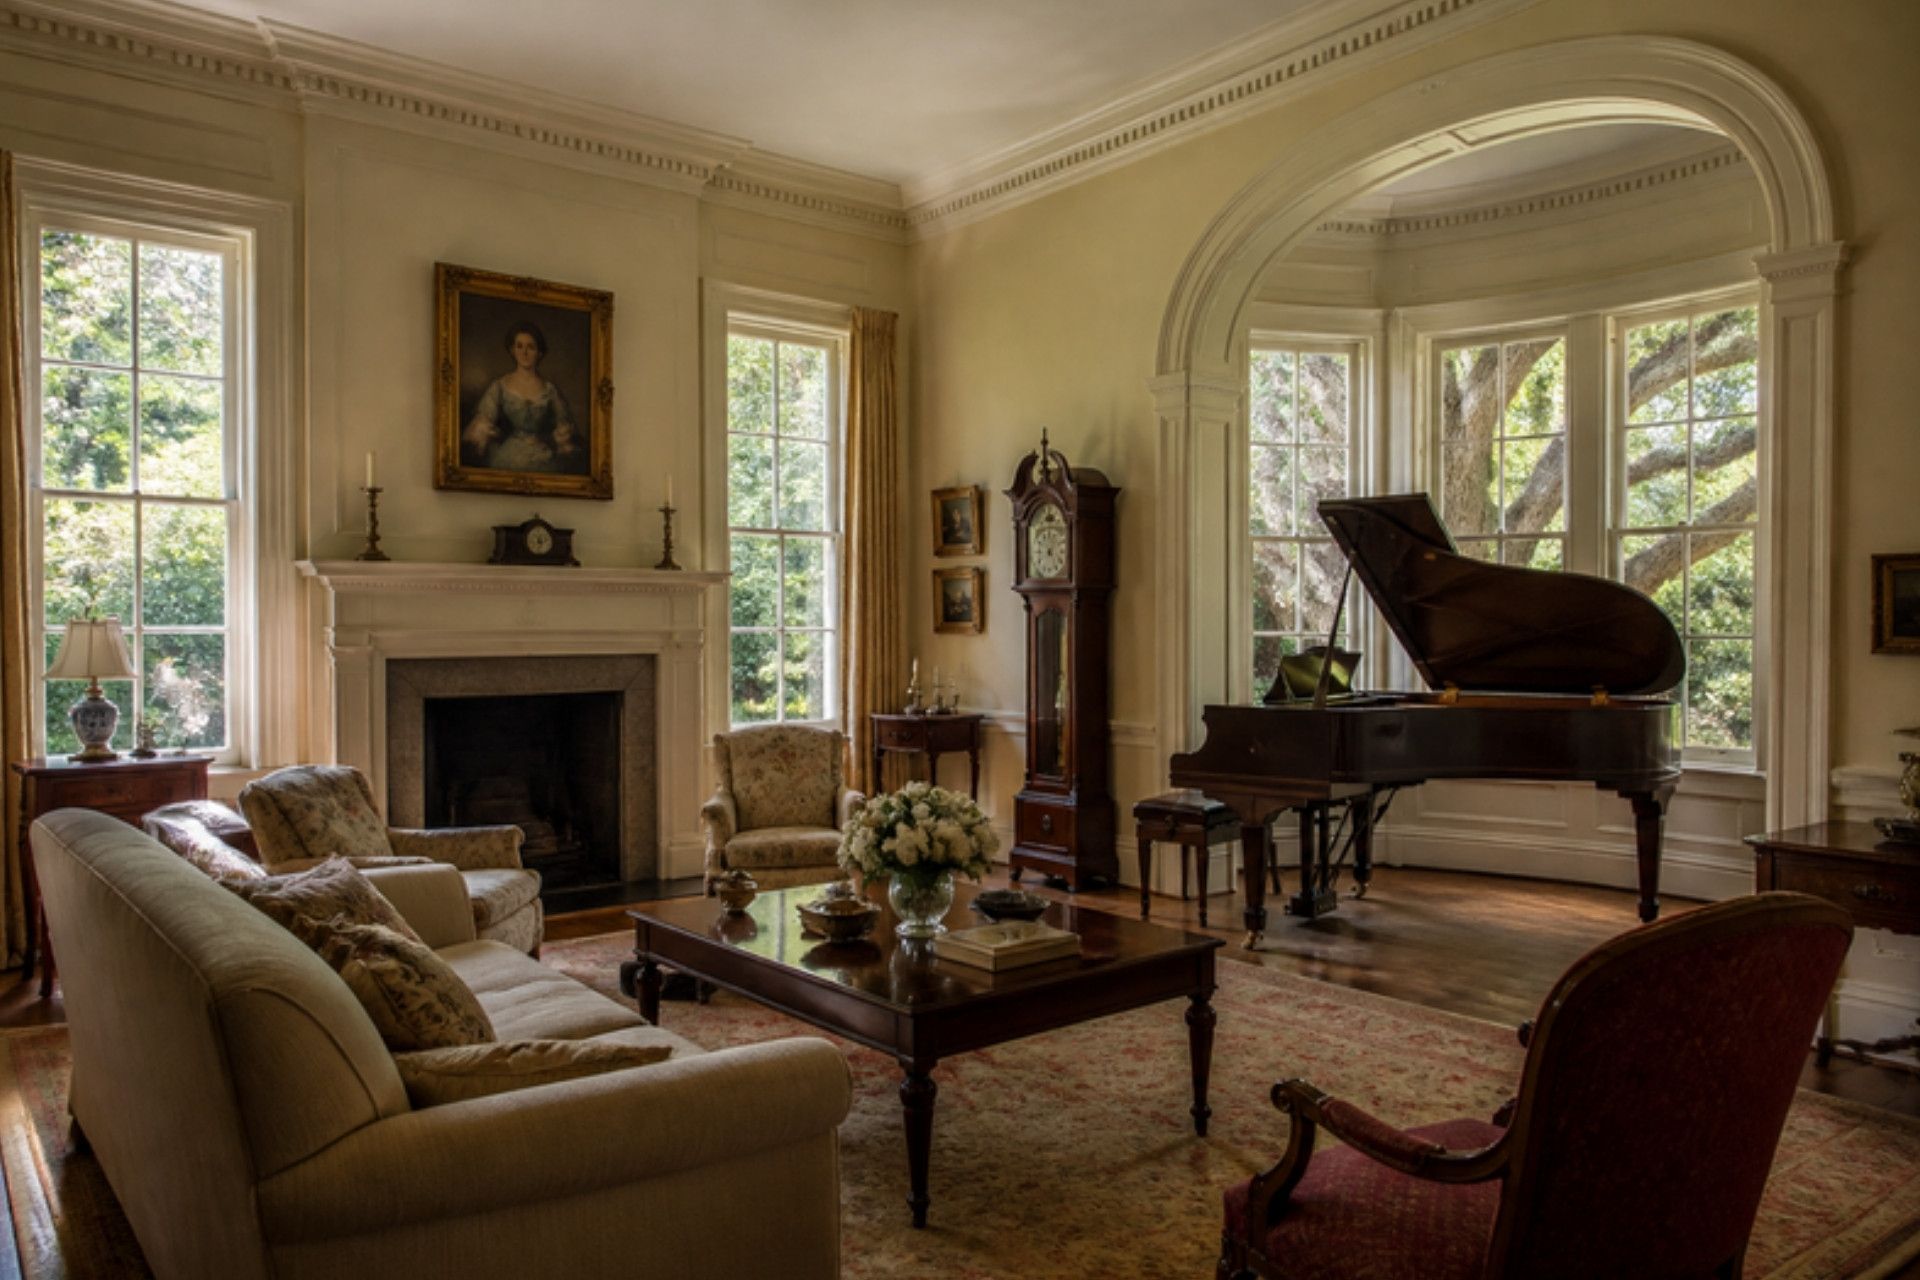
Scheduling Fine Art and Collections for Maximum Protection
Standard North Carolina homeowners policies impose sub-limits on categories such as jewelry, watches, silverware, furs, and firearms, often capping theft coverage at amounts far below the value of a single significant piece. Fine art may be covered under general contents, but usually without protection for accidental breakage and subject to depreciation at claim time.
Scheduling solves this problem by listing each item individually with an agreed value. The process generally follows these steps:
- Obtain current appraisals from qualified, credentialed appraisers who specialize in the relevant category.
- Gather documentation, including bills of sale, provenance records, certificates, and clear photographs.
- List each item on the schedule with its appraised value, which typically eliminates the deductible and the sub-limit.
- Confirm breakage and mysterious disappearance coverage, since these perils are frequently excluded under unscheduled contents.
- Reappraise every three to five years, because art and jewelry markets move and outdated values leave owners underinsured.
Collections of wine, antiques, rare books, or sports memorabilia can often be insured under blanket coverage with per-item maximums, which simplifies administration for larger holdings.
High Net Worth Carriers: Cincinnati and Hagerty
For these specialized risks, O'Connor Insurance Associates works primarily with Cincinnati and Hagerty as high net worth carriers. Each may offer private client features such as agreed value scheduling, broad collectibles coverage, and claims handling suited to historic homes, though specific terms depend on underwriting and policy forms. The agency is an independent agent, not the carrier itself.
The value of an independent agency lies in comparison and advocacy. Rather than receiving a single company's proposal, homeowners can review options side by side, ask questions about endorsements, and receive guidance at claim time. That matters as the market shifts: Nationwide fully exited the high-net-worth segment in 2024, and more high-value policies are moving to Excess and Surplus lines, which lack the backing of the North Carolina state guaranty fund.
Standard vs. High Value Policy Comparison
The following table highlights typical differences between a basic North Carolina homeowners policy and a private client high-value policy. Actual features vary by carrier and policy form.
| Feature | Standard Homeowners | Private Client High Value |
|---|---|---|
| Dwelling settlement | Replacement cost up to limit | Extended or guaranteed replacement cost may apply |
| Cash settlement option | Usually must rebuild to collect full cost | May allow cash settlement without rebuilding |
| Jewelry and art | Low theft sub-limits | Agreed value scheduling, often no deductible |
| Tree debris removal | Limited per tree and per loss | Higher limits often available |
| Liability limits | Commonly lower base limits | Higher limits, often paired with umbrella |
| Original materials | "Like kind and quality" | Restoration with historic materials may be included |
| Claims handling | General adjusters | Adjusters familiar with high-value homes |
Common Questions About Myers Park Home Coverage
Does my policy cover my slate roof if it's 80 years old?
Many high-value policies will cover an older slate roof if it is in sound condition, though some carriers apply roof age schedules or require inspections. Reviewing the roof settlement language before a storm is far preferable to discovering limitations afterward.
How do I value my art collection for insurance?
A credentialed appraiser specializing in fine art should prepare a written appraisal for each significant piece. Those values are then scheduled on the policy at an agreed amount and updated every few years.
Will my policy pay to remove a fallen oak that did not hit the house?
Often not under a standard form, since many policies pay for removal only when a tree damages a covered structure or blocks a driveway. Some private client policies provide broader tree coverage.
Do Myers Park deed restrictions affect my insurance?
They can, because setback and design requirements may influence how a home must be rebuilt. Adequate ordinance and law coverage helps absorb those added costs.
Is an umbrella policy necessary for a historic estate?
Most Myers Park homeowners benefit from an umbrella given the property values, household staff, entertaining, and tree liability exposures involved.
Making the Right Choice for Your Estate
Insuring a Myers Park estate correctly depends on accurate replacement cost valuation, endorsements that honor plaster and slate construction, realistic tree removal and liability limits, and properly scheduled fine art and collections. Each of these elements is easy to overlook in a generic policy, and each can determine whether a claim restores a home or leaves its owner absorbing the difference.
An experienced local agency brings familiarity with historic construction, neighborhood deed restrictions, and the carriers willing to underwrite these risks. O'Connor Insurance Associates has served Charlotte homeowners since 2000 with an educational approach, asking detailed questions so clients understand every coverage decision before they commit.
O'Connor Insurance Associates is a licensed North Carolina insurance agency (license #7014004). To request a review of an existing policy or a new private client proposal, contact the agency at 1973 JN Pease Place, Suite 203, Charlotte, North Carolina 28262, or call 704-510-8884. A home that has stood for a century deserves coverage built to see it through the next one.
Coverage descriptions are general. Policy terms, exclusions, limits and underwriting determine coverage.
Last updated:
On this page
O’Connor Insurance Associates is fully licensed to provide personal and commercial insurance solutions for individuals, families and businesses across North Carolina.
We proudly serve families and business owners from our office in Charlotte, North Carolina. As an independent, family-owned agency since 2000, our team works with more than one insurance company to make sure homeowners, drivers, contractors, landscapers, small businesses and other personal and commercial clients receive coverage that fits their real risks.

About the Author
President & Founder
I’m Terry O’Connor, President and Founder of O’Connor Insurance Associates. I grew up in Pennsylvania, earned my bachelor’s degree at Edinboro University and my master’s at Gannon University, and in 1998 I traded snow for sunshine and moved to Charlotte. In January 2000, I started this agency on my own because I wanted to help people protect what matters most to them. More than two decades later, we’ve grown into an independent agency serving families and businesses across North Carolina, and we’ve been recognized as an IIABA Best Practices Agency every year since 2010, a distinction held by fewer than 1% of agencies nationwide.
I’ve seen firsthand how the right protection can change a family’s or a business owner’s life, and that’s why I lead with empathy, education and honest advice. As an independent agent, I work for you, not for one insurance company. I take the time to explain your options in plain language, and when you call our office, you reach a real person who knows your account.
Outside the office, you’ll usually find me outdoors hunting or fishing, or on the mat coaching wrestling as an assistant varsity coach at Mallard Creek High School. I’m also a proud supporter of the arts, usually in the front row cheering on my daughter in local theater productions. I’d be glad to review your coverage with you. Call me at 704-510-8884 or email terry@oianc.com.
Relationships are the real measure
What our North Carolina clients say.
5.0 / 5
185 reviews on Google
Personal insurance
For the life you’re making.
Your home, your car, your time away. Let’s look at the whole picture.
Business insurance
For the business you’re building.
From established local companies to growing teams, we help make the coverage conversation clearer.
Your work deserves a closer look
Different businesses.
Different conversations.
We take time to understand what happens in your business every day.

Landscaping

Manufacturers

Technology Companies

HVAC Insurance

Electricians Insurance

Food Manufacturers
A little clarity goes a long way
Good questions.
Straight answers.
Have something else on your mind?
What does an independent insurance agency do?
An independent agency helps you compare options from more than one insurance company. We start with your needs, explain the differences and help you make an informed decision.
What can O’Connor help me insure?
Our team works with personal and business insurance, life and disability coverage, and Medicare options. Tell us what you need, and we’ll connect you with the right person.
Where does your agency serve clients?
We are based in Charlotte and serve clients across North Carolina. If your business operates in more than one state, call us to discuss your locations and coverage needs.
How do I get an insurance quote?
Start with the contact form or call 704-510-8884. We’ll ask about your situation and any current coverage, then review available options. Submitting a request does not bind coverage.
Can you help with an existing policy or claim?
Yes. Our Client Center page connects you with policy service, billing and claims options. You can also call during office hours for help finding the right next step.
What should I know before switching insurance?
Compare coverage, limits, exclusions and effective dates, not just the price. Speak with your agent before canceling an existing policy so you can coordinate the transition.
From our desk to yours
A little knowledge goes a long way.



Get a Quote
Let’s protect what you’re building.
Tell us a little about yourself. We’ll help you take the next step with a clearer picture of your options.
1973 J.N. Pease Place, Suite 203
Charlotte, NC 28262
Monday–Thursday · 9 AM–5 PM
Friday · 9 AM–3 PM
