

Waxhaw business owners face a mix of risks that generic policies rarely address in full: historic storefronts on Main Street, home offices that fall outside homeowners coverage, and crews moving equipment across Union County job sites. Sound Waxhaw, North Carolina business insurance matches coverage to how each operation actually works. An independent agency can compare several carriers to find that fit.
Waxhaw has grown considerably while keeping its small-town identity, and the business community reflects that balance. Boutiques and restaurants operate in century-old buildings along the railroad tracks. Consultants, bookkeepers, and online retailers run companies from spare bedrooms in newer subdivisions. Landscapers and contractors service the steady stream of residential and commercial projects throughout Union County and into southern Mecklenburg County.
Each of these business types carries a distinct risk profile, and the insurance market in 2026 is not uniform. Property rates have generally steadied, while liability pricing remains firm. The sections below outline how coverage typically works for each group, which policies tend to create gaps, and how carrier selection affects both price and protection for Waxhaw business owners.
Essential Waxhaw North Carolina Business Insurance for Local Success
Waxhaw businesses need tailored coverage because a retail shop, a home-based consultant, and a landscaping crew face very different claims. O'Connor Insurance Associates, an independent agency based in Charlotte since 2000, compares policies from multiple carriers so that each Waxhaw business receives coverage built around its actual operations rather than a generic package.
Tailored coverage matters because the market itself is uneven. Analysts note that excess liability and umbrella premiums remain high in 2026 due to social inflation, even as property rates stabilize. The same research documents a 116% year-over-year increase in the severity of so-called nuclear verdicts, which are jury awards far exceeding typical settlement values. For a small Waxhaw business, a single serious lawsuit can exceed a basic liability limit quickly.
A captive agent represents one company and can only offer that company's forms and pricing. An independent agency, by contrast, retains appointments with several carriers and can match a business to the underwriting appetite that suits it. A carrier that prices restaurants favorably may be less competitive for tree-trimming operations, and the reverse is often true as well.
O'Connor Insurance Associates, located at 1973 JN Pease Place, Suite 203, in Charlotte, has been recognized as an IIABA Best Practices Agency since 2010. The agency's approach centers on asking detailed questions before recommending coverage. Common topics include annual revenue, payroll, subcontractor use, equipment values, and the age and construction of any occupied building. Those details shape the policy far more than a business category alone.
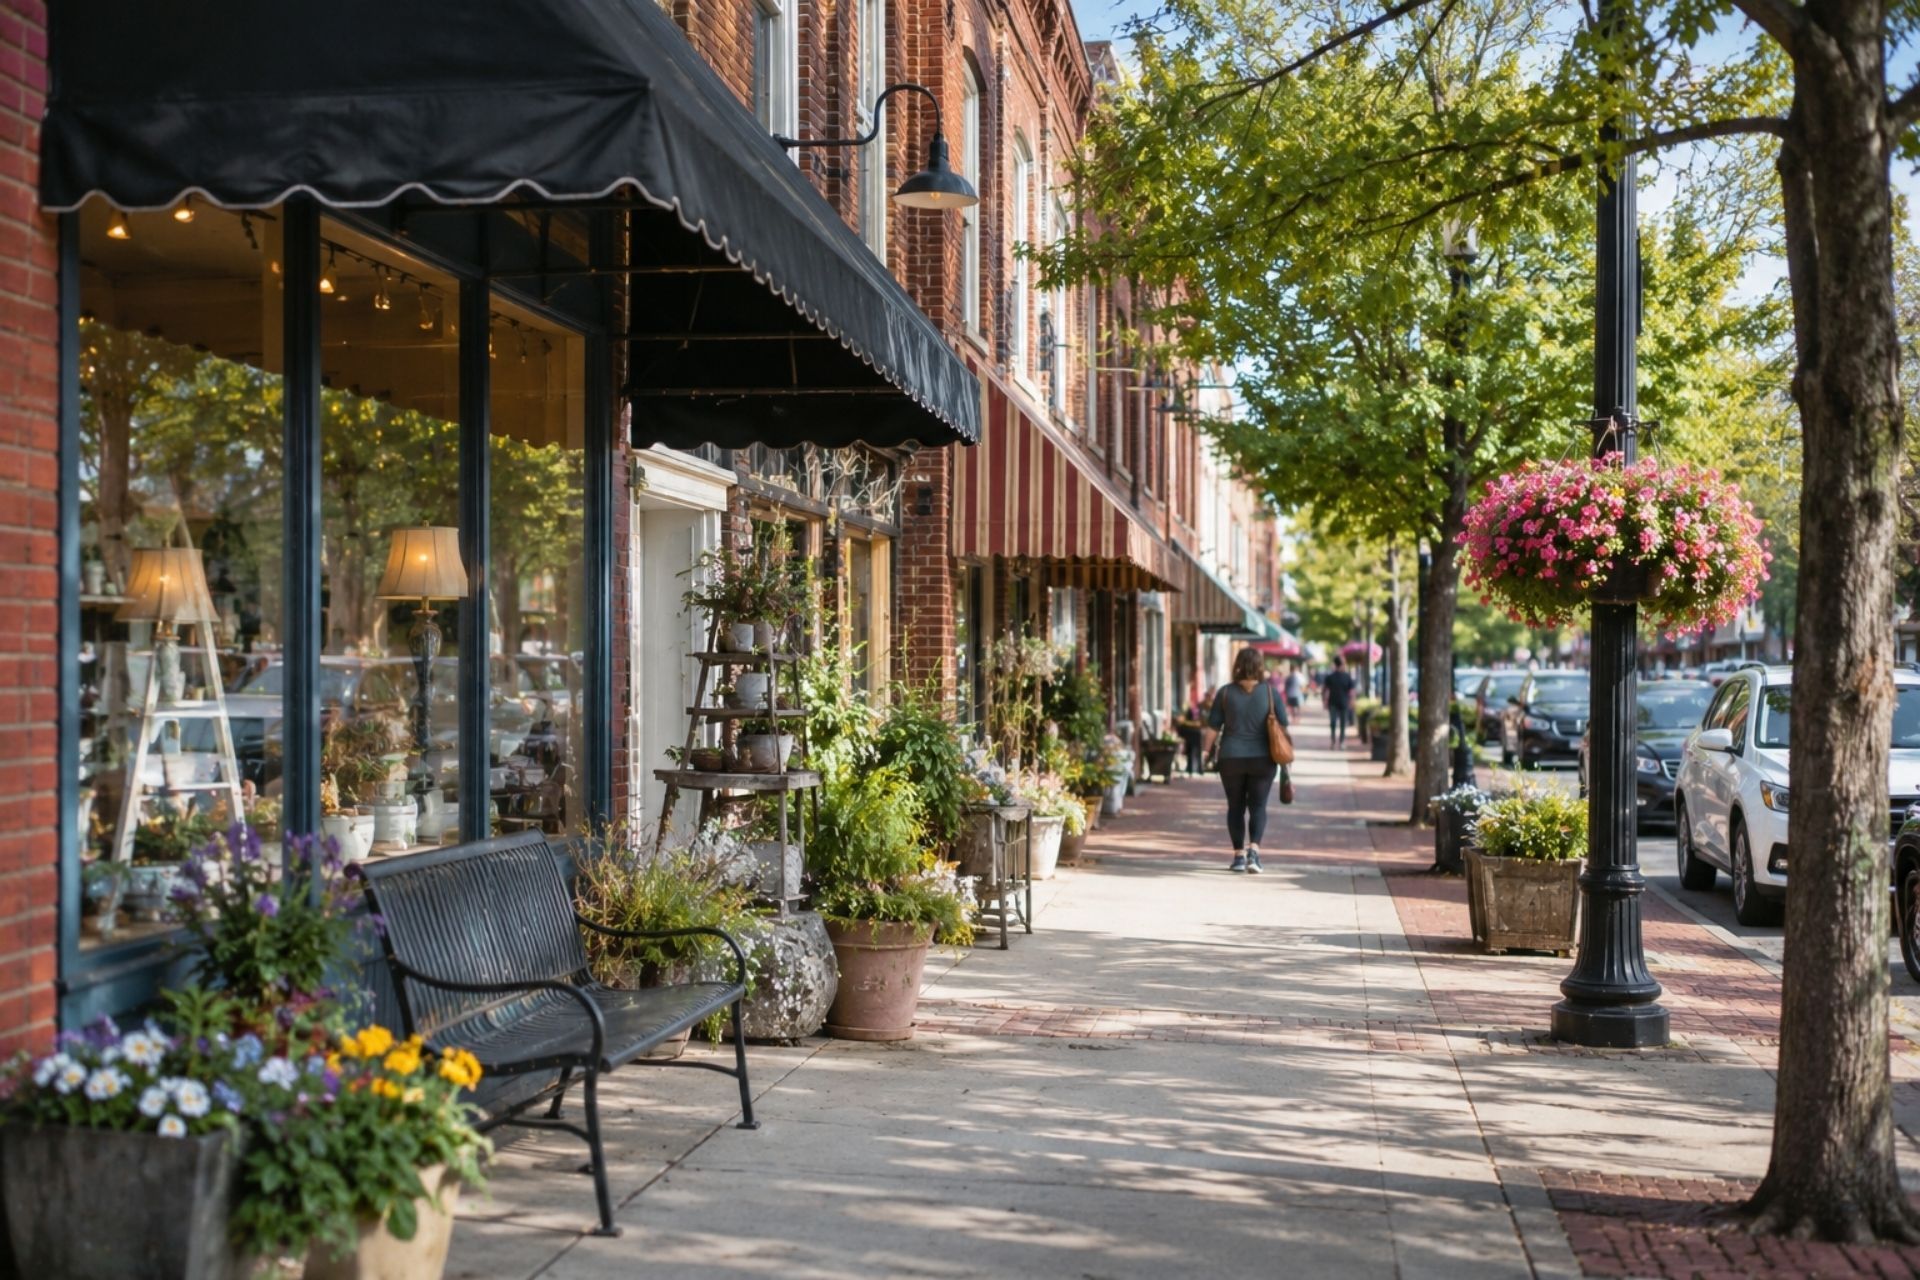
Protecting Downtown Waxhaw Shops and Retailers
Downtown Waxhaw shops need property coverage that reflects the true rebuilding cost of older buildings and liability coverage for customer injuries on uneven historic floors and sidewalks. A Business Owners Policy often serves as the foundation, with endorsements added for building ordinance requirements, equipment breakdown, and loss of income during repairs.
The downtown district presents conditions that newer strip centers do not. Many Main Street buildings feature older wiring, original masonry, wood framing, and shared walls with neighboring tenants. A fire that begins in one unit can damage inventory and fixtures in the next, and the question of which policy responds becomes complicated quickly. Retailers should review lease agreements carefully, because many leases assign specific insurance obligations to the tenant.
Growth is also reshaping the area. The Waxhaw Board of Commissioners adopted the Downtown Master Plan on October 28, 2025 to guide infrastructure and growth over the next five to ten years. Construction, streetscape changes, and increased foot traffic can affect both access to storefronts and the frequency of slip-and-fall exposures.
Several coverage elements deserve attention for downtown merchants:
- Ordinance or law coverage: Pays the added cost of bringing an older building up to current code after a covered loss, which standard property forms often limit.
- Business income and extra expense: Replaces lost revenue and covers temporary relocation costs while a damaged storefront is repaired.
- Equipment breakdown: Responds to failures of HVAC systems, refrigeration, and point-of-sale hardware.
- Premises liability: Addresses injuries from worn thresholds, steps, and narrow entryways common in historic structures.
- Valuable inventory limits: Confirms that seasonal stock increases, such as holiday merchandise, are reflected in policy limits.
A frequent mistake involves insuring a building for its market value rather than its replacement cost. Rebuilding period-appropriate construction usually costs more than the sale price suggests.
Liability Coverage for Landscapers and Contractors in Union County
Union County landscapers and contractors need general liability for property damage and injury claims, plus separate equipment coverage, because most liability policies do not protect tools. Carriers such as Erie, Travelers, and Cincinnati may offer contractor programs, and coverage features vary by carrier, trade, and underwriting review.
General liability addresses claims such as a mower throwing a rock through a homeowner's window, a crew member damaging an irrigation line, or a client tripping over materials at a job site. For solo landscaping operators in North Carolina, basic general liability averages $36 to $65 per month, while small crews of two to five employees typically spend $780 to $1,900 annually on insurance. Pricing shifts with services performed, since tree work and chemical application carry heavier exposures than routine mowing.
Contractors face additional expectations. North Carolina general contractors must maintain a $10,000 surety bond for licensure, though $1 million per occurrence in general liability has become the market standard for commercial projects. Developers and property managers commonly require certificates of insurance, additional insured endorsements, and waivers of subrogation before work begins.
Equipment is a separate concern. Most general liability policies for landscapers exclude tools in transit, which is why inland marine coverage is a high priority for Union County contractors seeking protection against theft between job sites. Mowers, trailers, compact loaders, and hand tools can represent tens of thousands of dollars in replacement value. Commercial landscaping firms are also focusing on specific risk management strategies in 2026 to protect profitability.
Workers Compensation Requirements in North Carolina
North Carolina requires workers compensation once a business reaches the employee threshold set under state law, and the North Carolina Industrial Commission enforces compliance. Seasonal and part-time workers generally count toward that threshold. Confirming headcount with an agent before hiring prevents both coverage gaps and penalties.
Audits create the most frequent problems. A primary industry pitfall for landscapers in 2026 involves workers comp audit surprises caused by misclassified seasonal payroll or underreported crew sizes. When a carrier audits at year-end and finds more payroll than estimated, the business receives an additional premium bill that can be substantial.
Subcontractors raise a related risk. Union County general contractors face significant audit penalties if they hire subcontractors who lack their own workers comp or general liability policies. The uninsured subcontractor's payroll is often added to the hiring contractor's policy. Collecting current certificates from every subcontractor, and keeping them on file, remains the simplest safeguard.
Commercial Auto Insurance for Service Vehicles
Personal auto policies frequently restrict or exclude coverage for vehicles used primarily for business, particularly trucks hauling trailers and equipment. A commercial auto policy covers liability and physical damage for those vehicles. It can also extend to employees who drive company trucks between Waxhaw, Monroe, and Indian Trail job sites.
Trailers deserve specific attention. Liability for a towed trailer generally follows the towing vehicle, but physical damage to the trailer itself must often be scheduled separately. Contractors who allow employees to use personal vehicles for errands should also ask about hired and non-owned auto coverage, which addresses liability when a non-company vehicle is involved in an accident during business use.
Insurance Solutions for Home-Based Businesses
Standard North Carolina homeowners policies often exclude or sharply limit business activities, including business property, client injuries, and professional errors. Home-based business owners in Waxhaw typically need either a home business endorsement for very small operations or a separate business policy when inventory, client visits, or income levels increase.
Many homeowners assume their existing policy covers a laptop, a shelf of inventory, or a client who visits for a consultation. In practice, homeowners forms commonly cap business personal property at a modest sublimit and exclude liability arising from business pursuits altogether. A client who slips on the front steps during a tax appointment may present a claim the homeowners carrier declines.
The right solution depends on the scale of the operation:
- Home business endorsement: Suitable for low-revenue operations with minimal inventory and few visitors; it extends limited property and liability protection under the homeowners policy.
- In-home business policy: A standalone form offering broader property limits, business income coverage, and liability for a modest premium.
- Business Owners Policy: Appropriate when revenue, inventory, or client traffic grows, or when contracts require specific limits.
- Professional liability: Necessary for consultants, designers, bookkeepers, and other advisers whose errors could cause financial loss to clients.
Online sellers face an added consideration, since product liability can follow merchandise even when sold through a marketplace platform. Disclosing business activity to the homeowners carrier is also important, because undisclosed operations can complicate unrelated home claims.
Comparing Common Business Coverage Options
General liability covers bodily injury and property damage to others, professional liability covers financial harm caused by advice or service errors, and a Business Owners Policy bundles general liability with property and business income coverage. Many Waxhaw businesses carry more than one of these, depending on their work.
The table below outlines the main differences in plain terms.
| Feature | General Liability | Professional Liability | Business Owners Policy (BOP) |
|---|---|---|---|
| Primary purpose | Injury and property damage to others | Financial loss from errors or advice | Bundled property and liability |
| Primary purpose | Injury and property damage to others | Financial loss from errors or advice | Bundled property and liability |
| Covers your property | No | No | Yes |
| Business income | No | No | Typically included |
| Who usually needs it | Nearly all businesses | Consultants, designers, advisers | Shops, offices, small service firms |
| Common gap | Excludes tools and professional errors | Excludes bodily injury | May exclude professional services |
A BOP often provides efficient pricing for eligible small businesses, though contractors with heavy equipment or higher-hazard operations may fall outside BOP eligibility. In those cases, a commercial package policy or standalone general liability combined with inland marine coverage tends to fit better. Given current liability market conditions, an umbrella policy above these limits deserves serious consideration for businesses with significant client contact or commercial contracts.
Carrier Options for Waxhaw Business Owners
O'Connor Insurance Associates typically begins with Erie, then considers Travelers, Cincinnati, Progressive, National General, Utica, and Foremost, depending on the business type. Each carrier has distinct underwriting preferences, and availability and coverage features vary by risk. The agency places coverage with these carriers and is not itself an insurance carrier.
Erie often serves as a starting point for many small businesses, as the carrier may offer competitive package policies for retail, office, and some contractor classes. Travelers generally provides broad commercial capabilities, including options that may suit growing contractors and businesses with larger property values. Cincinnati is frequently considered for established businesses seeking comprehensive package coverage and may offer favorable terms for well-managed accounts.
Progressive is commonly reviewed for commercial auto, particularly for contractors and landscapers operating pickup trucks and service vans. National General may provide additional auto and specialty options when a risk does not fit standard underwriting. Utica may be a suitable choice for certain commercial accounts, and Foremost is often considered for specialty dwelling situations relevant to some home-based business owners.
No single carrier suits every operation. A boutique on Main Street, a solo bookkeeper in a Waxhaw subdivision, and a ten-person hardscaping company may each end up with a different carrier. Comparing quotes across these companies allows the agency to weigh price, coverage forms, claims service, and eligibility together rather than in isolation.
Frequently Asked Questions About Waxhaw Business Coverage
These answers address the questions Waxhaw business owners raise most often. Coverage details depend on the specific operation, carrier, and policy form, so each answer serves as a general starting point. A conversation with a licensed agent can confirm how the guidance applies to a particular business in Union County.
Do I need insurance for a side hustle?
Usually, yes. Most homeowners policies limit or exclude business activity, so even a small side business can leave property and liability claims uncovered without an endorsement or separate policy.
How much coverage is required in Union County?
Union County does not set one universal amount, but licensing, leases, and contracts often do. Many commercial projects expect $1 million per occurrence in general liability, and workers compensation applies once a business meets North Carolina's employee threshold.
Will my general liability policy cover my mower if it gets stolen?
Typically not. Tools and equipment usually require inland marine coverage, especially while being transported between job sites.
Can I use my personal truck for my landscaping business?
A personal auto policy may restrict business use. Commercial auto coverage is generally the safer option for trucks hauling trailers or equipment.
Does a BOP cover mistakes in my professional advice?
No. A BOP focuses on property and general liability, so professional errors require a separate professional liability policy.
Why did my workers comp bill go up after the audit?
Audits compare estimated payroll to actual payroll. Additional seasonal workers or uninsured subcontractors frequently increase the final premium.
Making the Right Choice for Your Waxhaw Business
The right coverage begins with an honest review of operations, contracts, equipment, and buildings. Waxhaw shops, home-based businesses, landscapers, and contractors each face different gaps, and an independent agency comparing several carriers can design a program that addresses those gaps at a fair price.
Coverage gaps rarely appear until a claim arrives. A historic storefront without ordinance coverage, a home office relying on a homeowners policy, and a trailer of equipment without inland marine protection all share the same weakness: an assumption that went unchecked. Reviewing each policy annually, particularly after hiring, buying equipment, or signing a new lease, keeps protection aligned with the business as it grows.
Michelle O'Connor and the team at O'Connor Insurance Associates help business owners throughout Waxhaw and Union County compare options from Erie, Travelers, Cincinnati, and other carriers. To begin a coverage review, contact Michelle O'Connor at 704-510-8884 or visit the office at 1973 JN Pease Place, Suite 203, Charlotte, NC 28262. O'Connor Insurance Associates is a licensed North Carolina insurance agency (license #7014004).
Insurance serves as a safety net for the disaster no one planned for. Building that net carefully, before it is needed, gives a Waxhaw business room to keep growing with confidence.
Last updated:
On this page
O’Connor Insurance Associates is fully licensed to provide personal and commercial insurance solutions for individuals, families and businesses across North Carolina.
We proudly serve families and business owners from our office in Charlotte, North Carolina. As an independent, family-owned agency since 2000, our team works with more than one insurance company to make sure homeowners, drivers, contractors, landscapers, small businesses and other personal and commercial clients receive coverage that fits their real risks.

About the Author
President & Founder
I’m Terry O’Connor, President and Founder of O’Connor Insurance Associates. I grew up in Pennsylvania, earned my bachelor’s degree at Edinboro University and my master’s at Gannon University, and in 1998 I traded snow for sunshine and moved to Charlotte. In January 2000, I started this agency on my own because I wanted to help people protect what matters most to them. More than two decades later, we’ve grown into an independent agency serving families and businesses across North Carolina, and we’ve been recognized as an IIABA Best Practices Agency every year since 2010, a distinction held by fewer than 1% of agencies nationwide.
I’ve seen firsthand how the right protection can change a family’s or a business owner’s life, and that’s why I lead with empathy, education and honest advice. As an independent agent, I work for you, not for one insurance company. I take the time to explain your options in plain language, and when you call our office, you reach a real person who knows your account.
Outside the office, you’ll usually find me outdoors hunting or fishing, or on the mat coaching wrestling as an assistant varsity coach at Mallard Creek High School. I’m also a proud supporter of the arts, usually in the front row cheering on my daughter in local theater productions. I’d be glad to review your coverage with you. Call me at 704-510-8884 or email terry@oianc.com.
Relationships are the real measure
What our North Carolina clients say.
5.0 / 5
185 reviews on Google
Personal insurance
For the life you’re making.
Your home, your car, your time away. Let’s look at the whole picture.
Business insurance
For the business you’re building.
From established local companies to growing teams, we help make the coverage conversation clearer.
Your work deserves a closer look
Different businesses.
Different conversations.
We take time to understand what happens in your business every day.

Landscaping

Manufacturers

Technology Companies

HVAC Insurance

Electricians Insurance

Food Manufacturers
A little clarity goes a long way
Good questions.
Straight answers.
Have something else on your mind?
What does an independent insurance agency do?
An independent agency helps you compare options from more than one insurance company. We start with your needs, explain the differences and help you make an informed decision.
What can O’Connor help me insure?
Our team works with personal and business insurance, life and disability coverage, and Medicare options. Tell us what you need, and we’ll connect you with the right person.
Where does your agency serve clients?
We are based in Charlotte and serve clients across North Carolina. If your business operates in more than one state, call us to discuss your locations and coverage needs.
How do I get an insurance quote?
Start with the contact form or call 704-510-8884. We’ll ask about your situation and any current coverage, then review available options. Submitting a request does not bind coverage.
Can you help with an existing policy or claim?
Yes. Our Client Center page connects you with policy service, billing and claims options. You can also call during office hours for help finding the right next step.
What should I know before switching insurance?
Compare coverage, limits, exclusions and effective dates, not just the price. Speak with your agent before canceling an existing policy so you can coordinate the transition.
From our desk to yours
A little knowledge goes a long way.



Get a Quote
Let’s protect what you’re building.
Tell us a little about yourself. We’ll help you take the next step with a clearer picture of your options.
1973 J.N. Pease Place, Suite 203
Charlotte, NC 28262
Monday–Thursday · 9 AM–5 PM
Friday · 9 AM–3 PM
