

Affluent households in Charlotte, Cornelius, and Huntersville often hold assets that a standard homeowners or auto policy was never designed to protect. North Carolina high net worth insurance closes that gap through private client coverage for high value homes, jewelry and collections, collector cars, second homes, and high-limit umbrella liability. These policies are coordinated as a single program, so each asset is insured at a value that reflects what it would actually cost to replace.
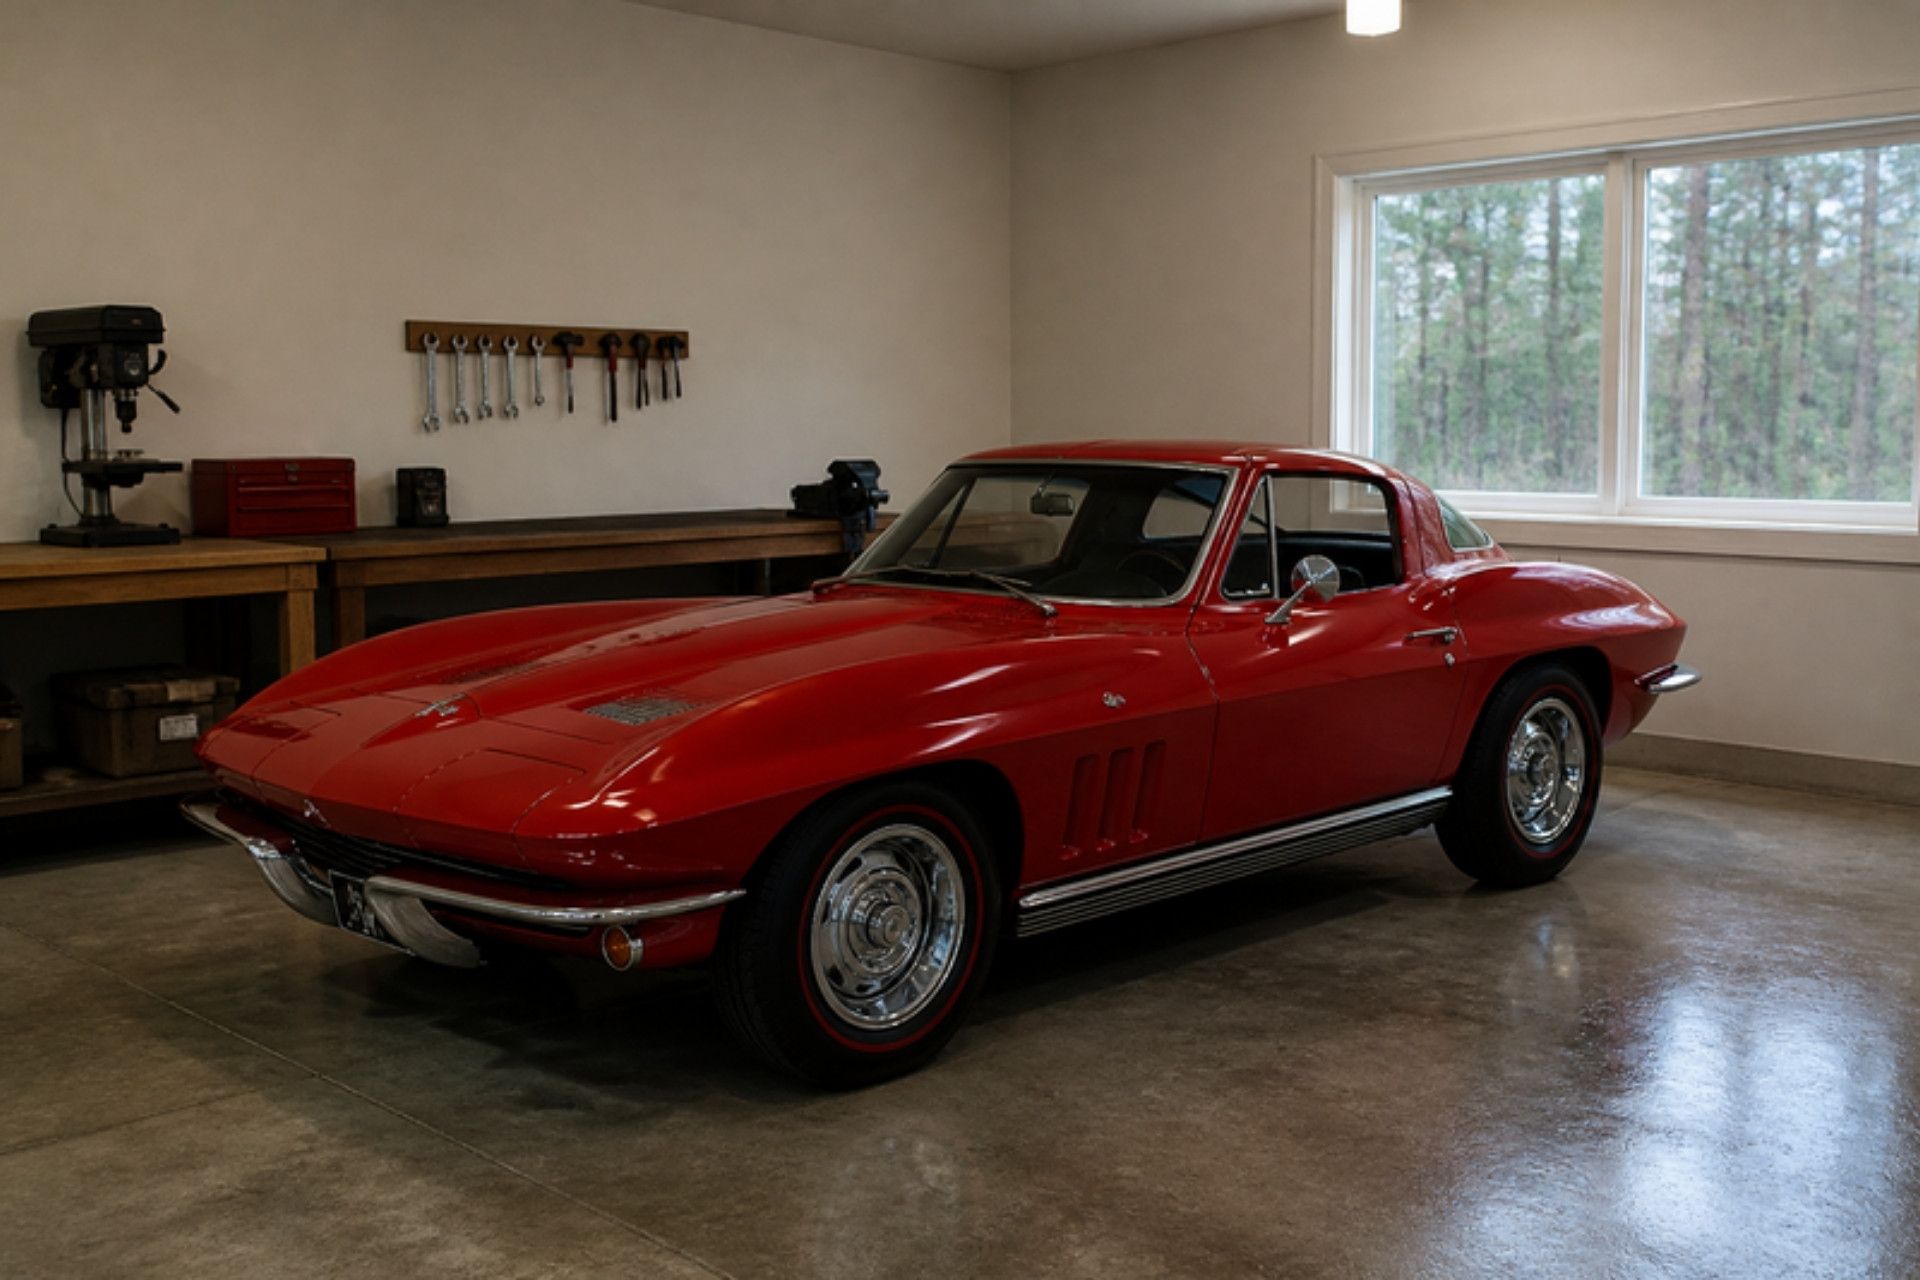
Consider a family whose waterfront property on Lake Norman includes a custom boathouse, a two-slip dock, and a wine cellar, along with a garage holding a restored 1967 Corvette. A conventional policy may cap the dock at a fraction of its cost, settle the Corvette at a depreciated figure, and offer no meaningful protection for the cellar. The gaps rarely surface at purchase. They surface after a loss, when the claim check arrives short.
Rising costs have made the issue more urgent. Effective June 1, 2026, the average statewide base rate for homeowners insurance in North Carolina increased by 7.5%, and many affluent families are reassessing whether their current coverage still matches their exposure.
Understanding North Carolina High Net Worth Insurance
North Carolina high net worth insurance is a category of personal coverage built for households with significant property, valuables, and liability exposure. It replaces mass-market forms with broader policies, higher limits, and specialized claims handling. Carriers such as Cincinnati Insurance, through its Executive Classic line, and Hagerty serve this segment.
O'Connor Insurance Associates, Inc. has operated as an independent agency in Charlotte, North Carolina since 2000 and has been recognized by the Independent Insurance Agents & Brokers of America (IIABA or the Big "I") as a Best Practices Agency since 2010. The agency specializes in private client coverage for affluent families in communities such as Lake Norman and Myers Park. Its appointed high net worth carriers are Cincinnati Insurance for the Executive Classic line and Hagerty for collector vehicles.
The distinction between standard and private client coverage involves more than higher limits. Private client policies generally provide broader definitions of covered loss, fewer exclusions, and settlement terms that favor replacement over depreciation. The coordinated design also means that homes, autos, valuables, and liability are reviewed together, which reduces the chance that one asset falls into a gap between two policies.
The broader market context is significant. The North Carolina property and casualty market generated approximately $28.3 billion in direct written premium in 2025, with growth moderating to 4.3% in 2026. Carrier appetite in this environment tends to favor well-documented, properly valued risks.
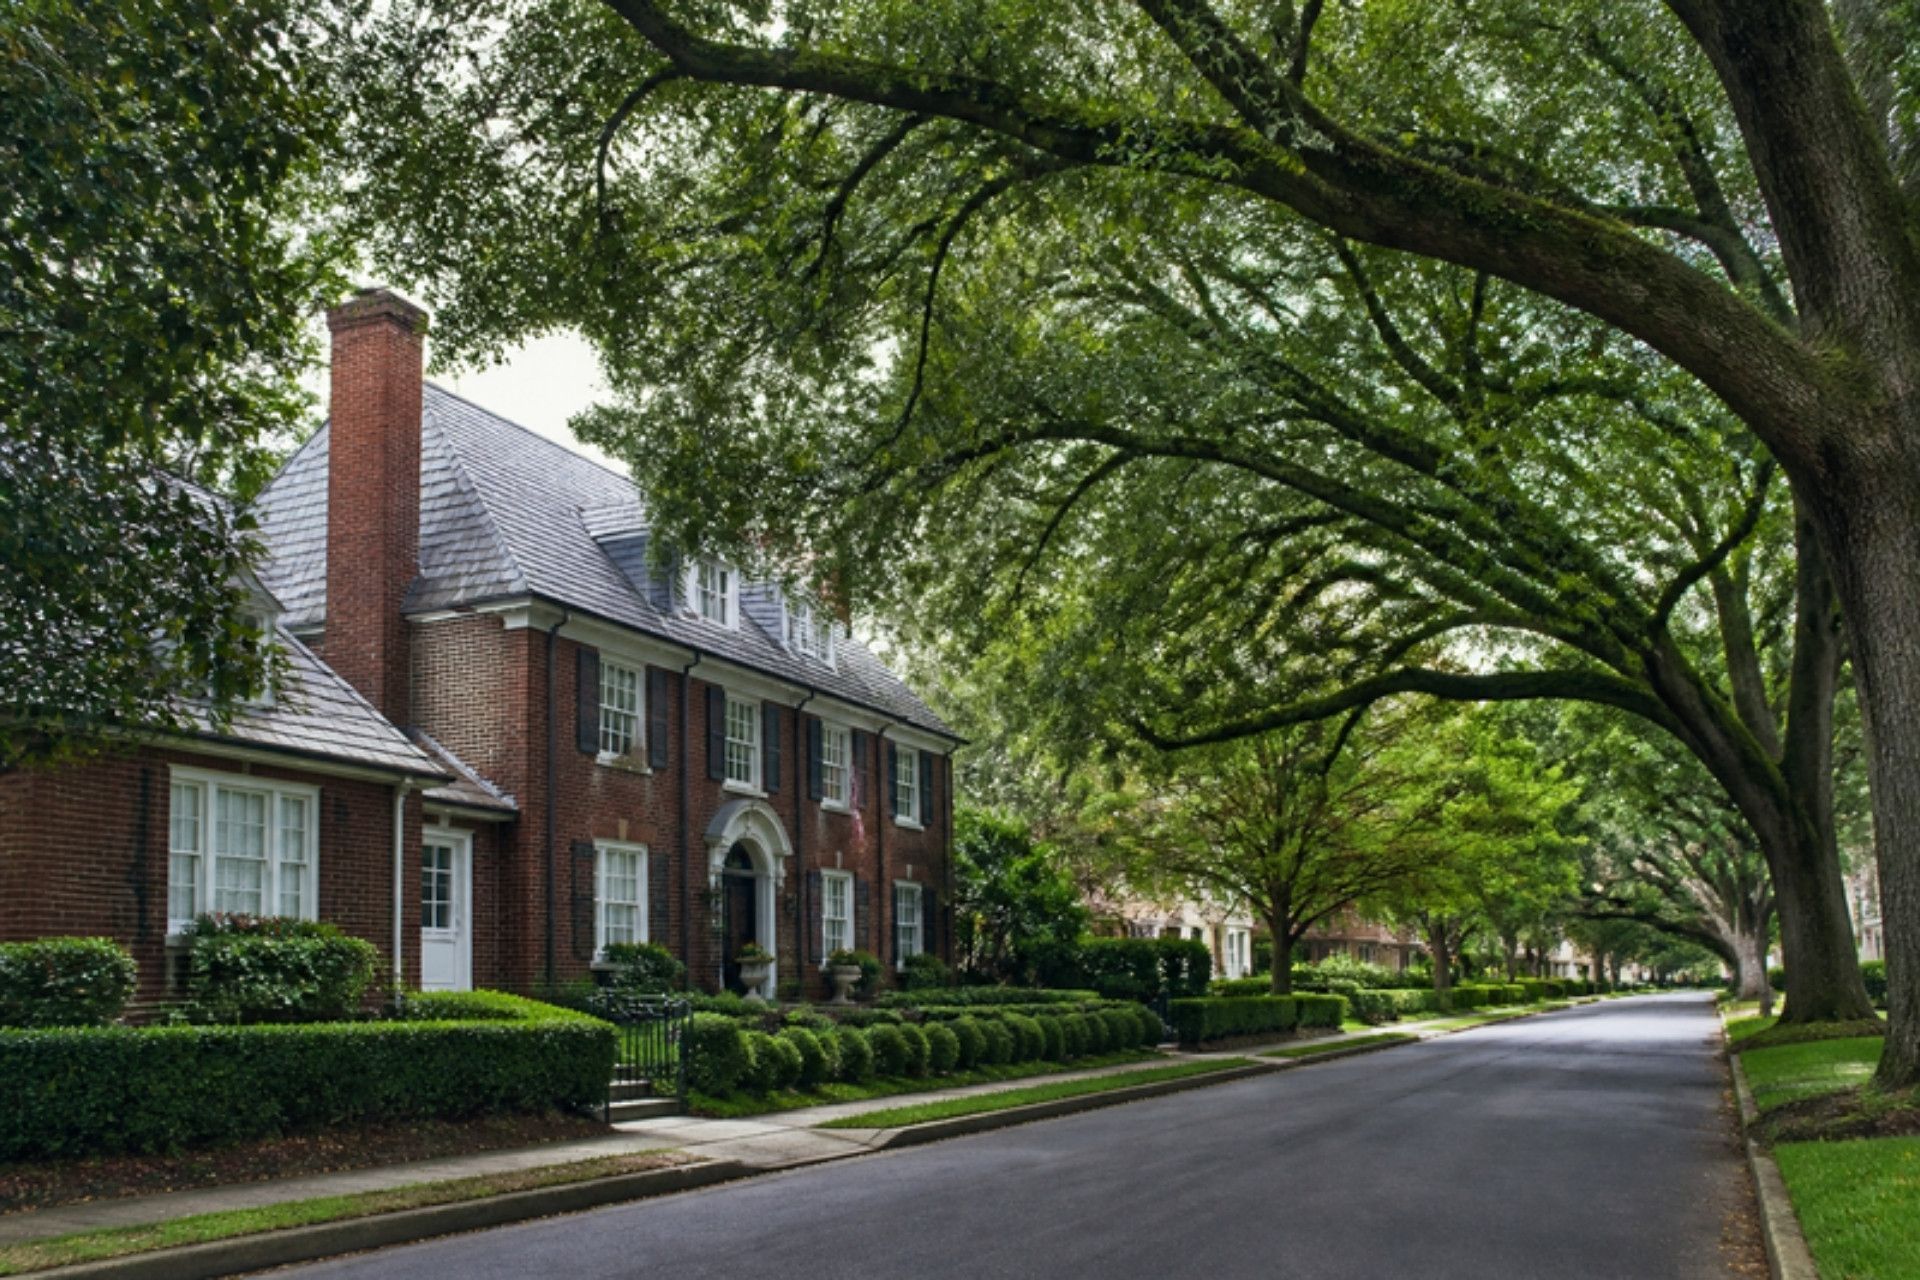
Insuring High Value Homes in Lake Norman and Myers Park
High value homes in Lake Norman and Myers Park frequently carry replacement costs that exceed the limits standard policies will write. Specialized forms, such as the Cincinnati Executive Classic line, are designed for these properties. They can include extended replacement cost provisions, higher limits on other structures, and coverage for custom materials and craftsmanship.
Property values in both communities have climbed sharply. As of July 2026, the median sale price in Myers Park reached $2,086,788, a 21.1% year-over-year increase. The median price for waterfront single-family homes in the Lake Norman four-county area was approximately $2.21 million in the first quarter of 2026. Market value and replacement cost are not the same figure, but rising prices often signal rising construction and labor costs as well.
Several coverage gaps appear repeatedly in reviews of homes in these neighborhoods:
- Docks and boathouses: Custom two-slip docks on Lake Norman can cost between $80,000 and $150,000 or more, which often exceeds the standard 10% "Other Structures" limit.
- Historic and custom finishes: Older Myers Park homes may feature plaster walls, slate roofs, and millwork that cost far more to reproduce than modern materials.
- Ordinance or law: Rebuilding to current code after a major loss can add expenses that basic forms cover only partially.
- Water backup and sump overflow: These losses are often excluded or sub-limited unless an endorsement is added.
An executive-level homeowners form, depending on the carrier's terms and the property's characteristics, may address many of these issues in the base policy rather than through a patchwork of endorsements. A professional replacement cost appraisal remains the foundation of an accurate limit.
Protecting Valuable Jewelry and Private Collections
Standard North Carolina homeowners policies often apply low sub-limits to theft of jewelry, watches, furs, silverware, and firearms. Scheduled personal property coverage lists each item at an appraised value, which can extend protection to mysterious disappearance and accidental loss and typically settles without a deductible.
A common client mistake is assuming that the personal property limit on a homeowners policy applies equally to every possession. In practice, a ring worth $40,000 may be covered for only a small fraction of that amount if it is stolen, because the theft sub-limit for jewelry is fixed in the policy form. A lost stone, a dropped watch, or a bracelet that slips off at the lake may not qualify as a covered loss at all under named-peril terms.
Scheduling solves both problems. Each item is described and valued on the policy, often using a recent appraisal or sales receipt, and the scheduled amount becomes the basis for settlement. Fine art, antiques, rare books, wine, and sports memorabilia can be scheduled individually or, depending on the carrier, insured under a blanket limit for the collection.
Documentation matters as much as the coverage itself. Appraisals should be updated periodically, particularly for gold and diamonds, whose market values fluctuate. Photographs, certificates of authenticity, and storage details for wine or art should be kept outside the home so they remain available after a fire.
Collector Car Insurance for North Carolina Enthusiasts
Collector vehicles are typically insured on an agreed value basis, meaning the owner and carrier settle on the car's worth before a loss occurs. Hagerty is widely recognized as a premier carrier for collector cars, and its policies generally pay the agreed amount after a total loss rather than a depreciated figure.
Daily drivers are usually insured on an actual cash value basis, which accounts for depreciation, mileage, and condition. That approach works reasonably well for a five-year-old SUV but fails for a restored classic, a limited-production sports car, or a vintage truck whose value may be rising. An actual cash value settlement on a collector car can leave the owner far short of the cost of acquiring a comparable vehicle.
Agreed value coverage, as offered through Hagerty, is designed for vehicles that are maintained, stored securely, and driven on a limited basis. Depending on the policy terms, eligible owners may also find options for spare parts, roadside service suited to classic vehicles, and coverage while traveling to shows and events across North Carolina. Owners should keep restoration receipts and recent photographs, since these support the agreed value at renewal.
Managing Risks for Second Homes and Coastal Properties
North Carolina residents with secondary residences, whether a lake cottage, a mountain retreat, or a coastal home, need an integrated portfolio so that liability, property limits, and deductibles align across locations. Separate policies from unrelated carriers frequently create gaps in umbrella coordination, rental exposure, and vacancy provisions.
The most frequent gap involves umbrella liability. An excess policy typically requires specific underlying limits on every residence and vehicle it sits above. When a vacation home is insured separately with lower liability limits, the umbrella may not respond as expected, or the owner may face a self-insured gap between the two layers.
Several other issues deserve attention for second homes:
- Vacancy and unoccupancy clauses may restrict coverage for water damage or vandalism when a home sits empty for extended periods.
- Short-term rental activity can change the risk profile and may require endorsements or a different policy form.
- Coastal properties often carry separate wind and hail deductibles, which can be calculated as a percentage of dwelling coverage.
- Flood is excluded from virtually all homeowners forms and must be addressed separately.
Placing primary and secondary residences within a coordinated private client program, where carrier eligibility allows, simplifies renewals, aligns deductibles, and ensures the umbrella sits on a consistent foundation.
The Necessity of High-Limit Umbrella Liability
Excess liability, commonly called an umbrella, provides additional protection above home, auto, and watercraft policies. North Carolina high net worth individuals generally need limits far beyond the state auto minimums of 50/100/50, effective July 1, 2025, because their visible assets make them more likely targets of lawsuits.
North Carolina's minimum auto liability limits require $50,000 for bodily injury per person, $100,000 per accident, and $50,000 for property damage, effective July 1, 2025. Those figures represent a legal floor, not a recommendation. A single serious accident involving multiple injuries, lost wages, and long-term medical care can produce a judgment that exceeds those amounts many times over.
Affluent households carry exposures that compound this risk. Teenage drivers, boats on Lake Norman, swimming pools, household staff, board service for nonprofits, and frequent entertaining all increase the likelihood of a liability claim. Private client umbrella programs may offer limits well into the millions, along with coverage for defense costs and, depending on the form, personal injury claims such as libel or slander.
The appropriate limit depends on net worth, future earnings, and specific activities. A review should also confirm that underlying limits on every auto, residence, and watercraft meet the umbrella's requirements, since a mismatch can leave a costly gap.
Comparing Standard vs. Private Client Coverage
Private client coverage generally differs from standard insurance in valuation, scope, limits, and service. Standard policies are designed for typical homes and settle many claims on a depreciated basis, while private client forms emphasize replacement, broader perils, and coordinated protection across every asset.
| Feature | Standard Coverage | Private Client Coverage |
|---|---|---|
| Dwelling valuation | Replacement cost up to a stated limit | Often extended or guaranteed replacement options |
| Other structures | Commonly 10% of dwelling | Higher limits available for docks and boathouses |
| Jewelry theft | Low sub-limit | Scheduled at appraised value |
| Collector cars | Actual cash value | Agreed value through specialty carriers |
| Liability | Basic limits | High-limit umbrella coordination |
| Claims handling | General adjusters | Adjusters familiar with high value property |
The table highlights general distinctions, and exact terms vary by carrier and policy. Recent premium increases make the comparison more relevant: the June 2026 adjustment was the second half of a negotiated settlement that capped total increases at roughly 15% over two years. Rising costs encourage a closer examination of what each premium dollar actually purchases.
Cincinnati Agent Near Me
Homeowners searching for a Cincinnati Insurance agent are often seeking the Executive Classic line, a homeowners program designed for high value properties. Cincinnati Insurance distributes through independent agencies, and working with an independent agent such as Michelle O'Connor provides access to the line alongside professional guidance on coverage design.
People look for Cincinnati because of its reputation for executive-level homeowners forms, its local claims approach, and its ability to coordinate home, auto, valuables, and umbrella coverage. Popular policies include Executive Classic homeowners, personal auto, scheduled personal property, and personal umbrella liability.
Going through an independent agent rather than searching for a direct channel offers practical advantages. An independent agency compares options from multiple carriers, reviews whether the Executive Classic line fits a specific property, and advocates for the client at claim time. O'Connor Insurance Associates is an appointed agency and is not the carrier; underwriting decisions rest with Cincinnati Insurance.
To request a quote, homeowners should gather current declarations pages, details on renovations and outbuildings, and an inventory of valuables. The agency then reviews eligibility and presents coverage recommendations.
Hagerty Agent Near Me
North Carolina car collectors look for Hagerty because of its focus on classic and collector vehicles and its agreed value approach. An independent agency provides expert guidance on eligibility, valuation, storage requirements, and how a Hagerty policy coordinates with daily driver auto coverage and umbrella liability.
Hagerty is known for its collector car insurance, valuation resources, and enthusiast community. Popular policies generally include agreed value coverage for classic, antique, exotic, and modified vehicles, with options that may extend to spare parts and event travel, subject to policy terms.
An independent agent adds value by confirming that the umbrella recognizes the collector vehicle, that underlying limits are adequate, and that the agreed value reflects current market conditions. Quoting typically requires vehicle details, photographs, storage information, and a description of the driver's daily-use vehicles. O'Connor Insurance Associates serves as an appointed agency and does not issue Hagerty policies.
Common Questions About North Carolina Private Client Insurance
These answers address questions frequently raised during reviews of high net worth coverage across the greater Charlotte area, written in plain language for anyone new to private client insurance.
What counts as a high value home in North Carolina?
There is no single threshold, but homes with replacement costs well above typical neighborhood values, or with custom construction, usually qualify for private client forms.
Do I need to schedule my engagement ring?
Scheduling is generally advisable for any ring of significant value, because standard theft sub-limits are low and accidental loss may not be covered otherwise.
How is agreed value different from stated value?
Agreed value pays the amount set at the start of the policy after a total loss. Stated value typically pays the lesser of the stated amount or actual cash value.
How much umbrella coverage do I need?
The limit should reflect net worth, future income, and activities such as boating or teen drivers, and it often exceeds $1 million for affluent households.
Can my lake house and primary home be on the same program?
In many cases, yes, depending on carrier eligibility, and coordinating them helps avoid gaps in liability and deductibles.
Does homeowners insurance cover flooding at Lake Norman?
No. Standard and private client homeowners forms generally exclude flood, so separate flood coverage is needed.
Making the Right Choice for Your Assets
The right private client program begins with an accurate inventory of what a household owns and what it could lose. High value homes, scheduled valuables, collector vehicles, second homes, and umbrella liability should be designed together, with appraisals updated and limits reviewed annually.
Each asset category carries its own risk of underinsurance: a dock exceeding its other structures limit, a watch subject to a theft sub-limit, a Corvette settled at a depreciated value, or an umbrella that fails to sit cleanly over a vacation home. These problems are preventable when coverage is reviewed before a loss rather than after one. A comprehensive approach to North Carolina high net worth insurance treats every asset as part of a single financial picture.
O'Connor Insurance Associates, Inc., an independent agency serving Charlotte since 2000, offers access to the Cincinnati Executive Classic line and Hagerty collector vehicle coverage, along with an educational review process. To secure a comprehensive North Carolina insurance review, contact the agency at 704-510-8884 or visit the Charlotte office at 1973 JN Pease Place, Suite 203, Charlotte, North Carolina 28262.
Coverage descriptions are general. Policy terms, exclusions, limits and underwriting determine coverage.
Last updated:
On this page
O’Connor Insurance Associates is fully licensed to provide personal and commercial insurance solutions for individuals, families and businesses across North Carolina.
We proudly serve families and business owners from our office in Charlotte, North Carolina. As an independent, family-owned agency since 2000, our team works with more than one insurance company to make sure homeowners, drivers, contractors, landscapers, small businesses and other personal and commercial clients receive coverage that fits their real risks.

About the Author
President & Founder
I’m Terry O’Connor, President and Founder of O’Connor Insurance Associates. I grew up in Pennsylvania, earned my bachelor’s degree at Edinboro University and my master’s at Gannon University, and in 1998 I traded snow for sunshine and moved to Charlotte. In January 2000, I started this agency on my own because I wanted to help people protect what matters most to them. More than two decades later, we’ve grown into an independent agency serving families and businesses across North Carolina, and we’ve been recognized as an IIABA Best Practices Agency every year since 2010, a distinction held by fewer than 1% of agencies nationwide.
I’ve seen firsthand how the right protection can change a family’s or a business owner’s life, and that’s why I lead with empathy, education and honest advice. As an independent agent, I work for you, not for one insurance company. I take the time to explain your options in plain language, and when you call our office, you reach a real person who knows your account.
Outside the office, you’ll usually find me outdoors hunting or fishing, or on the mat coaching wrestling as an assistant varsity coach at Mallard Creek High School. I’m also a proud supporter of the arts, usually in the front row cheering on my daughter in local theater productions. I’d be glad to review your coverage with you. Call me at 704-510-8884 or email terry@oianc.com.
Relationships are the real measure
What our North Carolina clients say.
5.0 / 5
185 reviews on Google
Personal insurance
For the life you’re making.
Your home, your car, your time away. Let’s look at the whole picture.
Business insurance
For the business you’re building.
From established local companies to growing teams, we help make the coverage conversation clearer.
Your work deserves a closer look
Different businesses.
Different conversations.
We take time to understand what happens in your business every day.

Landscaping

Manufacturers

Technology Companies

HVAC Insurance

Electricians Insurance

Food Manufacturers
A little clarity goes a long way
Good questions.
Straight answers.
Have something else on your mind?
What does an independent insurance agency do?
An independent agency helps you compare options from more than one insurance company. We start with your needs, explain the differences and help you make an informed decision.
What can O’Connor help me insure?
Our team works with personal and business insurance, life and disability coverage, and Medicare options. Tell us what you need, and we’ll connect you with the right person.
Where does your agency serve clients?
We are based in Charlotte and serve clients across North Carolina. If your business operates in more than one state, call us to discuss your locations and coverage needs.
How do I get an insurance quote?
Start with the contact form or call 704-510-8884. We’ll ask about your situation and any current coverage, then review available options. Submitting a request does not bind coverage.
Can you help with an existing policy or claim?
Yes. Our Client Center page connects you with policy service, billing and claims options. You can also call during office hours for help finding the right next step.
What should I know before switching insurance?
Compare coverage, limits, exclusions and effective dates, not just the price. Speak with your agent before canceling an existing policy so you can coordinate the transition.
From our desk to yours
A little knowledge goes a long way.



Get a Quote
Let’s protect what you’re building.
Tell us a little about yourself. We’ll help you take the next step with a clearer picture of your options.
1973 J.N. Pease Place, Suite 203
Charlotte, NC 28262
Monday–Thursday · 9 AM–5 PM
Friday · 9 AM–3 PM
