

Medicare Supplement coverage in North Carolina gives people enrolled in Original Medicare a way to fill the cost gaps that Parts A and B leave behind. The decisions that matter most are choosing between Plan G and Plan N, applying during a protected enrollment window, and comparing carriers before selecting a policy.
Residents across the greater Charlotte area, from Highland Creek and Huntersville to Concord, Cornelius, and Harrisburg, often begin this research a few months before their 65th birthday. That timing is sound, because the rules governing Medigap enrollment reward early preparation and can penalize delay. Two neighbors with identical coverage may pay very different monthly premiums depending on when they applied and which carrier issued the policy. The following guide explains each decision point in sequence, so that a choice made today continues to serve well for years to come.
Understanding North Carolina Medicare Supplement Plans
North Carolina Medicare Supplement plans, also called Medigap, are private insurance policies that help pay costs Original Medicare does not fully cover, such as deductibles, coinsurance, and copayments. North Carolina SHIIP, the Seniors' Health Insurance Information Program, provides free, unbiased counseling to residents who are comparing these options.
Medigap plans are standardized by letter, which means a Plan G issued by one carrier provides the same basic benefits as a Plan G issued by another carrier operating in North Carolina. What differs between carriers is the premium, the method used to calculate future rate increases, the company's financial strength, and the quality of its customer service. That standardization explains why comparison shopping produces real savings without any reduction in coverage.
A Medicare Supplement works alongside Original Medicare rather than replacing it. The policyholder keeps Parts A and B, and the supplement pays its share after Medicare processes a claim. Prescription drug coverage is not included in a Medicare Supplement.
North Carolina also offers protections beyond the federal minimums. Under state law G.S. 58-54-45, individuals under 65 who qualify for Medicare because of a disability havespecified Medigap purchase rights, a provision that many younger beneficiaries do not realize applies to them. For those first eligible on or after January 1, 2020, insurers must make Plan A available, and also Plan D or G if they market that plan to age-eligible beneficiaries, subject to the statutory application window: generally within six months of first Part B enrollment, with special timing for retroactive enrollment and certain managed care terminations. Earlier eligibility has different plan-letter rules. SHIIP counselors and the North Carolina Department of Insurance can confirm the applicable right before you rely on it.
Comparing Plan G vs Plan N in North Carolina
Plan G offers the most comprehensive coverage available to people newly eligible for Medicare, while Plan N typically carries a lower monthly premium in exchange for copayments on some office and emergency room visits. Both plans leave the annual Part B deductible as the enrollee's responsibility.
The practical difference comes down to how a person uses medical care and how much predictability matters. Plan G functions much like a fixed-cost arrangement once the Part B deductible is met, while Plan N asks the policyholder to share small costs at the point of service. Coverage details are standardized, but individual circumstances should always be reviewed with a licensed professional before purchase.
| Feature | Plan G | Plan N |
|---|---|---|
| Part B deductible | Paid by enrollee | Paid by enrollee |
| Part B excess charges | Covered | Not covered |
| Office visit copays | None | Copay on some visits |
| Emergency room copays | None | Copay on some visits |
| Typical premium | Higher | Lower |
Excess charges deserve particular attention. A provider who does not accept Medicare assignment may bill up to 15 percent above the Medicare-approved amount, and Plan N leaves that difference with the patient. In practice, many physicians in the Charlotte area accept assignment, but a client who sees out-of-network specialists at academic medical centers may encounter these charges unexpectedly.
Premium figures illustrate the trade-off. Based on rate filings as of fall 2026, the lowest filed rate for a 65-year-old female in Charlotte (ZIP 28202) was $113.59 per month for Plan G, compared with $85.10 for Plan N. Across North Carolina, Plan G premiums for a 65-year-old ranged from $113.59 to as high as $315.20 in those filings, which shows how much the carrier selection affects cost for identical benefits. Rates change with each filing, so current quotes will differ.
Medigap Open Enrollment and Underwriting Protections
The Medigap open enrollment window lasts six months, beginning on the first day of the month in which a person is both 65 or older and enrolled in Medicare Part B. During this period, carriers may still ask health questions on the application, but they cannot use the answers to deny coverage or charge more because of preexisting conditions.
This six-month window is the single most valuable timing protection in the Medicare Supplement market. Once it closes, carriers in North Carolina may generally require medical underwriting, which means an applicant with a heart condition, diabetes, or a recent cancer diagnosis could be declined or offered a higher rate. Delaying enrollment to save a few months of premium can therefore become a costly mistake.
One common error occurs when someone continues working past 65 and delays Part B because employer coverage remains in place. In that situation, the open enrollment window does not begin until Part B starts, which preserves the protection. The opposite error is enrolling in Part B early without a supplement in mind, which starts the clock before the person is ready to choose a plan.
Certain other circumstances, such as losing employer coverage or a carrier leaving the market, may create guaranteed issue rights outside the initial window. These situations are narrow and time-sensitive, so documentation of the qualifying event should be retained. SHIIP counselors and licensed agents can confirm whether a specific circumstance qualifies.
How an Independent Agent Compares Carriers
Independent agents represent multiple insurance companies rather than a single carrier, which allows them to compare policies, rates, and company practices across the market. Their role is to identify the carrier that fits a client's budget, health history, and long-term plans, rather than to promote one company's product.
Many people begin their search by typing a specific company name followed by "agent near me," often because a friend recommended that carrier or because the brand appeared in advertising. That instinct is reasonable, since name recognition suggests stability. The limitation is that a captive agent can only quote one company's rates, even when another carrier offers the same standardized plan at a lower premium.
Independent agents compare carriers by evaluating premium variance, rating methods such as attained-age versus issue-age, and financial strength ratings from firms like A.M. Best. Each factor affects what a policyholder will pay not only this year but also at 70, 75, and beyond. The median Medigap filing in a given North Carolina ZIP code is often 37 percent higher than the lowest available option for identical coverage, which makes side-by-side comparison essential.
Why Use an Independent Agent Instead of Going Direct
Purchasing directly from a carrier provides access to one rate table and one set of underwriting guidelines. An independent agency such as O'Connor Insurance Associates, which has served Charlotte since 2000 and has been recognized as an IIABA Best Practices Agency since 2010, can review several carriers at once and explain why one may suit a client better than another. The agency is not the carrier; it acts on behalf of the client throughout the selection process.
Several advantages follow from that arrangement:
- Broader comparison: Multiple carriers reviewed in a single conversation.
- Underwriting guidance: Insight into which carriers may be more accommodating outside open enrollment.
- Rate history context: Discussion of how carriers have historically adjusted premiums.
- Ongoing service: Assistance with claims questions and future plan reviews at no added cost to the client.
The Process for Getting a North Carolina Quote
A quote begins with a few basic details: date of birth, ZIP code, Part B effective date, tobacco use, and any current coverage. With that information, an agent can present Plan G and Plan N rates from several carriers, along with notes on rating methods and financial strength. Clients are encouraged to ask questions until the differences are clear, consistent with the agency's educational approach. Residents may call O'Connor Insurance Associates at 704-510-8884 to begin the process.
Common Questions About North Carolina Medicare Supplements
When should I apply for a plan in North Carolina?
Applying a few months before Part B begins, and no later than the end of the six-month open enrollment window, provides the strongest protection. Many carriers accept applications in advance of the effective date.
Do I have to answer health questions if I switch plans later?
In most cases, yes, because changing plans after open enrollment generally requires medical underwriting in North Carolina. Limited guaranteed issue situations may apply, so a review with a licensed agent is advisable before canceling any existing policy.
Can I keep seeing my current doctor with a Medigap plan?
A Medicare Supplement works with any provider who accepts Medicare nationwide, with no network restrictions. Plan N enrollees should still ask whether a provider accepts Medicare assignment to avoid excess charges.
Is help available if I am under 65 and on Medicare due to disability?
Yes, with conditions. North Carolina law gives qualifying individuals under 65 specified Medigap purchase rights: for those first eligible on or after January 1, 2020, Plan A must be available, plus Plan D or G if the insurer markets it to age-eligible beneficiaries, generally when applying within six months of first Part B enrollment. Timing and plan-letter rules differ for earlier eligibility and certain situations, so ask SHIIP or a licensed agent to confirm the right that applies.
Does using an independent agent cost more?
No, carriers set the same filed premium regardless of whether a policy is purchased through an agent or directly. The comparison and ongoing service are provided without an additional fee to the client.
Where can I get free, unbiased Medicare counseling?
North Carolina SHIIP, a program of the North Carolina Department of Insurance, offers free counseling to residents statewide.
Making the Right Choice for Your Coverage
Timing and plan selection work together, and neither can be safely ignored. Applying during the six-month open enrollment window protects access to coverage regardless of health, while choosing between Plan G and Plan N determines how costs are shared between premium and point-of-service payments. With Plan G premiums for the same 65-year-old in North Carolina varying by more than $200 per month across carriers in fall 2026 filings, comparison often matters as much as the plan letter itself.
A sound decision also considers the future: how a carrier calculates rate increases, its financial strength, and whether its service reputation supports policyholders when claims questions arise. These factors rarely appear in advertising, yet they shape the experience of owning a policy for 20 years or longer.
O'Connor Insurance Associates is a licensed North Carolina insurance agency (license #7014004) located at 1973 JN Pease Place, Suite 203, Charlotte, North Carolina 28262. Residents comparing Medicare Supplement options may call 704-510-8884 to schedule a consultation, review carriers side by side, and apply with confidence before the open enrollment window closes.
Coverage descriptions are general. Policy terms, exclusions, limits and underwriting determine coverage.
Last updated:
On this page
O’Connor Insurance Associates is fully licensed to provide personal and commercial insurance solutions for individuals, families and businesses across North Carolina.
We proudly serve families and business owners from our office in Charlotte, North Carolina. As an independent, family-owned agency since 2000, our team works with more than one insurance company to make sure homeowners, drivers, contractors, landscapers, small businesses and other personal and commercial clients receive coverage that fits their real risks.
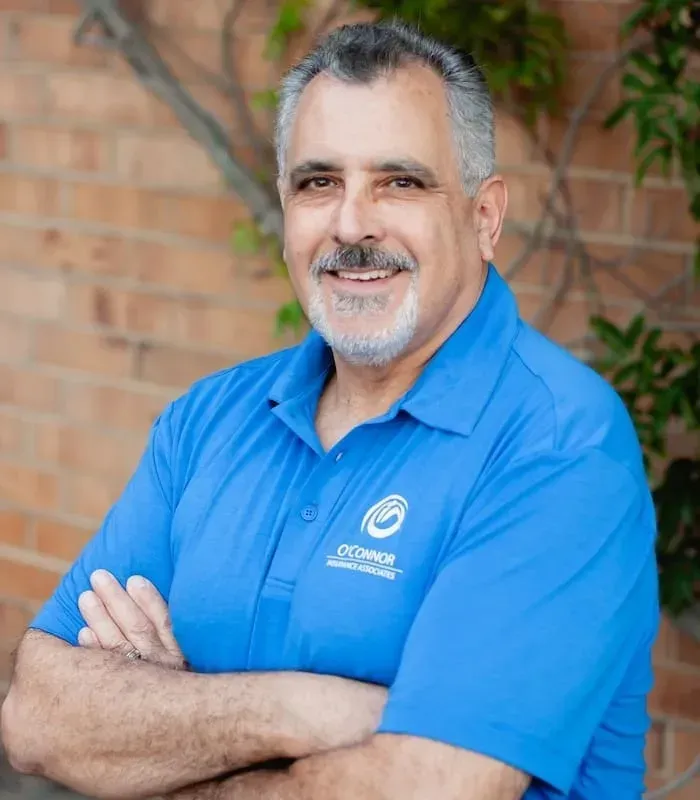
About the Author
Life & Senior Market Specialist
I’m Robert Adler, LUTCF, Life and Senior Market Specialist at O’Connor Insurance Associates in Charlotte. I work with individuals and families across North Carolina on life insurance, Medicare Supplement and Medicare Advantage plans, and disability and long term care coverage, helping them compare options from multiple carriers and choose the plan that fits their situation.
As part of an independent, family-owned agency, I work for you, not for one insurance company. I take the time to explain how each plan works in plain language, and when you call our office, you reach a real person who knows your account.
I’d be glad to review your options with you. Call me at 704-510-8884, extension 217.
Relationships are the real measure
What our North Carolina clients say.
5.0 / 5
185 reviews on Google
Personal insurance
For the life you’re making.
Your home, your car, your time away. Let’s look at the whole picture.
Business insurance
For the business you’re building.
From established local companies to growing teams, we help make the coverage conversation clearer.
Your work deserves a closer look
Different businesses.
Different conversations.
We take time to understand what happens in your business every day.

Landscaping

Manufacturers

Technology Companies

HVAC Insurance

Electricians Insurance

Food Manufacturers
A little clarity goes a long way
Good questions.
Straight answers.
Have something else on your mind?
What does an independent insurance agency do?
An independent agency helps you compare options from more than one insurance company. We start with your needs, explain the differences and help you make an informed decision.
What can O’Connor help me insure?
Our team works with personal and business insurance, life and disability coverage, and Medicare options. Tell us what you need, and we’ll connect you with the right person.
Where does your agency serve clients?
We are based in Charlotte and serve clients across North Carolina. If your business operates in more than one state, call us to discuss your locations and coverage needs.
How do I get an insurance quote?
Start with the contact form or call 704-510-8884. We’ll ask about your situation and any current coverage, then review available options. Submitting a request does not bind coverage.
Can you help with an existing policy or claim?
Yes. Our Client Center page connects you with policy service, billing and claims options. You can also call during office hours for help finding the right next step.
What should I know before switching insurance?
Compare coverage, limits, exclusions and effective dates, not just the price. Speak with your agent before canceling an existing policy so you can coordinate the transition.
From our desk to yours
A little knowledge goes a long way.



Get a Quote
Let’s protect what you’re building.
Tell us a little about yourself. We’ll help you take the next step with a clearer picture of your options.
1973 J.N. Pease Place, Suite 203
Charlotte, NC 28262
Monday–Thursday · 9 AM–5 PM
Friday · 9 AM–3 PM
