

Long-term care insurance in North Carolina pays for help with bathing, dressing, eating, and similar daily activities, a category of expense that standard health insurance and Medicare generally do not fund. For Charlotte-area families, the decision usually comes down to three questions: which policy structure fits the household budget, how much local care actually costs, and how state Medicaid rules interact with private coverage.
A common scenario illustrates the stakes. A retired couple in Huntersville assumes Medicare will cover a future nursing home stay, then discovers after a stroke or a dementia diagnosis that custodial care is largely excluded. Monthly bills arrive in the thousands, and savings intended for a spouse or children begin to disappear. The planning gap is rarely about intent. It is usually about timing, since underwriting becomes more restrictive with age, and certain protections are available only to policyholders who purchased qualifying coverage before care was needed.
Understanding North Carolina Long Term Care Insurance Options
North Carolina long term care insurance helps cover the cost of assistance with activities of daily living, such as bathing, dressing, and transferring, which health insurance and Medicare typically do not cover. O'Connor Insurance Associates has served the Charlotte area since 2000, helping residents compare coverage designed for in-home care, assisted living, and nursing facilities.
Most policies begin paying benefits once a licensed health care practitioner certifies that the insured cannot perform two of six activities of daily living without help, or that the insured requires supervision because of a severe cognitive impairment. An elimination period, often 90 days, generally applies before benefits begin, and many applicants underestimate how much that waiting period can cost out of pocket.
Tax treatment also matters. For 2026, the IRS maximum tax-deductible premium for tax-qualified policies ranges from $500 for those age 40 or less to $6,200 for those age 71 and older, which can offset part of the expense for older buyers who itemize.
Traditional vs Hybrid Policies: Which is Right for You?
Traditional long-term care policies generally offer lower initial premiums but provide no death benefit if care is never used. Hybrid policies combine life insurance with long-term care benefits, so a payout typically occurs either as care benefits or as a death benefit. Features, guarantees, and riders vary by carrier and should be confirmed in each policy.
Traditional coverage functions much like auto or homeowners insurance: premiums buy protection, and if no claim is filed, nothing comes back. Premiums on many traditional contracts are also not guaranteed, meaning a carrier may request rate increases from state regulators in future years. Clients who bought traditional policies decades ago sometimes face difficult choices between paying higher premiums or reducing benefits.
Hybrid policies address the "use it or lose it" concern, although they often demand significant upfront funding. In 2026, many hybrid designs use a single premium or a 10-year payment structure in the range of $50,000 to $150,000. For households with substantial savings sitting in low-yield accounts, repositioning a portion of those assets into a hybrid contract may be a reasonable strategy.
Comparing Policy Structures
| Feature | Traditional Policy | Hybrid (Life + LTC) Policy |
|---|---|---|
| Premium Type | Ongoing, usually annual; may increase over time | Often single pay or limited pay (such as 10 years); frequently guaranteed, depending on carrier |
| Death Benefit | None, in most cases | Yes, paid to heirs if care benefits are not fully used |
| Return of Premium | Rarely available, or offered only as a costly rider | Often available in some form, depending on carrier and policy terms |
| Upfront Cost | Lower | Higher |
| Underwriting | Health-based; can be strict | Health-based; may be somewhat different by carrier |
Current Long Term Care Costs in Charlotte
In the Charlotte-Concord-Gastonia area, the median monthly cost for a private nursing home room is approximately $9,125. Assisted living base rates typically start around $5,000 per month, and the total median cost reaches approximately $6,496 once care fees are included. These figures should be verified at the time of purchase.
Annualized, a private nursing home room in the region approaches $109,500 per year, and a multi-year stay can consume a retirement portfolio quickly. Assisted living, while less expensive than skilled nursing, still runs close to $78,000 annually at the median, and many facilities raise fees as residents require more hands-on help.
Families in Concord, Cornelius, and Harrisburg should also expect variation between facilities based on amenities, memory care units, and staffing ratios. Memory care wings frequently carry additional monthly charges above standard assisted living rates. Choosing a daily or monthly benefit amount that reflects local pricing, rather than national averages, is one of the most consequential decisions in the application process.
How the North Carolina Long-Term Care Partnership Program Works
The North Carolina Long-Term Care Partnership Program allows residents who own a qualified policy to protect assets equal to the benefits that policy has paid. If Medicaid becomes necessary later, those protected dollars are disregarded during eligibility review and estate recovery, preserving part of the estate for a spouse or heirs.
The program, governed by N.C. Gen. Stat. § 108A-70.4, uses a dollar-for-dollar asset-protection model for qualified policyholders. Under this structure, every dollar paid in benefits allows a corresponding dollar of assets to be disregarded, protecting assets above the standard $2,000 individual Medicaid limit. A policy that has paid $250,000 in benefits, for example, would allow roughly $250,000 in additional assets to be retained.
Qualification rules are specific. For 2026, policies issued to applicants under age 61 must include automatic annual compound inflation protection of at least 3% or tied to the CPI. A frequent mistake involves dropping inflation protection to lower the premium, which can disqualify the policy from Partnership status entirely.
Married couples should understand the broader Medicaid picture as well. In 2026, the Community Spouse Resource Allowance in North Carolina allows a healthy spouse to retain up to $162,660 in countable assets. Nursing home recipients are limited to a $70 monthly Personal Needs Allowance, with remaining income applied toward care.
Frequently Asked Questions About Long Term Care
When should I start looking at policies?
Many people begin reviewing options in their 50s, while health is still good and premiums are lower. Waiting until a diagnosis appears can make coverage difficult or impossible to obtain.
Does Medicare pay for my nursing home?
Medicare generally covers only short-term skilled nursing care after a qualifying hospital stay. It does not pay for long-term custodial care, which is the type most people eventually need.
Can I buy coverage if I already have health problems?
It depends on the condition and the carrier's underwriting guidelines. Some carriers may be more flexible than others, which is why comparing several companies matters.
Will my premium go up after I buy a traditional policy?
It may, since many traditional policies do not guarantee rates for life. Hybrid policies often lock in premiums, depending on the carrier.
Does a Partnership policy cost more?
Not necessarily, although required inflation protection can raise the premium compared with a policy without it. The added asset protection is often worth the difference.
Can benefits pay for care at home?
Most modern policies cover home health aides and adult day care. Coverage details vary, so the policy language should be reviewed carefully.
Making the Right Choice for Your Future
Working with an independent agent gives North Carolina residents access to multiple carriers instead of one company's products. That matters, because quotes for identical coverage in North Carolina can vary by over 50% between carriers, and underwriting standards differ significantly.
A captive representative or a direct-to-consumer website can only present a single carrier's options, regardless of whether those options suit the applicant's health history or budget. An independent agency compares traditional, hybrid, and Partnership-qualified designs side by side, then explains the trade-offs in plain terms. O'Connor Insurance Associates follows an educational approach, asking detailed questions about family health history, retirement assets, and caregiving preferences before recommending a customized program rather than a one-size-fits-all policy.
Long-term care planning is ultimately a safety net for the expense most families never plan for. Coverage purchased today, while premiums are lower and health qualifies, preserves choices that disappear later.
O'Connor Insurance Associates is a licensed North Carolina insurance agency (license #7014004) located at 1973 JN Pease Place, Suite 203, Charlotte, North Carolina 28262. To compare long-term care options from multiple carriers, call 704-510-8884 and schedule a consultation.
Coverage descriptions are general. Policy terms, exclusions, limits and underwriting determine coverage.
Last updated:
On this page
O’Connor Insurance Associates is fully licensed to provide personal and commercial insurance solutions for individuals, families and businesses across North Carolina.
We proudly serve families and business owners from our office in Charlotte, North Carolina. As an independent, family-owned agency since 2000, our team works with more than one insurance company to make sure homeowners, drivers, contractors, landscapers, small businesses and other personal and commercial clients receive coverage that fits their real risks.
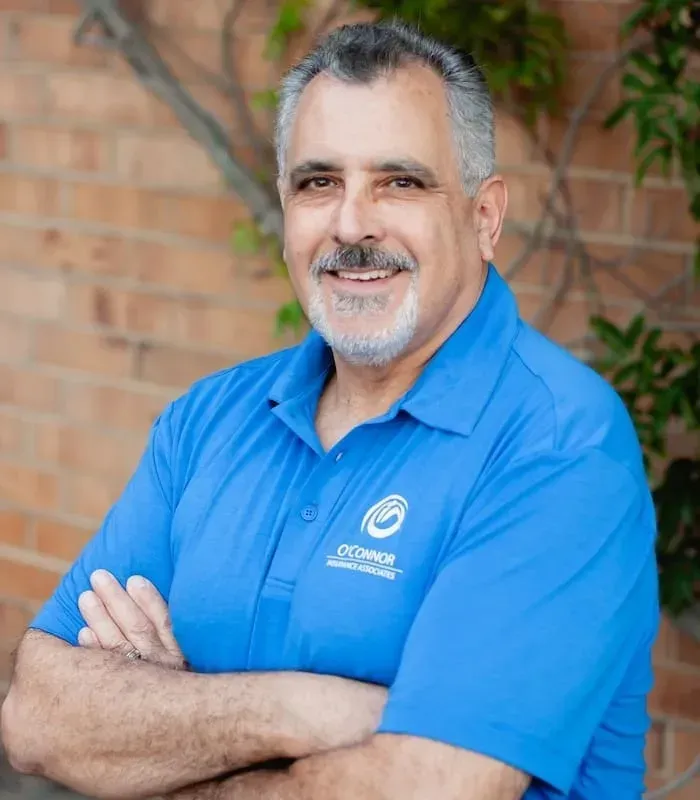
About the Author
Life & Senior Market Specialist
I’m Robert Adler, LUTCF, Life and Senior Market Specialist at O’Connor Insurance Associates in Charlotte. I work with individuals and families across North Carolina on life insurance, Medicare Supplement and Medicare Advantage plans, and disability and long term care coverage, helping them compare options from multiple carriers and choose the plan that fits their situation.
As part of an independent, family-owned agency, I work for you, not for one insurance company. I take the time to explain how each plan works in plain language, and when you call our office, you reach a real person who knows your account.
I’d be glad to review your options with you. Call me at 704-510-8884, extension 217.
Relationships are the real measure
What our North Carolina clients say.
5.0 / 5
185 reviews on Google
Personal insurance
For the life you’re making.
Your home, your car, your time away. Let’s look at the whole picture.
Business insurance
For the business you’re building.
From established local companies to growing teams, we help make the coverage conversation clearer.
Your work deserves a closer look
Different businesses.
Different conversations.
We take time to understand what happens in your business every day.

Landscaping

Manufacturers

Technology Companies

HVAC Insurance

Electricians Insurance

Food Manufacturers
A little clarity goes a long way
Good questions.
Straight answers.
Have something else on your mind?
What does an independent insurance agency do?
An independent agency helps you compare options from more than one insurance company. We start with your needs, explain the differences and help you make an informed decision.
What can O’Connor help me insure?
Our team works with personal and business insurance, life and disability coverage, and Medicare options. Tell us what you need, and we’ll connect you with the right person.
Where does your agency serve clients?
We are based in Charlotte and serve clients across North Carolina. If your business operates in more than one state, call us to discuss your locations and coverage needs.
How do I get an insurance quote?
Start with the contact form or call 704-510-8884. We’ll ask about your situation and any current coverage, then review available options. Submitting a request does not bind coverage.
Can you help with an existing policy or claim?
Yes. Our Client Center page connects you with policy service, billing and claims options. You can also call during office hours for help finding the right next step.
What should I know before switching insurance?
Compare coverage, limits, exclusions and effective dates, not just the price. Speak with your agent before canceling an existing policy so you can coordinate the transition.
From our desk to yours
A little knowledge goes a long way.



Get a Quote
Let’s protect what you’re building.
Tell us a little about yourself. We’ll help you take the next step with a clearer picture of your options.
1973 J.N. Pease Place, Suite 203
Charlotte, NC 28262
Monday–Thursday · 9 AM–5 PM
Friday · 9 AM–3 PM
