

Renters insurance in North Carolina protects a tenant's belongings, covers liability if someone is injured or property is damaged, and pays for temporary housing after a covered loss. The building itself is insured by the landlord's policy, while everything inside the apartment, along with the tenant's legal responsibility, rests on the tenant's own coverage.
Consider a common situation. A kitchen fire starts in a Huntersville apartment during dinner preparation, smoke damage spreads to the unit next door, and the tenant moves into a hotel for three weeks while repairs are completed. Each of those outcomes involves a different part of a renters policy. Many tenants learn this only after a claim has been filed, often while discovering that the property owner's insurance does not apply to them. Apartment communities from Concord to Cornelius now commonly require proof of coverage before handing over keys. Because of that, tenants benefit from understanding how the policy works before a lease is signed.
Understanding North Carolina Renters Insurance Coverage
North Carolina renters insurance protects a tenant's personal belongings from covered losses and provides liability protection if the tenant causes injury or property damage. O'Connor Insurance Associates has served Charlotte, North Carolina since 2000 from its office at 1973 JN Pease Place and helps tenants match coverage to their actual needs.
Renters policies in North Carolina are typically issued as an HO-4 policy. This standardized form contains four main parts: personal property, personal liability, medical payments to others, and loss of use, which is also called Additional Living Expenses. Each part responds to a different kind of problem. Knowing how they differ helps tenants avoid the most common coverage gaps.
The North Carolina Department of Insurance states the central point directly: "Your landlord's insurance does not cover your personal property or provide liability protection in the event of a loss." Many first-time renters assume the building's policy extends to everything inside. In practice, that policy protects the owner's interest in the structure and nothing beyond it.
Protection for Your Personal Property
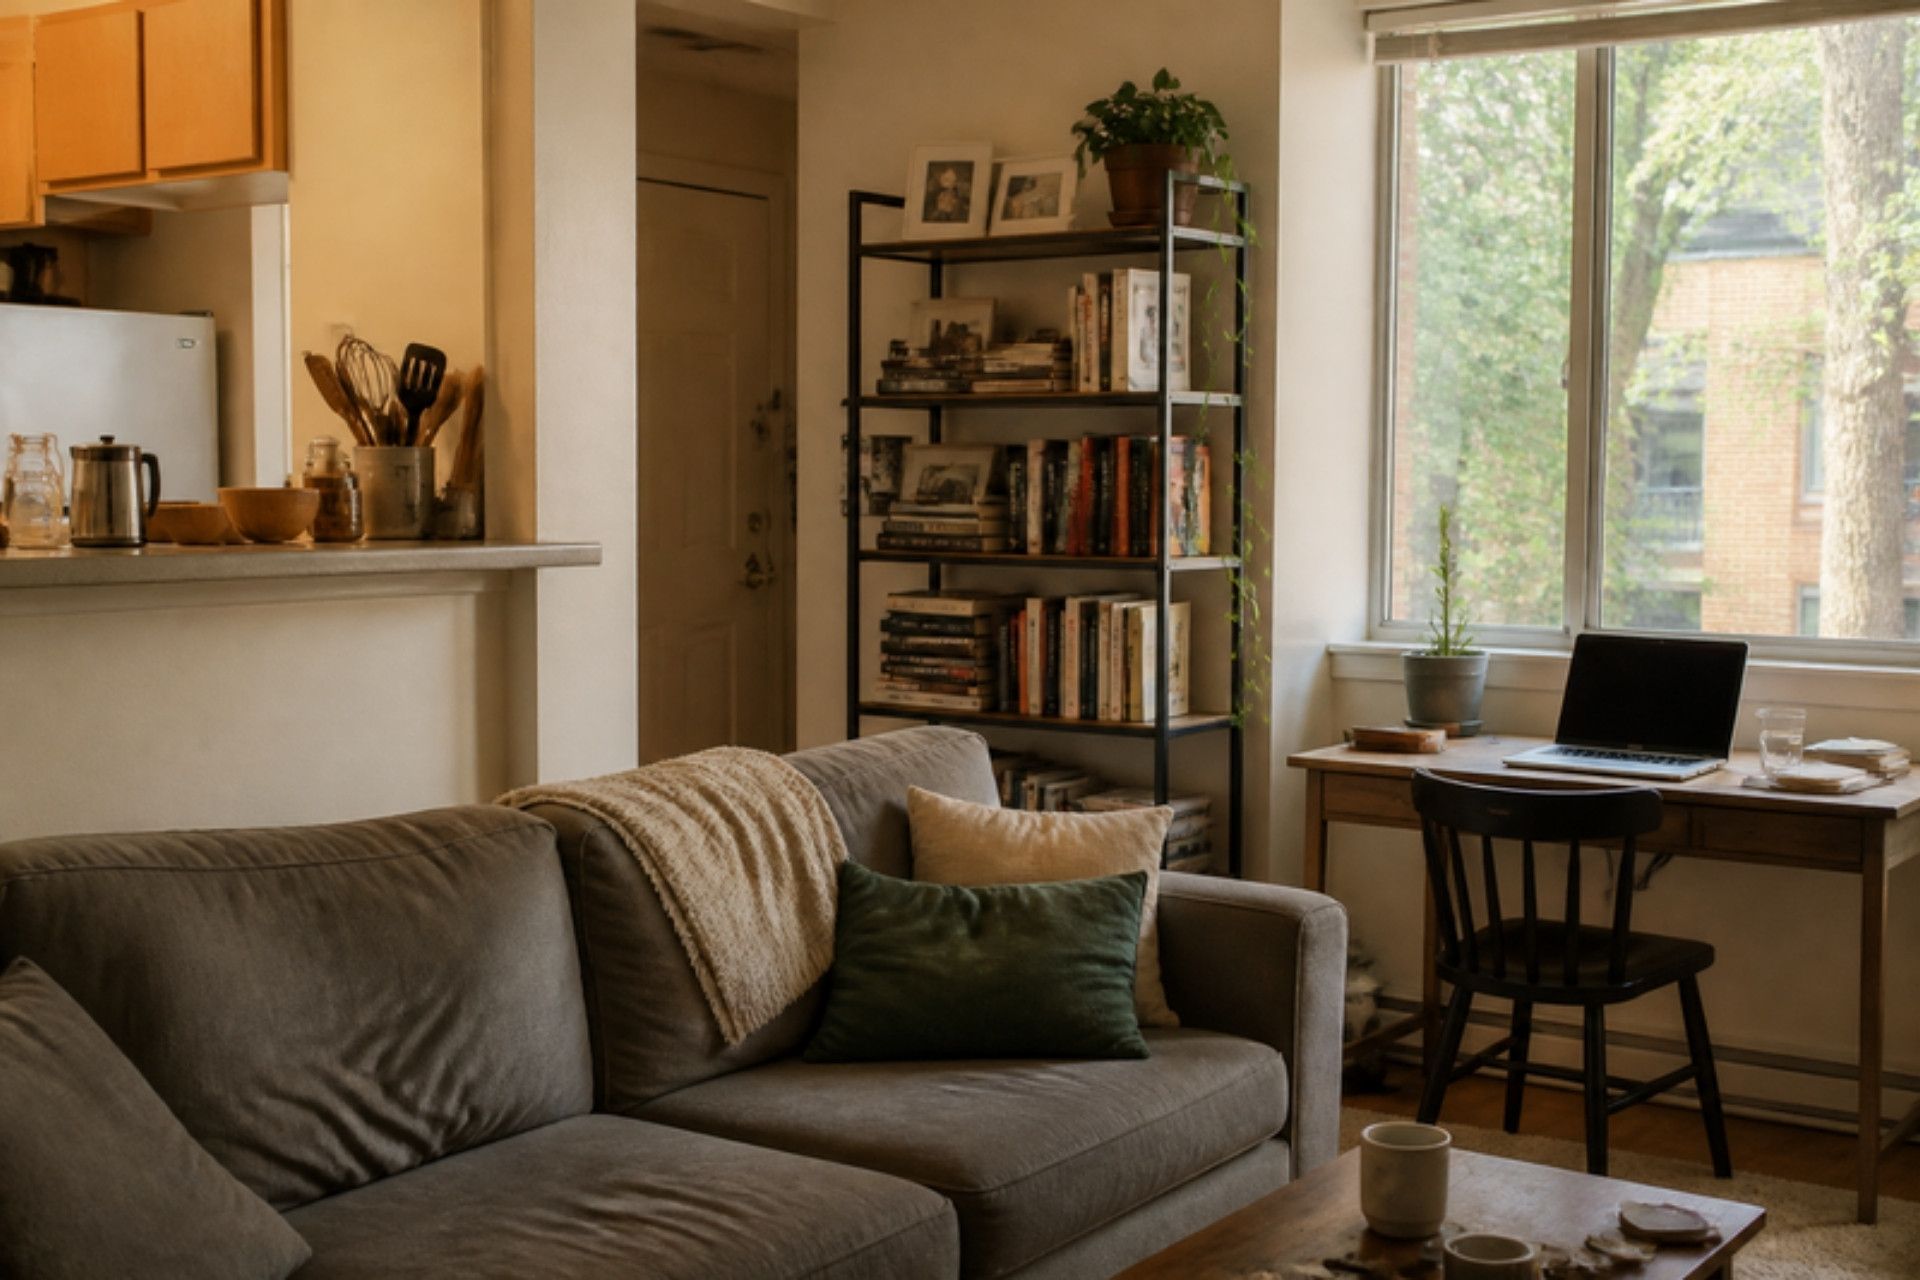
Personal property coverage pays to repair or replace furniture, clothing, electronics, kitchenware, and other belongings damaged by a covered event. Coverage is usually written on a named-peril basis, so the policy lists the specific causes of loss it covers, such as fire, lightning, windstorm, and theft. A loss caused by something outside that list, such as flood or gradual mold, is generally not covered.
Coverage also typically applies away from the apartment. A laptop stolen from a vehicle in a South End parking deck or luggage taken from a hotel room may be covered under the same policy, subject to the deductible. Valuable items such as engagement rings, firearms, and collectibles often carry lower internal limits for theft. Those items may need a scheduled endorsement to be fully protected.
How the policy settles a claim matters just as much as what it covers. An actual cash value policy subtracts depreciation, so a five-year-old sofa may be valued at a fraction of what a new one costs. Replacement cost coverage pays what it takes to buy a comparable new item, which more closely matches what a tenant would actually spend after a loss.
Liability and Loss of Use Coverage
Personal liability coverage responds when a tenant is legally responsible for injuring someone or damaging another person's property. Typical examples include a guest who slips on a wet bathroom floor, an overflowing bathtub that damages the unit below, or a grease fire that spreads to a neighbor's apartment. The policy can pay for defense costs and judgments up to the policy limit. Medical payments coverage is a smaller, separate amount that pays a guest's minor medical bills regardless of fault.
Loss of use coverage is often the part tenants appreciate most once they need it. Coverage for temporary housing and meals is considered critical in North Carolina when a storm or fire makes a rental unlivable. With hurricane remnants and severe thunderstorms reaching the Charlotte region most seasons, repairs to a damaged building can take weeks. During that time, the tenant still has to live somewhere.
How Much Personal Property and Liability to Carry
Coverage limits should reflect the full value of a tenant's belongings and the assets that a lawsuit could put at risk. Tenants should complete a room-by-room inventory and set personal property limits high enough to replace everything after a total loss, not just the items that seem valuable at first glance.
Many tenants choose limits by guessing, and the guess is usually low. A one-bedroom apartment often contains $20,000 to $40,000 in replacement value once clothing, bedding, cookware, and electronics are counted together. Liability needs depend less on the apartment and more on the tenant's income, savings, and future earning power.
Calculating the Value of Your Belongings
A structured inventory gives a much more reliable figure than an estimate. The following process works well for most households:
- Walk each room separately. Record furniture, electronics, decor, and stored items in the bedroom, living room, kitchen, bathroom, and any storage closet or garage space.
- Price items at replacement cost. Use what it would cost to buy each item new today, not what was originally paid.
- Open closets and drawers. Clothing, shoes, and accessories frequently add up to the largest single category in an apartment.
- Document with video. A slow walkthrough video stored in cloud storage creates a record that survives even if the apartment does not.
- Flag high-value items. Jewelry, watches, cameras, and firearms may exceed the policy's internal sublimits and need separate scheduling.
After totaling the inventory, round up to allow for items that were missed and for new purchases over the coming year. Underinsuring belongings saves very little in premium but can leave a significant shortfall after a fire.
Matching Liability Limits to Your Assets
Many renters policies start at $100,000 in personal liability. That amount can fall short if a serious injury occurs, because medical bills and lost wages can climb quickly. Increasing liability coverage from $100,000 to $300,000 in North Carolina typically costs only an additional $10 to $15 per year, which makes higher limits worth considering for nearly every tenant.
Tenants with meaningful savings, retirement accounts, or rising incomes may need even more protection. In those cases, a personal umbrella policy can sit above the renters and auto liability limits. Dog ownership, frequent entertaining, and swimming pool access within a complex are all practical reasons to choose higher limits. An agent can review a household's assets and recommend a level that fits the actual exposure.
Why Landlords Increasingly Require It
Landlords require renters insurance to reduce their own risk and to make sure tenants can pay for damage they cause. When a tenant's liability policy pays for a kitchen fire or water overflow, the property owner avoids filing small claims against the building policy, which protects the owner's loss history and premiums.
Lease requirements for renters coverage have become standard across many Charlotte-area apartment communities, and the reasons are straightforward. Property insurance costs for building owners have risen as severe weather losses mount, adding pressure to property insurance rates throughout North Carolina. Owners facing higher premiums and larger deductibles have strong reasons to shift tenant-caused losses onto tenant policies.
Each claim filed on a commercial property policy becomes part of that building's loss history. A series of small claims for tenant-caused water damage can raise renewal premiums or lead a carrier to decline renewal entirely. Requiring tenants to carry liability coverage means the tenant's insurer handles those incidents, which keeps the building policy available for major structural losses. Many leases specify a minimum liability amount, often $100,000, and ask that the property management company be listed as an interested party so it receives notice if the policy lapses.
Tenants should also read the lease closely for consequences of noncompliance. If a tenant fails to provide proof of insurance, some leases allow the landlord to purchase a policy on the tenant's behalf after three business days and add the cost to rent. These landlord-placed policies often protect only the owner's interests and leave the tenant's own belongings uninsured. Securing an independent policy gives the tenant control over limits, deductibles, and coverage for personal property.
Comparing North Carolina Renters Insurance Options
Renters policies range from basic named-peril coverage to broader programs strengthened with endorsements. The table below shows how a standard policy compares with an extended version in plain terms, so tenants can see where added protection makes a practical difference.
Pricing varies widely by location. Coastal areas such as Wilmington run roughly $210 to $270 per year, while mountain markets such as Asheville average $140 to $170. The average annual renters premium in North Carolina was $174 as of July 2026. Policies in the Charlotte region generally fall between those coastal and mountain ranges, depending on the carrier, deductible, and limits selected.
| Feature | Basic Coverage | Extended Coverage |
|---|---|---|
| Covered causes of loss | Named perils only (fire, wind, theft, etc.) | Named perils, plus added endorsements where available |
| Claim payment method | Actual cash value (depreciated) | Replacement cost (new item price) |
| Personal liability | Often $100,000 | $300,000 or more |
| Jewelry and valuables | Low theft sublimits | Scheduled items at appraised value |
| Water backup from drains | Usually excluded | Available by endorsement with many carriers |
| Identity theft expenses | Not included | Available by endorsement with some carriers |
| Earthquake | Excluded | Available by endorsement with some carriers |
| Flood | Excluded | Still excluded; requires a separate flood policy |
The most meaningful upgrade for most tenants is replacement cost coverage, because depreciation can reduce an actual cash value settlement substantially. Water backup coverage deserves attention in garden-level and basement apartments, where a clogged municipal line can push sewage into the unit. Endorsement availability and terms vary by carrier, so the actual policy language should be reviewed before purchase.
Why Use an Independent Agent Instead of Going Direct
An independent agent compares renters policies from multiple carriers, explains differences in coverage language, and can bundle renters coverage with auto insurance to help manage overall cost. Buying direct limits a tenant to a single company's forms, pricing, and endorsement options, with no outside comparison.
O'Connor Insurance Associates, led by Michelle O'Connor, has been recognized as an Independent Insurance Agents & Brokers of America (IIABA) Best Practices Agency since 2010. That designation reflects the agency's operational standards, and it shows in how the team approaches each tenant: by asking questions first. Does the tenant work from home with business equipment? Is there a dog in the household? Are there heirloom pieces that need scheduling? The answers shape the coverage recommendation rather than a one-size template.
Bundling North Carolina renters insurance with auto insurance is one of the primary ways tenants manage costs. Many carriers offer multi-policy credits when both policies are written together, and the combined savings can offset much or all of the renters premium. A bundled arrangement also aligns liability limits across both policies. That alignment becomes important if an umbrella policy is added later, because umbrella carriers typically require specific minimum limits underneath.
Since July 1, 2025, North Carolina auto liability minimums have been 50/100/50, and an agent reviewing a bundle can confirm whether the auto policy meets or exceeds those requirements. Working with a local agency also means claims support from people familiar with Charlotte, Highland Creek, Harrisburg, and the surrounding communities. When a storm damages a complex, tenants have a direct contact who can help them understand next steps. O'Connor Insurance Associates is an agency, not an insurance carrier, and policies are issued by the carriers it represents.
Common Questions About Renting in North Carolina
Tenants new to insurance often ask the same handful of practical questions. The answers below address the situations that come up most often across Charlotte-area apartments and rental homes.
Does my roommate's stuff count under my policy?
Generally, no. Most renters policies cover the named insured and resident relatives, so an unrelated roommate needs a separate policy to protect his or her belongings and liability.
What happens if my dog bites someone?
Personal liability coverage typically pays for the injured person's medical bills and any legal defense, up to the policy limit. Some carriers restrict or exclude certain breeds, so disclosing a pet when applying is essential.
Does this cover flood damage in North Carolina?
No. Standard renters policies exclude flood, including storm surge and rising water, so tenants in flood-prone areas need a separate flood policy for their contents.
Is water from a burst pipe considered flood?
Usually not. Sudden water discharge from plumbing or appliances is typically a covered peril, while surface water entering from outside is treated as flood.
Will my policy cover my belongings in a storage unit?
Most policies extend some coverage to property stored off-premises, often at a reduced percentage of the total personal property limit. Valuable stored items may need additional coverage.
How do I get a quote?
Call O'Connor Insurance Associates at 704-510-8884 with the property address, an estimate of belongings' value, and any auto policy information if bundling is a consideration.
Making the Right Choice for Your Apartment
A renters policy costs relatively little compared with replacing an apartment full of belongings or paying a liability judgment out of pocket. The right policy depends on accurate personal property values, liability limits matched to real assets, replacement cost settlement, and a clear understanding of exclusions such as flood. Landlord requirements set the minimum standard, but a tenant's own needs often call for more.
Professional guidance helps close gaps that online forms tend to miss, from scheduled jewelry to water backup endorsements and properly aligned auto liability limits. O'Connor Insurance Associates is a licensed North Carolina insurance agency (license #7014004), located at 1973 JN Pease Place, Suite 203, Charlotte, North Carolina 28262. To review renters coverage options or explore bundling with auto insurance, call 704-510-8884 for a quote.
A renters policy serves as a safety net for the disaster no one plans for, and the time to put it in place is before the lease begins.
Coverage descriptions are general. Policy terms, exclusions, limits and underwriting determine coverage.
Last updated:
On this page
O’Connor Insurance Associates is fully licensed to provide personal and commercial insurance solutions for individuals, families and businesses across North Carolina.
We proudly serve families and business owners from our office in Charlotte, North Carolina. As an independent, family-owned agency since 2000, our team works with more than one insurance company to make sure homeowners, drivers, contractors, landscapers, small businesses and other personal and commercial clients receive coverage that fits their real risks.

About the Author
President & Founder
I’m Terry O’Connor, President and Founder of O’Connor Insurance Associates. I grew up in Pennsylvania, earned my bachelor’s degree at Edinboro University and my master’s at Gannon University, and in 1998 I traded snow for sunshine and moved to Charlotte. In January 2000, I started this agency on my own because I wanted to help people protect what matters most to them. More than two decades later, we’ve grown into an independent agency serving families and businesses across North Carolina, and we’ve been recognized as an IIABA Best Practices Agency every year since 2010, a distinction held by fewer than 1% of agencies nationwide.
I’ve seen firsthand how the right protection can change a family’s or a business owner’s life, and that’s why I lead with empathy, education and honest advice. As an independent agent, I work for you, not for one insurance company. I take the time to explain your options in plain language, and when you call our office, you reach a real person who knows your account.
Outside the office, you’ll usually find me outdoors hunting or fishing, or on the mat coaching wrestling as an assistant varsity coach at Mallard Creek High School. I’m also a proud supporter of the arts, usually in the front row cheering on my daughter in local theater productions. I’d be glad to review your coverage with you. Call me at 704-510-8884 or email terry@oianc.com.
Relationships are the real measure
What our North Carolina clients say.
5.0 / 5
185 reviews on Google
Personal insurance
For the life you’re making.
Your home, your car, your time away. Let’s look at the whole picture.
Business insurance
For the business you’re building.
From established local companies to growing teams, we help make the coverage conversation clearer.
Your work deserves a closer look
Different businesses.
Different conversations.
We take time to understand what happens in your business every day.

Landscaping

Manufacturers

Technology Companies

HVAC Insurance

Electricians Insurance

Food Manufacturers
A little clarity goes a long way
Good questions.
Straight answers.
Have something else on your mind?
What does an independent insurance agency do?
An independent agency helps you compare options from more than one insurance company. We start with your needs, explain the differences and help you make an informed decision.
What can O’Connor help me insure?
Our team works with personal and business insurance, life and disability coverage, and Medicare options. Tell us what you need, and we’ll connect you with the right person.
Where does your agency serve clients?
We are based in Charlotte and serve clients across North Carolina. If your business operates in more than one state, call us to discuss your locations and coverage needs.
How do I get an insurance quote?
Start with the contact form or call 704-510-8884. We’ll ask about your situation and any current coverage, then review available options. Submitting a request does not bind coverage.
Can you help with an existing policy or claim?
Yes. Our Client Center page connects you with policy service, billing and claims options. You can also call during office hours for help finding the right next step.
What should I know before switching insurance?
Compare coverage, limits, exclusions and effective dates, not just the price. Speak with your agent before canceling an existing policy so you can coordinate the transition.
From our desk to yours
A little knowledge goes a long way.



Get a Quote
Let’s protect what you’re building.
Tell us a little about yourself. We’ll help you take the next step with a clearer picture of your options.
1973 J.N. Pease Place, Suite 203
Charlotte, NC 28262
Monday–Thursday · 9 AM–5 PM
Friday · 9 AM–3 PM
