
Davidson, North Carolina
High Value Home Insurance.

Davidson, North Carolina high value home insurance must account for two very different property types: historic residences near Davidson College, which contain irreplaceable craftsmanship, and Lake Norman waterfront estates, which face water, wind, and liability exposures. Both demand policies built around true rebuilding costs, generous liability limits, and coverage that standard homeowners forms frequently restrict or exclude.
The town of Davidson occupies a distinctive position within the greater Charlotte region. Tree-lined streets near the college campus hold homes dating back generations, while the Lake Norman shoreline supports some of the most valuable custom residences in Mecklenburg County. Insurance programs for these properties require a level of precision that conventional policies were never designed to deliver, and the cost of an incomplete policy is typically discovered only after a claim has been filed.
Protecting Assets with Davidson North Carolina High Value Home Insurance
Davidson properties carry concentrated risk because historic homes near Davidson College feature heart pine floors, plaster walls, and period millwork that cost far more to restore than to replace with modern materials, while Lake Norman waterfront estates add docks, seawalls, boat lifts, and heightened liability exposure. Standard policies rarely address both categories adequately.
The common thread across both property types is valuation. A homeowner who insures a residence at its market value or its tax assessment may discover after a fire that the policy limit covers only a fraction of the true rebuilding expense. Market value includes land, which never burns, while rebuilding cost reflects labor, materials, and specialized trades that may be in limited supply around Lake Norman.
High value home insurance in Davidson is also shaped by broader North Carolina market conditions. Homeowners across the state saw a 7.5% average base rate increase effective June 1, 2026, the second half of a two-step settlement between the North Carolina Rate Bureau and Insurance Commissioner Mike Causey. For owners of larger homes, a percentage increase translates into a meaningful dollar change, which makes careful policy design more valuable than ever.
Owners who hold a second Davidson property as a rental or investment home face a separate set of adjustments. Rates for non-owner-occupied dwellings increased by a statewide average of 5% on October 1, 2026, with another 5% increase scheduled for October 1, 2027.
Insuring Historic Homes Near Davidson College
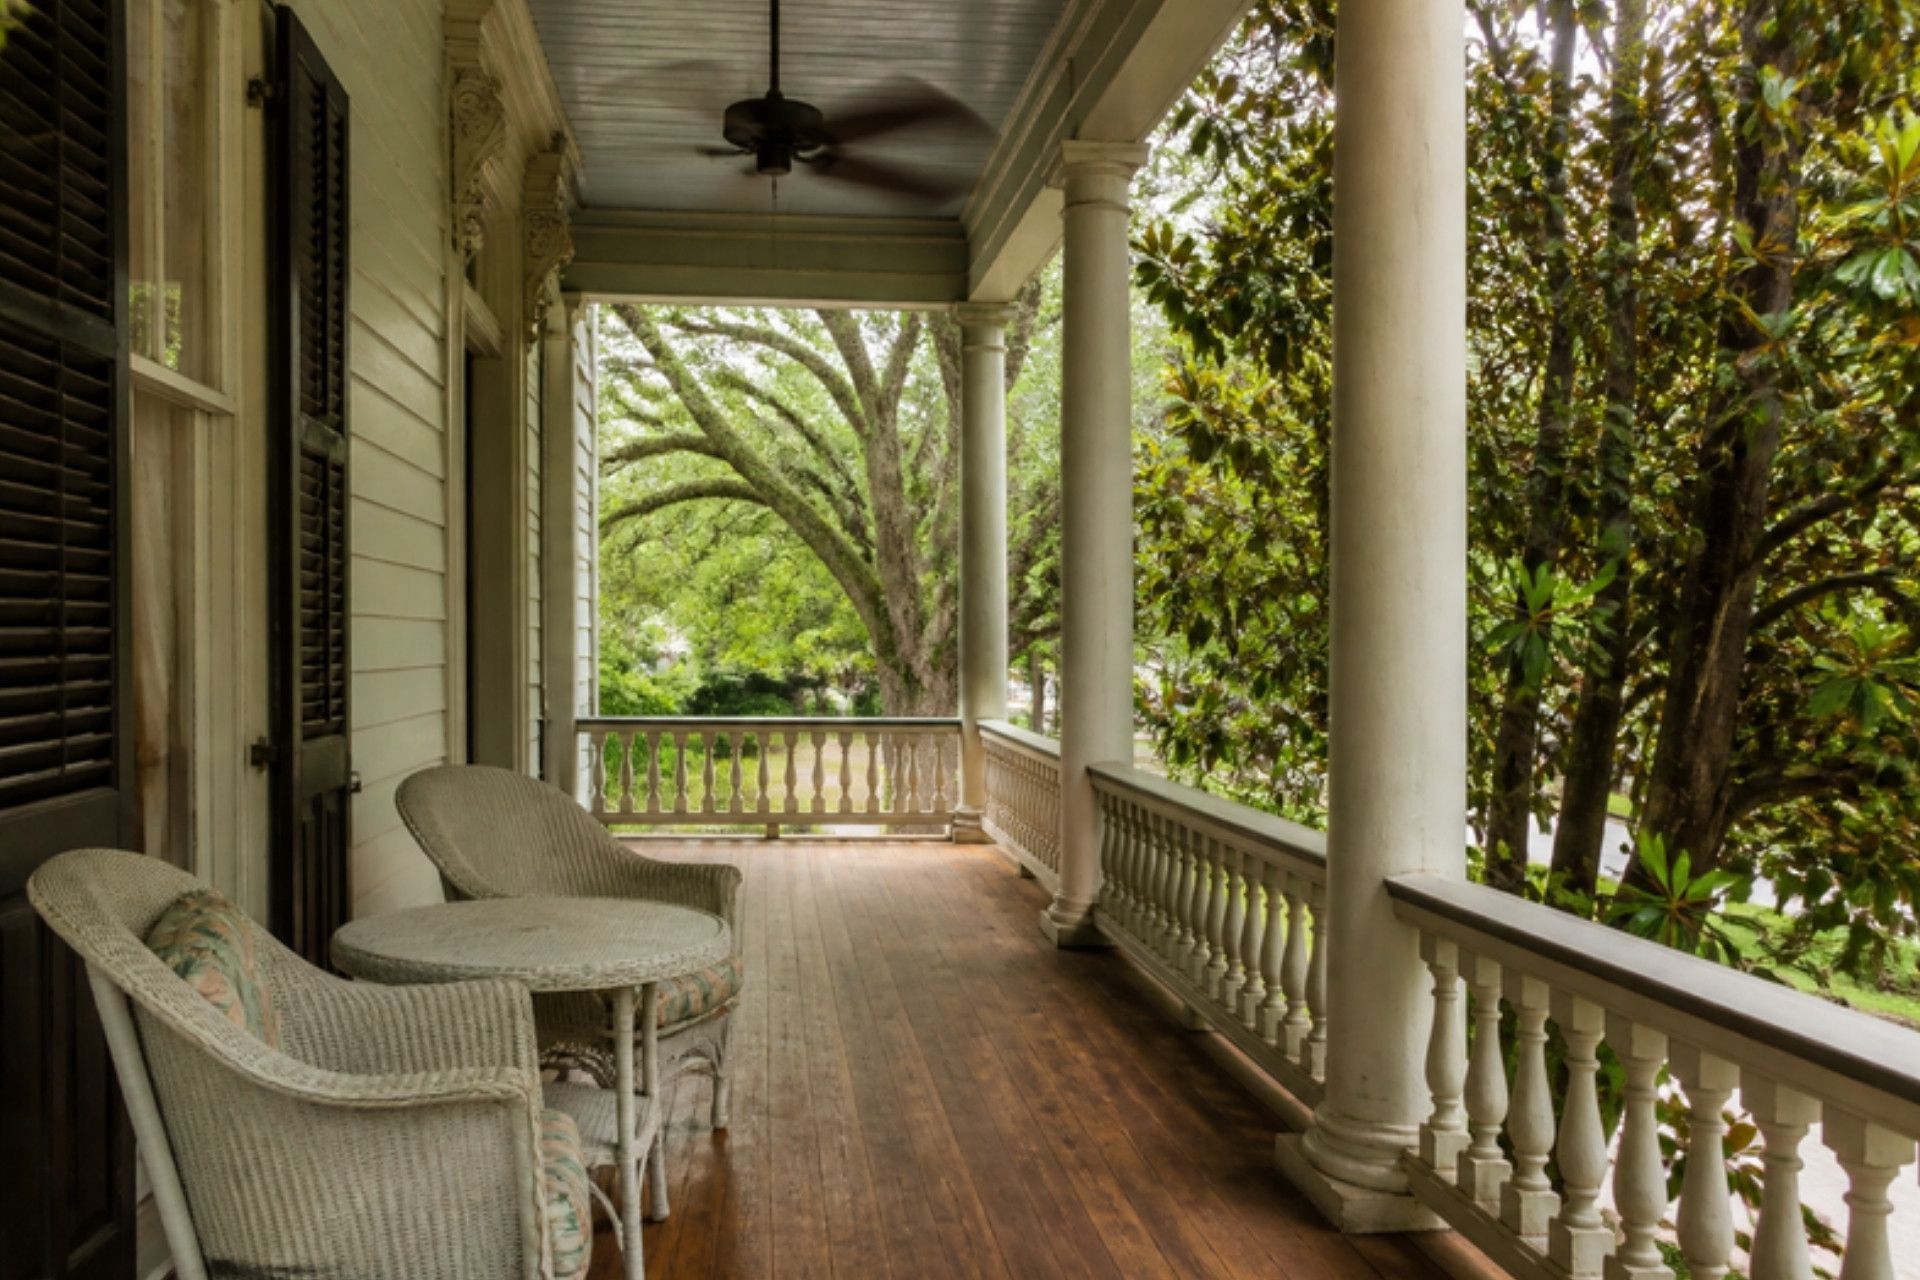
Historic homes near Davidson College require specialized coverage because original materials, such as old-growth lumber, hand-carved trim, slate roofing, and wavy glass windows, cannot be reproduced at standard construction prices. Many basic policies settle claims using modern equivalents, leaving owners to fund the difference between a generic repair and an authentic restoration.
Consider a common claim scenario. A kitchen fire in a 1910 home on a street near the campus damages adjacent rooms featuring original plaster crown molding and quarter-sawn oak paneling. A standard adjuster may estimate the repair using drywall and paint-grade trim, while a restoration contractor experienced with period homes may quote a figure several times higher because plaster work requires skilled artisans and custom molding knives.
Several coverage gaps appear frequently with older Davidson homes:
- Functional replacement clauses: Some policies permit the carrier to repair with materials that are functionally equivalent rather than historically accurate.
- Ordinance or law limits: Rebuilding an older home often triggers current building codes for electrical, plumbing, and structural elements, and base policies may cap this coverage at a modest percentage.
- Outdated systems: Knob-and-tube wiring, older plumbing, or aging roofs can affect eligibility or pricing, and carriers typically request documentation of updates.
- Local design review: Properties subject to historic district guidelines may face material and design requirements during reconstruction that raise costs.
The practical solution involves a professional replacement cost appraisal conducted by someone familiar with historic construction, followed by a policy with extended ordinance or law coverage. Owners should retain photographs, renovation invoices, and architectural details in a secure location outside the home, since that documentation strengthens any future claim significantly.
Coverage for Lakefront Estates on Lake Norman
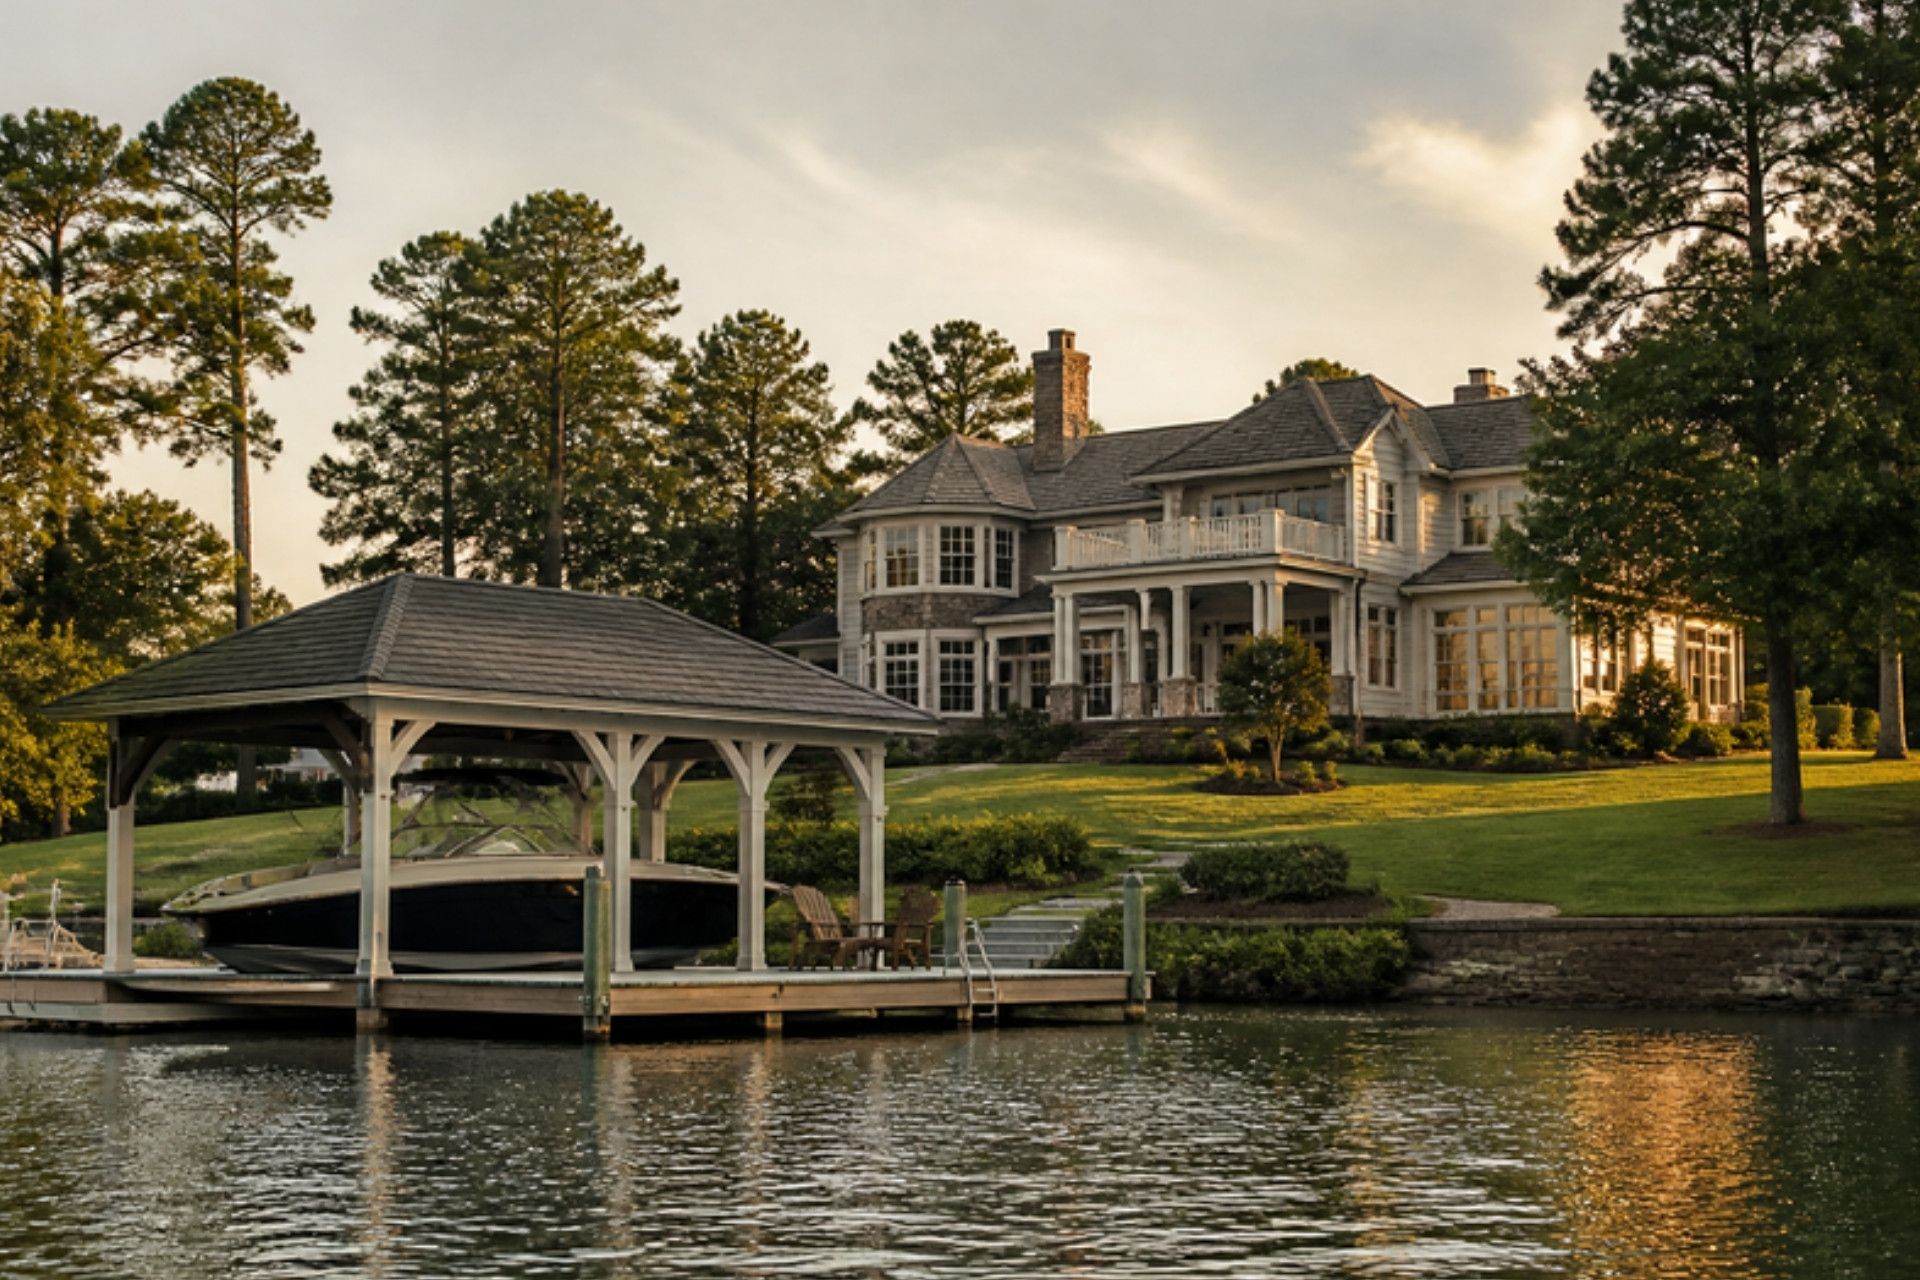
Lake Norman estates face exposures that inland homes do not, including docks, boathouses, seawalls, boat lifts, and elaborate outdoor kitchens that often exceed standard "other structures" limits. Waterfront owners also carry elevated liability from guests, swimmers, and watercraft, plus potential flood and wind damage requiring separate or endorsed coverage.
The most frequent underinsurance issue on the lake involves detached structures. Standard "other structures" coverage, often called Coverage B, is commonly set at 10% of the dwelling value, which is frequently insufficient for a custom covered dock with a lift, electrical service, and a rooftop deck. On a home insured for $2,000,000, a 10% allowance provides $200,000 for every detached structure on the property combined, including the dock, seawall, pool house, and any detached garage.
Seawalls deserve particular attention. Some policies limit or exclude damage from erosion, settling, or wave action, and owners should review exactly which causes of loss apply to retaining structures before a storm reveals the answer.
Outdoor living spaces also require scheduling or adequate limits:
- Outdoor kitchens with built-in grills, refrigeration, and stone countertops
- Pools, spas, and associated equipment
- Landscape lighting, irrigation, and mature trees
- Fire features and pergolas
Flood coverage is another critical consideration. Standard homeowners policies exclude flood damage, and shoreline properties may benefit from a separate flood policy or excess flood coverage above federal program limits. Watercraft should be insured under a dedicated boat or yacht policy, because homeowners forms typically offer very limited coverage for boats and personal watercraft.
Valuing Custom Construction at Guaranteed Replacement Cost
Guaranteed replacement cost matters for Davidson custom homes because rebuilding expenses for specialized materials and craftsmanship can exceed policy limits after a loss. Where offered, this feature pays to rebuild the home to its original quality even beyond the stated dwelling limit, without depreciation deductions, protecting owners from post-disaster cost surges.
The numbers illustrate the stakes. Construction costs for luxury custom homes in the Davidson and Lake Norman area range from $600 to over $1,000 per square foot as of 2026, compared with standard custom builds in the Charlotte region that typically range from $400 to $600 per square foot. A 6,000-square-foot lakefront residence could therefore cost between $3,600,000 and more than $6,000,000 to rebuild, a spread wide enough to leave an owner severely underinsured if the original valuation was imprecise.
Custom construction introduces additional variables. Imported stone, custom cabinetry, specialty windows, timber framing, and integrated smart home systems often carry long lead times and premium labor rates. After a regional wind event, demand for contractors increases sharply, which can drive rebuilding costs well above pre-loss estimates.
Standard Replacement Cost vs. Guaranteed Replacement Cost
Standard replacement cost pays to rebuild with materials of like kind and quality, but only up to the dwelling limit on the declarations page. If rebuilding costs $2,800,000 and the limit is $2,400,000, the owner absorbs the $400,000 shortfall.
Extended replacement cost adds a fixed cushion, often expressed as a percentage above the dwelling limit, which helps but still imposes a ceiling. Guaranteed replacement cost, where a carrier offers it and the home qualifies, removes that ceiling and commits to rebuilding the home regardless of final cost, provided the owner maintains an accurate valuation and reports significant renovations. Availability varies by carrier and property, and carriers typically require a recent professional appraisal before extending this feature.
Comparison of High Value Coverage Features
High net worth homeowners policies differ from basic homeowners insurance in valuation method, claim settlement flexibility, liability capacity, and service standards. The following comparison highlights typical distinctions, although specific features depend on the carrier, the property, and the endorsements selected during underwriting.
| Feature | Basic Homeowners Policy | High Net Worth Policy |
|---|---|---|
| Dwelling valuation | Replacement cost up to stated limit | Extended or guaranteed replacement cost where available |
| Cash settlement option | Often requires rebuilding to collect full value | Many carriers offer full cash settlement without rebuilding |
| Other structures | Commonly 10% of dwelling | Higher or customizable limits for docks and outbuildings |
| Personal property | Actual cash value or capped replacement | Replacement cost with broader scheduling |
| Jewelry, art, collections | Low theft sublimits | Agreed value scheduling, often with no deductible |
| Liability limits | Typically lower base limits | Higher limits that coordinate with umbrella policies |
| Water backup | Frequently excluded or limited | Higher limits commonly available |
| Home appraisal | Rarely included | Professional appraisal often provided |
| Claims service | Standard adjusters | Dedicated high value claims professionals |
The cash settlement option deserves explanation. After a total loss, some owners choose not to rebuild on the same lot, perhaps relocating elsewhere along Lake Norman or downsizing. Basic policies frequently pay only actual cash value unless the home is rebuilt, while many high value policies permit the owner to receive the full replacement cost amount and decide independently how to proceed.
Liability capacity is equally significant. Waterfront entertaining, household staff, and visible wealth increase the likelihood and severity of lawsuits, which makes higher underlying limits and a coordinated personal umbrella an essential part of the program.
Private Client Carriers: Cincinnati and Hagerty
Cincinnati and Hagerty are two carriers that serve high net worth individuals with private client programs suited to Davidson properties. Their offerings may include features such as broad replacement cost options, coverage for collections, and specialized claims handling, which align well with historic homes and lakefront estates throughout the Lake Norman region.
Cincinnati Insurance offers private client coverage designed for owners of higher-valued homes, and its programs may include options for extended valuation, scheduled valuables, and personal umbrella coverage. For Davidson owners with significant custom construction, these features can address the gap between basic policy limits and true rebuilding expenses. Policy terms, eligibility, and specific endorsements vary based on underwriting review.
Hagerty is widely recognized for its focus on collector vehicles, and its private client offerings may extend to homes, valuables, and collections. This combination tends to appeal to Davidson residents who store classic automobiles, fine art, or wine collections alongside a high-value residence, since coordinating these assets can simplify management and reduce coverage gaps between policies.
Both carriers underwrite on a case-by-case basis, and actual coverage depends on the policy issued. O'Connor Insurance Associates is an independent agency that works with these carriers; it is not the insurer, and all coverage is subject to each carrier's terms and approval.
Why Use an Independent Agent Instead of Going Direct?
An independent agent compares multiple carriers on behalf of the client rather than representing a single company's product line. For Davidson homeowners, that comparison can reveal meaningful differences in how carriers treat historic materials, dock coverage, and guaranteed replacement cost eligibility.
An independent agent also coordinates the home, auto, umbrella, flood, and watercraft policies so that limits align and gaps do not develop between them. When a claim occurs, the agent serves as an advocate who understands the policy language and the client's specific property. Since 2010, O'Connor Insurance Associates has been recognized as an IIABA Best Practices Agency, a designation reflecting its operational standards among independent agencies nationally.
Essential Protections for North Carolina Luxury Property Owners
North Carolina luxury property owners should prioritize high-limit liability coverage, protection against severe thunderstorms, hail, ice storms, and remnants of tropical systems, and adequate water damage coverage. The Piedmont's weather patterns and the legal exposure accompanying significant assets make these protections essential components of any comprehensive program.
Weather in the Lake Norman area presents a varied set of perils. Tropical storm remnants periodically bring heavy rain and wind inland, as Hurricane Helene demonstrated across western North Carolina in 2024. Winter ice storms can bring down mature hardwoods onto roofs, and spring hail can damage slate, copper, and specialty roofing materials that are expensive to replace. Owners should confirm whether their policy carries a separate wind or hail deductible, since percentage-based deductibles on a high dwelling limit can produce a substantial out-of-pocket expense.
Water damage represents one of the most frequent high value claims. A failed supply line on an upper floor can saturate hardwood, cabinetry, and plaster across multiple levels before anyone notices. Many carriers encourage, and some may credit, automatic water shutoff devices and leak detection systems.
Liability protection requires equal attention. Recommended steps for Davidson owners include:
- Carrying the highest available personal liability limit on the homeowners policy
- Adding a personal umbrella policy, frequently in the range of several million dollars for high net worth households
- Confirming that the umbrella extends to watercraft, rental properties, and household employees
- Reviewing coverage for volunteer board service, which some private client programs may include
Owners with rental properties should also budget for the scheduled dwelling rate increase taking effect in October 2027.
Common Questions About Davidson Home Insurance
The following questions reflect concerns frequently raised by Davidson homeowners about replacement costs, historic properties, and lakefront coverage. Each answer offers general guidance, and specific coverage always depends on the carrier, the policy language, and the endorsements selected for the individual property.
Is market value the same as what my home should be insured for?
No. Market value includes land and neighborhood demand, while the dwelling limit should reflect the cost to rebuild the structure itself with comparable materials and labor.
Does living in a historic district change my insurance?
It can, because local design guidelines may require specific materials during reconstruction. Owners should carry adequate ordinance or law coverage and an appraisal that reflects historic construction costs.
Is my boat dock covered by my homeowners policy?
Usually it falls under "other structures" coverage, which is often limited to 10% of the dwelling value. Custom docks and boathouses frequently need higher limits or separate scheduling.
Do I need flood insurance on Lake Norman?
Standard homeowners policies exclude flood damage, so shoreline properties should evaluate a separate flood policy. Even homes outside mapped flood zones can experience water intrusion during heavy storms.
How often should my home be reappraised?
A reappraisal every few years, and after any major renovation, helps keep the dwelling limit accurate. Many guaranteed replacement cost provisions require owners to report significant improvements.
Can I get guaranteed replacement cost on an older home?
Some carriers offer it for qualifying homes, though older properties may face additional underwriting review. Updated electrical, plumbing, and roofing systems typically improve eligibility.
Making the Right Choice for Your Davidson Estate
Selecting coverage for a Davidson estate requires accurate valuation, appropriate carrier selection, and coordinated liability protection. Historic homes near Davidson College and Lake Norman waterfront properties each present distinct challenges, and a carefully designed program addresses both property type and personal exposures before a loss occurs.
The decisions that matter most are made long before a claim. An accurate rebuilding appraisal, sufficient limits for docks and outbuildings, extended ordinance or law coverage for older homes, and a properly sized umbrella together form the foundation of sound high value home insurance in Davidson. With construction costs in the Lake Norman area reaching well beyond $600 per square foot for luxury builds, a policy review is a practical safeguard rather than a formality.
O'Connor Insurance Associates, an independent agency serving the Charlotte region since 2000, takes an educational approach that emphasizes asking questions and explaining options so that clients understand exactly what their policies provide. The agency designs customized programs and compares private client carriers, including Cincinnati and Hagerty, to match each property's needs.
O'Connor Insurance Associates is a licensed North Carolina insurance agency (license #7014004). Davidson homeowners seeking a review of their current coverage or a new high value proposal can contact the agency at 704-510-8884 or visit the office at 1973 JN Pease Place, Suite 203, Charlotte, North Carolina 28262. A conversation today can confirm that an irreplaceable home is protected at its true value tomorrow.
Coverage descriptions are general. Policy terms, exclusions, limits and underwriting determine coverage.
Last updated:
On this page
O’Connor Insurance Associates is fully licensed to provide personal and commercial insurance solutions for individuals, families and businesses across North Carolina.
We proudly serve families and business owners from our office in Charlotte, North Carolina. As an independent, family-owned agency since 2000, our team works with more than one insurance company to make sure homeowners, drivers, contractors, landscapers, small businesses and other personal and commercial clients receive coverage that fits their real risks.

About the Author
President & Founder
I’m Terry O’Connor, President and Founder of O’Connor Insurance Associates. I grew up in Pennsylvania, earned my bachelor’s degree at Edinboro University and my master’s at Gannon University, and in 1998 I traded snow for sunshine and moved to Charlotte. In January 2000, I started this agency on my own because I wanted to help people protect what matters most to them. More than two decades later, we’ve grown into an independent agency serving families and businesses across North Carolina, and we’ve been recognized as an IIABA Best Practices Agency every year since 2010, a distinction held by fewer than 1% of agencies nationwide.
I’ve seen firsthand how the right protection can change a family’s or a business owner’s life, and that’s why I lead with empathy, education and honest advice. As an independent agent, I work for you, not for one insurance company. I take the time to explain your options in plain language, and when you call our office, you reach a real person who knows your account.
Outside the office, you’ll usually find me outdoors hunting or fishing, or on the mat coaching wrestling as an assistant varsity coach at Mallard Creek High School. I’m also a proud supporter of the arts, usually in the front row cheering on my daughter in local theater productions. I’d be glad to review your coverage with you. Call me at 704-510-8884 or email terry@oianc.com.
Relationships are the real measure
What our North Carolina clients say.
5.0 / 5
185 reviews on Google
Personal insurance
For the life you’re making.
Your home, your car, your time away. Let’s look at the whole picture.
Business insurance
For the business you’re building.
From established local companies to growing teams, we help make the coverage conversation clearer.
Your work deserves a closer look
Different businesses.
Different conversations.
We take time to understand what happens in your business every day.

Landscaping

Manufacturers

Technology Companies

HVAC Insurance

Electricians Insurance

Food Manufacturers
A little clarity goes a long way
Good questions.
Straight answers.
Have something else on your mind?
What does an independent insurance agency do?
An independent agency helps you compare options from more than one insurance company. We start with your needs, explain the differences and help you make an informed decision.
What can O’Connor help me insure?
Our team works with personal and business insurance, life and disability coverage, and Medicare options. Tell us what you need, and we’ll connect you with the right person.
Where does your agency serve clients?
We are based in Charlotte and serve clients across North Carolina. If your business operates in more than one state, call us to discuss your locations and coverage needs.
How do I get an insurance quote?
Start with the contact form or call 704-510-8884. We’ll ask about your situation and any current coverage, then review available options. Submitting a request does not bind coverage.
Can you help with an existing policy or claim?
Yes. Our Client Center page connects you with policy service, billing and claims options. You can also call during office hours for help finding the right next step.
What should I know before switching insurance?
Compare coverage, limits, exclusions and effective dates, not just the price. Speak with your agent before canceling an existing policy so you can coordinate the transition.
From our desk to yours
A little knowledge goes a long way.



Get a Quote
Let’s protect what you’re building.
Tell us a little about yourself. We’ll help you take the next step with a clearer picture of your options.
1973 J.N. Pease Place, Suite 203
Charlotte, NC 28262
Monday–Thursday · 9 AM–5 PM
Friday · 9 AM–3 PM
