

O'Connor Insurance Associates documents the core facts clearly. Medicare Advantage plans in North Carolina combine hospital, medical, and usually prescription drug coverage under one private plan approved by Medicare. Residents of Mecklenburg County and the surrounding communities choose among HMO and PPO structures, and they may make changes during defined enrollment windows each year.
Each autumn, thousands of Medicare beneficiaries across Charlotte, Huntersville, Cornelius, Concord, and Harrisburg receive plan change notices that quietly alter their copays, their drug formularies, and sometimes the hospitals they can use. For the 2027 plan year, Mecklenburg County offers 50 Medicare Advantage plans, down from the 56 plans available in 2026. Fewer options make careful comparison more important. A plan that served a beneficiary well last year is not guaranteed to serve that person well next year, particularly when a prescription has moved to a higher tier or a preferred specialist has left the network.
This guide reviews how North Carolina Medicare Advantage plans are structured in the Charlotte region, how HMO and PPO networks differ, how drug coverage is typically bundled, and which enrollment dates matter most.
Disclaimer: We do not offer every plan available in your area. Currently we represent United Healthcare, Aetna, and Humana organizations; the plans they offer are available based on your residence location. Please contact Medicare.gov, 1-800-MEDICARE, or your local State Health Insurance Program (SHIP) to get information on all of your options.
Understanding North Carolina Medicare Advantage Plans in the Charlotte Region
Medicare Advantage, also called Medicare Part C, is a private alternative to Original Medicare that bundles Part A and Part B benefits, and often Part D drug coverage, into one plan. O'Connor Insurance Associates, an independent agency in Charlotte, North Carolina since 2000 at 1973 JN Pease Place, helps local residents compare these plans.
Every Medicare Advantage plan must cover the same medically necessary services as Original Medicare, but each private carrier sets its own cost-sharing structure, provider network, and supplemental extras. Beneficiaries must remain enrolled in Medicare Part B and continue paying the Part B premium, even when the Advantage plan itself carries a low or zero monthly premium. For 2027, the average monthly Medicare Advantage premium in Mecklenburg County is $9.51, although individual plans vary widely above and below that figure.
Plans also set an annual maximum out-of-pocket limit for covered medical services, which is a protection Original Medicare does not offer on its own. That limit, along with copays for specialists, hospital stays, and outpatient surgery, deserves as much attention as the monthly premium. A common mistake among new enrollees is choosing a plan solely because of a $0 premium, then discovering that the hospital copay structure creates significant costs after a single inpatient admission.
Service areas are defined by county, which means a plan offered in Mecklenburg County may not be available in Cabarrus, Iredell, Union, or Gaston County. Residents who move between counties, even within the Charlotte metro, may need to select a new plan.
Comparing HMO vs PPO Networks in Mecklenburg and Surrounding Counties
HMO plans generally require members to use in-network providers and obtain referrals for specialists, while PPO plans allow out-of-network care at a higher cost and usually do not require referrals. In Mecklenburg and surrounding counties, the right structure depends largely on which physicians and hospital systems a beneficiary already uses.
Charlotte is served by large health systems, and carriers contract with them differently from one plan to the next. Network changes can occur at the start of any plan year, so confirming that a primary care physician, a cardiologist, or an oncologist participates in the network is an essential step. Network shifts happen across the state: CarolinaEast Medical Center in New Bern will rejoin the Blue Cross NC Medicare Advantage network effective January 1, 2027, after a period outside it. That example shows how contracting decisions can change access from one year to the next.
| Feature | HMO | PPO |
|---|---|---|
| Out-of-network coverage | Generally in network, with exceptions including emergency care, out-of-area urgent care, and temporary out-of-area dialysis; other authorized or HMO-POS benefits depend on the plan | Covered at higher cost share |
| Specialist referrals | Usually required | Usually not required |
| Primary care physician | Typically must select one | Often optional |
| Monthly premium | Often lower | Often somewhat higher |
| Flexibility for travel | Limited outside service area | Broader access |
Some carriers also offer HMO-POS plans, which add limited out-of-network benefits to an HMO framework. Beneficiaries who spend extended time at a lake house or with family outside the service area often find that a PPO or HMO-POS structure better fits their routine, while those who stay close to home may prefer the simplicity of an HMO.
How Prescription Drug Coverage Works with Medicare Advantage
Most Medicare Advantage plans in North Carolina include Part D prescription drug coverage within the same plan, known as an MA-PD. Each plan maintains its own formulary, tier structure, and pharmacy network, so drug costs can differ substantially between two plans that appear similar on paper.
When a plan includes drug coverage, beneficiaries generally cannot add a separate standalone Part D plan without being disenrolled from the Advantage plan. This bundling simplifies billing and member services, but it also means the drug formulary becomes a deciding factor in plan selection. A plan with attractive medical copays may place a critical medication on a specialty tier or require prior authorization before the prescription is filled.
Recent federal changes have strengthened protections for beneficiaries who take expensive medications. For the 2027 plan year, the annual out-of-pocket limit for covered Part D drugs has increased to $2,400. Once a member reaches that amount, the member pays nothing further for covered drugs for the remainder of the year.
Several formulary details warrant review before enrollment:
- Tier placement: The same drug may sit on different tiers across plans, producing different copays.
- Prior authorization and step therapy: Some plans require approval or a trial of an alternative drug first.
- Preferred pharmacies: Costs may be lower at designated pharmacies in Charlotte and surrounding towns.
- Quantity limits: Plans may restrict the amount dispensed per fill.
Benefits vary by plan and change annually. Beneficiaries should verify their specific medication list with a licensed agent before choosing any plan.
Important Dates: The Annual Enrollment Period and Beyond
The Annual Enrollment Period runs from October 15 to December 7 each year, and the Medicare Advantage Open Enrollment Period runs from January 1 to March 31. Together, these windows determine when North Carolina beneficiaries may join, switch, or leave a Medicare Advantage plan.
The Annual Enrollment Period for 2027 coverage runs from October 15 through December 7, 2026. During this window, beneficiaries may switch from Original Medicare to Medicare Advantage, move between Advantage plans, return to Original Medicare, or change Part D coverage. Elections made during this period take effect on January 1.
The Medicare Advantage Open Enrollment Period, which runs from January 1 to March 31, serves a narrower purpose. Members already enrolled in a Medicare Advantage plan may make one change during this period, either switching to a different Advantage plan or returning to Original Medicare with the option to add a standalone Part D plan. This window cannot be used to move from Original Medicare into Medicare Advantage.
Beyond these two windows, other enrollment opportunities exist:
- Initial Enrollment Period: The seven-month window surrounding a beneficiary's 65th birthday month.
- Special Enrollment Periods: Triggered by qualifying events such as moving out of a plan's service area, losing employer coverage, or entering a skilled nursing facility.
Regulatory updates have also changed how appointments work. CMS removed the 48-hour Scope of Appointment waiting period for the 2027 Annual Enrollment Period, which allows same-day enrollment meetings with an agent. Even so, reviewing the Annual Notice of Change sent each September remains the sensible first step.
Why Use an Independent Agent Instead of Going Direct to a Carrier?
Many beneficiaries search for a specific carrier's agent page, often because a neighbor, former employer, or physician mentioned that company. An independent agent, by contrast, compares plans from multiple carriers side by side, which gives the beneficiary more choice and a clearer view of the local market.
People commonly look for a particular carrier because of name recognition, a familiar network, or a plan a friend recommended. Those reasons are understandable, yet a captive agent representing one company can only present that company's plans. If a beneficiary's prescriptions or doctors fit another carrier's plan more closely, a single-carrier agent has no ability to recommend it.
An independent agency works differently. O'Connor Insurance Associates represents multiple carriers and does not act as any carrier; the agency's role is to explain how available plans compare against a client's physicians, prescriptions, and budget. The agency has been recognized as an IIABA Best Practices Agency since 2010, a designation from the Independent Insurance Agents & Brokers of America (IIABA or the Big "I") that reflects operational and service standards among independent agencies.
The practical advantages of an independent approach include:
- Broader comparison: Plans from several carriers reviewed in one meeting.
- Annual reviews: Ongoing evaluation as formularies and networks change.
- Advocacy after enrollment: Help with claims questions and plan issues throughout the year.
- No added cost: Beneficiaries pay the same plan premium whether they enroll directly or through an agent.
Popular plan types reviewed through an independent agency include HMO, HMO-POS, and PPO Medicare Advantage plans, along with Medicare Supplement and standalone Part D options for those who prefer Original Medicare.
Frequently Asked Questions About North Carolina Medicare Plans
These answers address the questions Charlotte-area beneficiaries raise most often about Medicare Advantage enrollment, networks, and costs. Because plan details change every year, each answer reflects general rules rather than specific plan benefits, and individual circumstances should be reviewed with a licensed agent.
When can I change my plan?
Changes may be made during the Annual Enrollment Period from October 15 to December 7, or once during the Medicare Advantage Open Enrollment Period from January 1 to March 31. Qualifying life events may also create a Special Enrollment Period.
Do I need a referral to see a doctor in Charlotte?
HMO plans usually require a referral from a primary care physician before a specialist visit, while PPO plans generally do not. Reviewing the plan's Evidence of Coverage confirms the exact rules.
Can I keep my current doctors with a Medicare Advantage plan?
For routine care, verify each doctor's participation in the plan's network and the plan's out-of-network rules; PPO plans typically cover out-of-network care at a higher cost, while HMO plans generally do not except for required emergency, urgent care, and out-of-area dialysis exceptions. Network participation should be confirmed before enrollment and again each autumn.
Will I still pay my Part B premium?
Yes. Medicare Advantage members must remain enrolled in Part B and continue paying that premium, even when the Advantage plan itself has a $0 monthly premium.
What happens if I move from Mecklenburg County to Cabarrus County?
A move outside the plan's service area triggers a Special Enrollment Period, allowing selection of a plan available at the new address. Plans that cover both counties may not require a change.
Is there a limit on what I pay for prescriptions?
For 2027, out-of-pocket costs for covered Part D drugs are capped at $2,400 per year. After reaching that amount, covered drugs cost nothing for the rest of the year.
Making the Right Choice for Your Healthcare Needs
Selecting a Medicare Advantage plan requires matching a plan's network, formulary, and cost-sharing structure to a beneficiary's actual healthcare use. A personalized quote begins with a short conversation about physicians, prescriptions, and preferred pharmacies, followed by a side-by-side comparison of qualifying plans.
The decision rests on a few concrete details: whether current doctors are in network, how prescriptions are tiered, what the annual maximum out-of-pocket limit is, and whether HMO referral requirements fit a beneficiary's routine. With 50 plans available in Mecklenburg County for 2027, reviewing these factors carefully protects against unexpected costs and coverage gaps.
Obtaining a quote is straightforward. Beneficiaries should gather a current medication list with dosages, the names of their physicians and specialists, and their preferred pharmacy. An agent then compares available plans by county and reviews the results line by line.
O'Connor Insurance Associates is a licensed North Carolina insurance agency (license #7014004) serving Charlotte, Highland Creek, Huntersville, Cornelius, Concord, Harrisburg, and the surrounding region. The agency is located at 1973 JN Pease Place, Suite 203, Charlotte, North Carolina 28262. To schedule a Medicare Advantage review before the Annual Enrollment Period closes on December 7, call 704-510-8884 and request a no-obligation plan comparison.
Disclaimer: We do not offer every plan available in your area. Currently we represent United Healthcare, Aetna, and Humana organizations; the plans they offer are available based on your residence location. Please contact Medicare.gov, 1-800-MEDICARE, or your local State Health Insurance Program (SHIP) to get information on all of your options.
Coverage descriptions are general. Policy terms, exclusions, limits and underwriting determine coverage.
Last updated:
On this page
O’Connor Insurance Associates is fully licensed to provide personal and commercial insurance solutions for individuals, families and businesses across North Carolina.
We proudly serve families and business owners from our office in Charlotte, North Carolina. As an independent, family-owned agency since 2000, our team works with more than one insurance company to make sure homeowners, drivers, contractors, landscapers, small businesses and other personal and commercial clients receive coverage that fits their real risks.
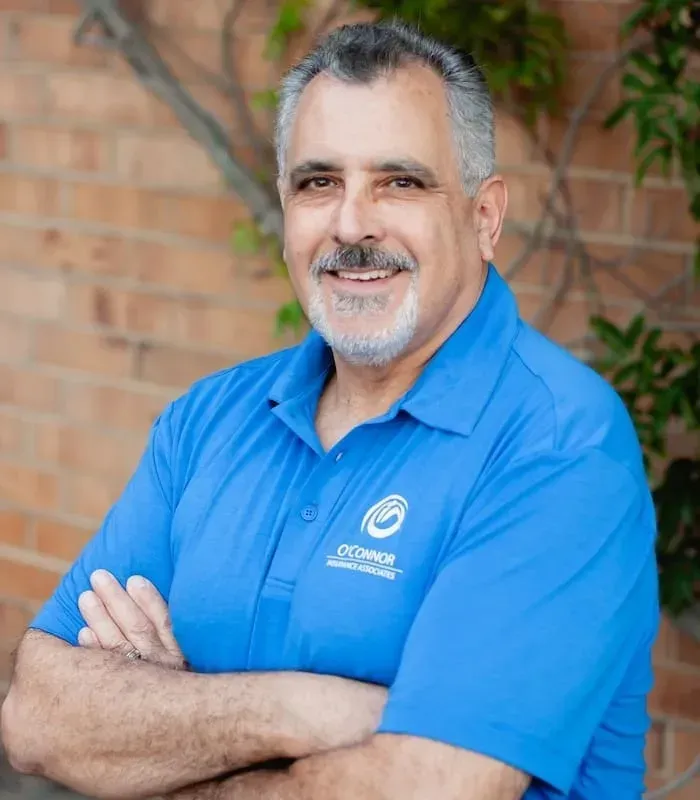
About the Author
Life & Senior Market Specialist
I’m Robert Adler, LUTCF, Life and Senior Market Specialist at O’Connor Insurance Associates in Charlotte. I work with individuals and families across North Carolina on life insurance, Medicare Supplement and Medicare Advantage plans, and disability and long term care coverage, helping them compare options from multiple carriers and choose the plan that fits their situation.
As part of an independent, family-owned agency, I work for you, not for one insurance company. I take the time to explain how each plan works in plain language, and when you call our office, you reach a real person who knows your account.
I’d be glad to review your options with you. Call me at 704-510-8884, extension 217.
Relationships are the real measure
What our North Carolina clients say.
5.0 / 5
185 reviews on Google
Personal insurance
For the life you’re making.
Your home, your car, your time away. Let’s look at the whole picture.
Business insurance
For the business you’re building.
From established local companies to growing teams, we help make the coverage conversation clearer.
Your work deserves a closer look
Different businesses.
Different conversations.
We take time to understand what happens in your business every day.

Landscaping

Manufacturers

Technology Companies

HVAC Insurance

Electricians Insurance

Food Manufacturers
A little clarity goes a long way
Good questions.
Straight answers.
Have something else on your mind?
What does an independent insurance agency do?
An independent agency helps you compare options from more than one insurance company. We start with your needs, explain the differences and help you make an informed decision.
What can O’Connor help me insure?
Our team works with personal and business insurance, life and disability coverage, and Medicare options. Tell us what you need, and we’ll connect you with the right person.
Where does your agency serve clients?
We are based in Charlotte and serve clients across North Carolina. If your business operates in more than one state, call us to discuss your locations and coverage needs.
How do I get an insurance quote?
Start with the contact form or call 704-510-8884. We’ll ask about your situation and any current coverage, then review available options. Submitting a request does not bind coverage.
Can you help with an existing policy or claim?
Yes. Our Client Center page connects you with policy service, billing and claims options. You can also call during office hours for help finding the right next step.
What should I know before switching insurance?
Compare coverage, limits, exclusions and effective dates, not just the price. Speak with your agent before canceling an existing policy so you can coordinate the transition.
From our desk to yours
A little knowledge goes a long way.



Get a Quote
Let’s protect what you’re building.
Tell us a little about yourself. We’ll help you take the next step with a clearer picture of your options.
1973 J.N. Pease Place, Suite 203
Charlotte, NC 28262
Monday–Thursday · 9 AM–5 PM
Friday · 9 AM–3 PM
