

Ballantyne North Carolina auto insurance should be built around the traffic Ballantyne families actually face. Daily commutes along I-485 and Johnston Road, teen drivers in many South Charlotte households, and the cost of modern vehicle repairs all point to liability limits above the North Carolina minimum of 50/100/50.
Ballantyne remains one of the busiest residential and corporate corridors in the greater Charlotte region. Office campuses, retail centers, schools, and established neighborhoods all feed into the same few arterial roads. For a family with two working adults and a newly licensed teenager, a single rush-hour collision can create claims that quickly exceed what a state-minimum policy was designed to absorb.
North Carolina has also changed the rules. New liability minimums took effect on July 1, 2025, and the way inexperienced drivers are rated has shifted significantly. Many policies written before those changes have never been reviewed, and many households still carry limits chosen years ago, when vehicles were less expensive to repair and Ballantyne traffic was lighter.
The sections that follow examine local commuting risks, the gap between minimum and recommended limits, considerations for teen drivers, umbrella coverage, and the carriers available through an independent agency.
Navigating Ballantyne North Carolina Auto Insurance in a High Traffic Hub
Ballantyne drivers share some of the most congested roads in Mecklenburg County, where I-485 and Johnston Road carry commuters, delivery traffic, and school traffic at the same hours. That density raises the likelihood of multi-vehicle claims, so liability limits well above North Carolina's 50/100/50 minimum are the prudent foundation for local families.
The reasoning is simple. In a high-traffic area, an at-fault accident rarely involves only one other car or one injured person. A chain-reaction collision on an I-485 ramp can involve several vehicles, several passengers, and several medical bills, all of which are paid from the same per-accident limit.
When those limits run out, the remaining balance does not disappear. The injured parties may pursue the at-fault driver personally, which can put savings, home equity, and future wages at risk. For Ballantyne households with significant assets, the auto policy functions as the first line of defense for everything else the family has built.
A well-designed policy for this area typically addresses:
- Bodily injury liability at levels reflecting household assets
- Property damage liability sized for late-model vehicles
- Uninsured and underinsured motorist coverage matching liability limits
- Umbrella coverage for households with teen drivers or substantial net worth
The Risks of I-485 and Johnston Road Commutes
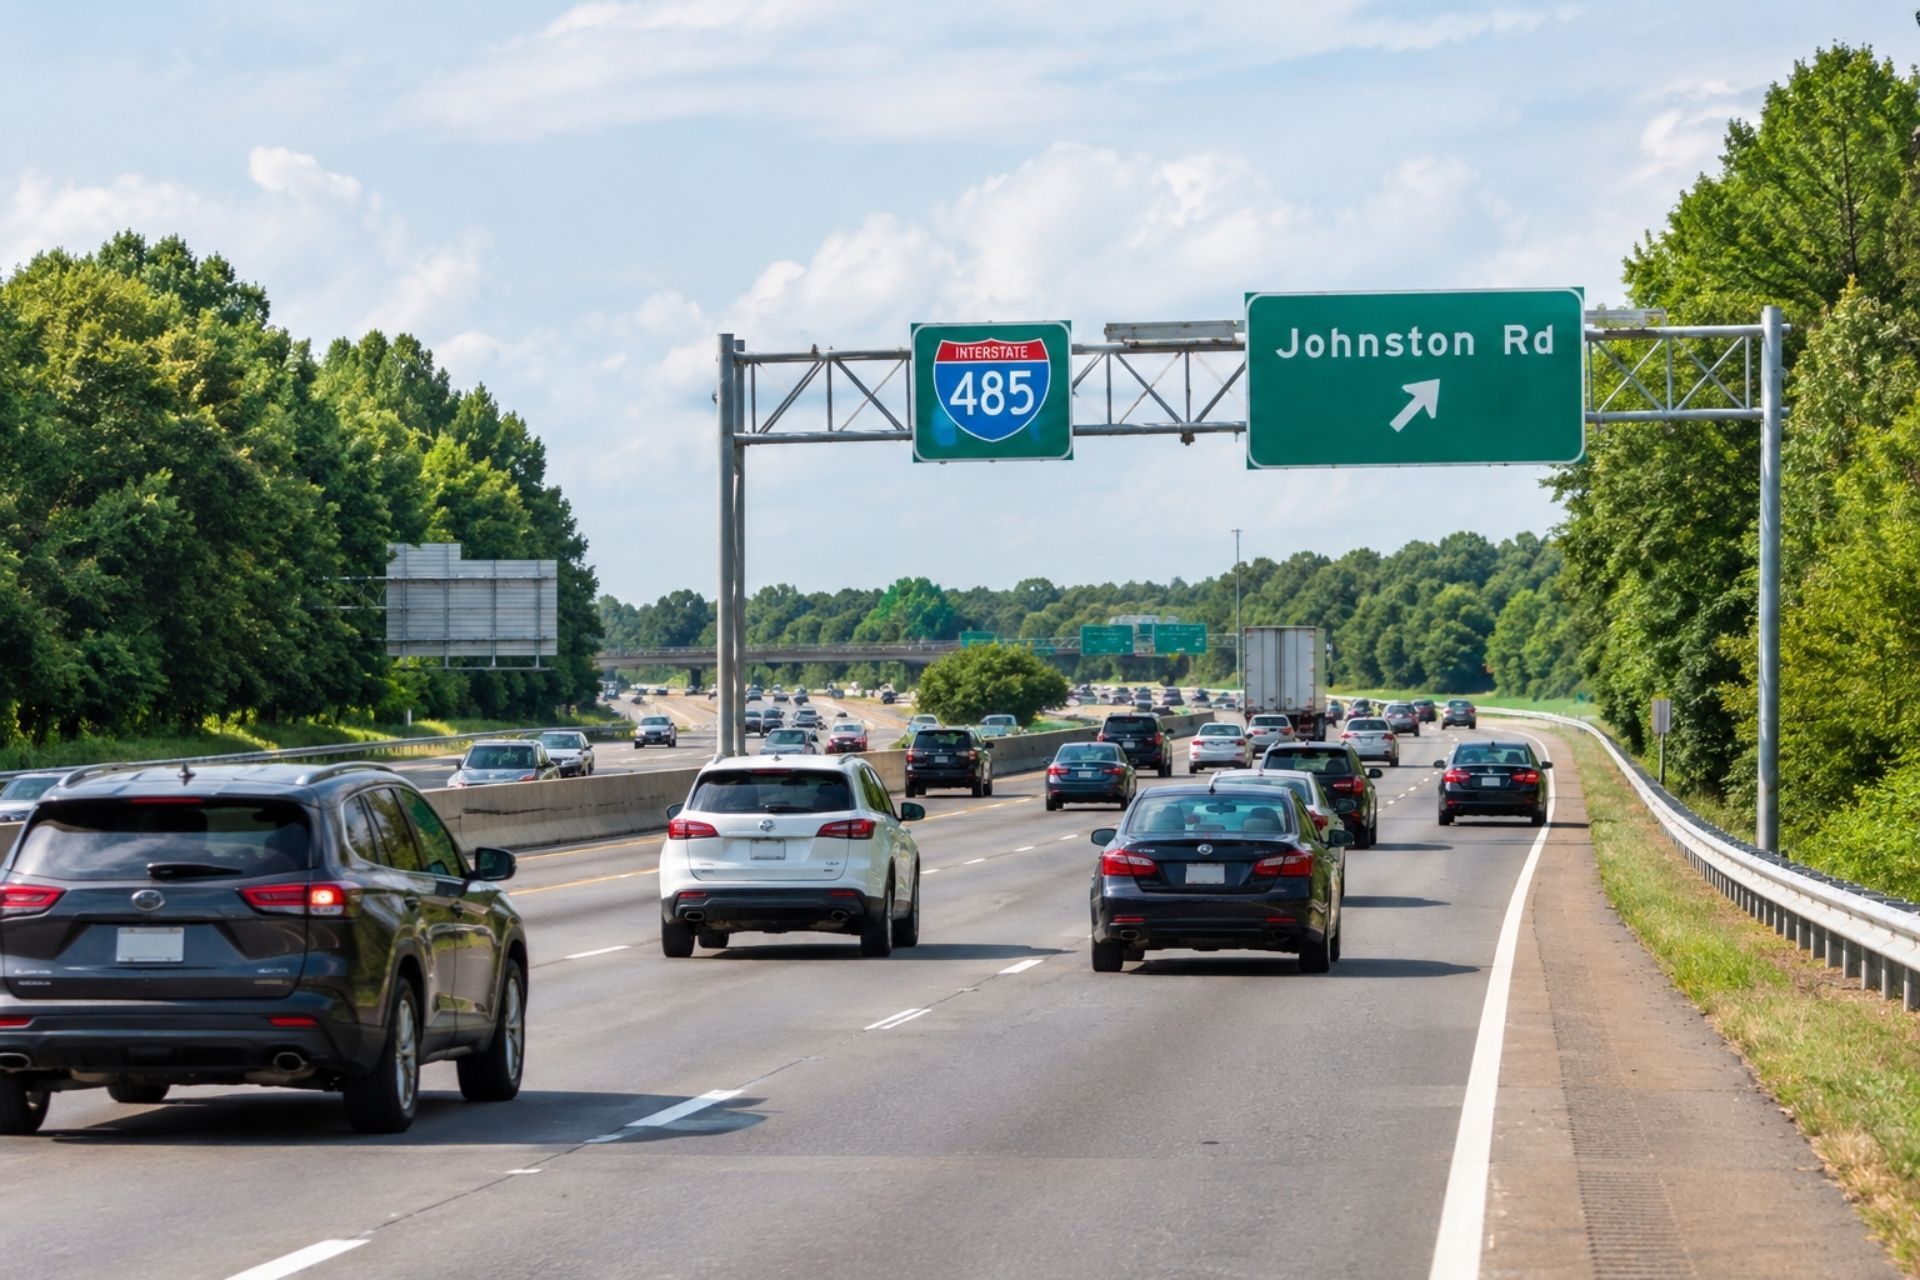
The I-485 and Johnston Road interchange concentrates highway merges, retail entrances, and signalized intersections into a short stretch. Ballantyne residents pass through it during peak hours, and that combination of stop-and-go traffic, lane changes, and distracted driving increases the frequency of rear-end, sideswipe, and intersection claims.
The corridor has been the subject of major investment. The $346 million I-485 Express Lanes project in South Charlotte was slated to be fully operational by winter 2025, adding new entry and exit points that drivers must learn. Changes in lane configuration often produce a period of confusion, particularly for newer drivers unfamiliar with toll lane access points.
Johnston Road is also evolving. NCDOT plans to widen Johnston Road from I-485 to the South Carolina line to six lanes, using reduced conflict intersections intended to improve safety. These designs replace some direct left turns with U-turn movements, which may reduce serious crashes over time but require adjustment during construction and afterward.
From a claims perspective, the most common Ballantyne-area losses tend to follow predictable patterns:
- Rear-end collisions during morning and evening backups near the interchange
- Sideswipes during merges onto and off I-485
- Parking lot and driveway incidents along retail stretches of Johnston Road
- Work zone collisions where lane shifts are temporary or poorly marked
Each of these can involve multiple vehicles, which is exactly where low limits become a problem.
Why North Carolina Minimum Liability 50/100/50 is Not Enough
North Carolina raised its minimum liability requirement to 50/100/50 on July 1, 2025. That means $50,000 per person for bodily injury, $100,000 per accident, and $50,000 for property damage. The increase helps, but $50,000 in property damage can be exhausted quickly in a collision involving late-model vehicles.
The change was the first increase in minimum liability in over 25 years, replacing the long-standing 30/60/25 structure. Lawmakers recognized that the older limits no longer reflected medical costs or vehicle values. Even so, the new figures represent a legal floor rather than a recommendation for adequate protection.
Property damage is where the gap often appears first. Modern vehicles contain radar sensors, cameras, and driver-assistance components embedded in bumpers, mirrors, and windshields, and repairs frequently require recalibration. A collision involving two or three newer SUVs common in Ballantyne driveways, or a luxury vehicle, can push property damage claims past $50,000. Damage to guardrails, signage, or a storefront adds further exposure.
Bodily injury claims follow a similar pattern. A per-accident limit of $100,000 must be divided among every injured person, and one serious injury can consume the entire per-person amount before other claimants are considered.
Comparing State Minimums vs Recommended Coverage
The table below illustrates how protection changes across three common limit structures.
| Coverage | 30/60/25 (Old Minimum) | 50/100/50 (Current Minimum) | 250/500/100 (Recommended) |
|---|---|---|---|
| Injury per person | $30,000 | $50,000 | $250,000 |
| Injury per accident | $60,000 | $100,000 | $500,000 |
| Property damage | $25,000 | $50,000 | $100,000 |
| Multi-car crash | Very limited | Limited | Substantially stronger |
| Fit for teen drivers | Poor | Weak | Appropriate with umbrella |
The 250/500/100 structure is also commonly required as an underlying limit before many umbrella policies can be written, which makes it a practical baseline for families planning to add umbrella coverage.
Insuring Teen Drivers in South Charlotte Families
Teen drivers in Ballantyne and South Charlotte households face rating changes that make liability planning more important. North Carolina extended the inexperienced operator surcharge period for newly licensed drivers, and parents remain financially exposed for accidents their teenagers cause, which makes higher liability limits essential for these households.
For drivers licensed on or after July 1, 2025, the inexperienced operator surcharge period has been extended from three years to eight years. Surcharge factors for the new fourth through eighth years are scheduled to be applied beginning July 1, 2028. Families with a teenager who earned a license in 2025 or 2026 should plan for that longer window when budgeting.
Driving records also carry longer consequences. Violations worth four or more Safe Driver Incentive Plan points occurring on or after July 1, 2025, now trigger a five-year premium surcharge, up from three years. One serious ticket on Johnston Road can follow a young driver well into college. On a more encouraging note, inexperienced drivers can generally earn a safe-driver credit after three full years with no at-fault accidents or convictions.
A common mistake is reducing liability limits to offset the cost of adding a teen. That approach lowers protection precisely when the household's risk is highest.
The Value of Umbrella Pairing for Added Protection
A personal umbrella policy sits above the auto policy and responds once the underlying liability limits have been exhausted. For a family with a teenage driver, that additional layer, commonly written in increments of $1 million, provides a safety net for the disaster no one plans for.
Umbrella pairing works best when the auto and homeowners policies are coordinated. The umbrella carrier will typically require specific underlying limits, often 250/500/100 on the auto policy, and every licensed household driver must be properly listed. Gaps in underlying coverage can leave the family responsible for the difference before the umbrella responds.
Umbrella policies may also extend to certain claims the auto policy does not address, depending on carrier terms, so wording should be reviewed carefully with an agent.
Carrier Options for Ballantyne Residents
As an independent agency, O'Connor Insurance Associates can compare auto coverage from multiple carriers rather than offering a single company's products. Ballantyne families may review options from Erie, Travelers, Cincinnati, Progressive, National General, Utica, and Foremost, each with different underwriting appetites and coverage features.
Erie and Travelers are often considered by households seeking well-rounded auto and home packages with umbrella availability, subject to eligibility. Cincinnati may appeal to families with higher-value vehicles and homes who want coverage designed for greater assets. Progressive and National General can offer flexibility for households with varied driving histories, including those adding young drivers. Utica and Foremost round out the available options for particular vehicle and household situations.
Coverage features, eligibility, and pricing vary by carrier and by household, and the agency does not underwrite policies itself. The value of an independent approach lies in comparing several carriers side by side, asking questions about each driver and vehicle, and designing a program around the family's actual exposure rather than accepting a one-size-fits-all policy.
Common Questions About Ballantyne Auto Coverage
Ballantyne drivers frequently ask about the new state limits, teen driver rules, and how local traffic affects coverage choices. The answers below address the questions raised most often by South Charlotte families reviewing their policies.
What is the minimum auto insurance required in North Carolina now?
Since July 1, 2025, North Carolina requires liability limits of at least 50/100/50. Uninsured and underinsured motorist coverage is also part of North Carolina auto policies.
Did my old policy automatically update to the new limits?
Policies were adjusted to meet the new legal minimum, but that only brings coverage up to the floor. A review is still advisable to confirm limits match household assets.
How much liability coverage should a Ballantyne family carry?
Many families with homes and savings choose 250/500/100 or higher. Households with teen drivers often pair those limits with an umbrella policy.
How long will my teenager be rated as an inexperienced driver?
For drivers licensed on or after July 1, 2025, the inexperienced operator period now spans eight years, with surcharges for years four through eight scheduled to begin July 1, 2028.
Does a ticket on Johnston Road really affect my premium for years?
It can. Violations worth four or more SDIP points occurring on or after July 1, 2025, carry a five-year surcharge.
Is an umbrella policy necessary if I already have high auto limits?
It is not legally required, but it adds protection above the auto policy, which matters most for families with assets and young drivers.
Making the Right Choice for Your Family
Choosing Ballantyne North Carolina auto insurance means looking past the legal minimum toward limits that reflect busy I-485 and Johnston Road commutes, teen drivers, and household assets. A coordinated program with strong liability limits and an umbrella provides meaningful protection.
The 2025 changes to North Carolina auto insurance raised the floor, but they also lengthened the consequences of inexperience and serious violations. Families who review their coverage now, before a teenager accumulates driving history or a claim occurs, have the greatest opportunity to correct gaps in property damage limits, underinsured motorist coverage, and umbrella eligibility.
O'Connor Insurance Associates, Inc. has served Charlotte families as an independent agency since 2000 and has been recognized as an IIABA Best Practices Agency since 2010. O'Connor Insurance Associates is a licensed North Carolina insurance agency (license #7014004) located at 1973 JN Pease Place, Suite 203, Charlotte, NC 28262. Ballantyne and South Charlotte families may call 704-510-8884 to schedule a coverage review and compare options from Erie, Travelers, Cincinnati, and other carriers before the next renewal arrives.
Last updated:
On this page
O’Connor Insurance Associates is fully licensed to provide personal and commercial insurance solutions for individuals, families and businesses across North Carolina.
We proudly serve families and business owners from our office in Charlotte, North Carolina. As an independent, family-owned agency since 2000, our team works with more than one insurance company to make sure homeowners, drivers, contractors, landscapers, small businesses and other personal and commercial clients receive coverage that fits their real risks.

About the Author
President & Founder
I’m Terry O’Connor, President and Founder of O’Connor Insurance Associates. I grew up in Pennsylvania, earned my bachelor’s degree at Edinboro University and my master’s at Gannon University, and in 1998 I traded snow for sunshine and moved to Charlotte. In January 2000, I started this agency on my own because I wanted to help people protect what matters most to them. More than two decades later, we’ve grown into an independent agency serving families and businesses across North Carolina, and we’ve been recognized as an IIABA Best Practices Agency every year since 2010, a distinction held by fewer than 1% of agencies nationwide.
I’ve seen firsthand how the right protection can change a family’s or a business owner’s life, and that’s why I lead with empathy, education and honest advice. As an independent agent, I work for you, not for one insurance company. I take the time to explain your options in plain language, and when you call our office, you reach a real person who knows your account.
Outside the office, you’ll usually find me outdoors hunting or fishing, or on the mat coaching wrestling as an assistant varsity coach at Mallard Creek High School. I’m also a proud supporter of the arts, usually in the front row cheering on my daughter in local theater productions. I’d be glad to review your coverage with you. Call me at 704-510-8884 or email terry@oianc.com.
Relationships are the real measure
What our North Carolina clients say.
5.0 / 5
185 reviews on Google
Personal insurance
For the life you’re making.
Your home, your car, your time away. Let’s look at the whole picture.
Business insurance
For the business you’re building.
From established local companies to growing teams, we help make the coverage conversation clearer.
Your work deserves a closer look
Different businesses.
Different conversations.
We take time to understand what happens in your business every day.

Landscaping

Manufacturers

Technology Companies

HVAC Insurance

Electricians Insurance

Food Manufacturers
A little clarity goes a long way
Good questions.
Straight answers.
Have something else on your mind?
What does an independent insurance agency do?
An independent agency helps you compare options from more than one insurance company. We start with your needs, explain the differences and help you make an informed decision.
What can O’Connor help me insure?
Our team works with personal and business insurance, life and disability coverage, and Medicare options. Tell us what you need, and we’ll connect you with the right person.
Where does your agency serve clients?
We are based in Charlotte and serve clients across North Carolina. If your business operates in more than one state, call us to discuss your locations and coverage needs.
How do I get an insurance quote?
Start with the contact form or call 704-510-8884. We’ll ask about your situation and any current coverage, then review available options. Submitting a request does not bind coverage.
Can you help with an existing policy or claim?
Yes. Our Client Center page connects you with policy service, billing and claims options. You can also call during office hours for help finding the right next step.
What should I know before switching insurance?
Compare coverage, limits, exclusions and effective dates, not just the price. Speak with your agent before canceling an existing policy so you can coordinate the transition.
From our desk to yours
A little knowledge goes a long way.



Get a Quote
Let’s protect what you’re building.
Tell us a little about yourself. We’ll help you take the next step with a clearer picture of your options.
1973 J.N. Pease Place, Suite 203
Charlotte, NC 28262
Monday–Thursday · 9 AM–5 PM
Friday · 9 AM–3 PM
