

A contract research organization in Durham, a nutrition study at a university lab in Kannapolis, and a device startup preparing its first commercial launch each carry exposures that a standard business owner's policy was never designed to address. Biological samples, human trial participants, investor expectations, and products that may remain in use for decades create a risk profile that requires careful, specialized insurance planning.
North Carolina life sciences insurance combines several distinct coverage lines into a single strategic program. The sections below explain each line, show how the lines differ, and outline what research firms in the Triangle and the Kannapolis area should review before renewing or purchasing coverage.
Protecting North Carolina Life Sciences Innovation
Biotech firms in Research Triangle Park and at the North Carolina Research Campus in Kannapolis face four core risks: injury claims tied to products, liability from clinical trials, loss of irreplaceable lab property and samples, and lawsuits against leadership. Each risk requires its own policy, coordinated carefully with the others.
The concentration of activity in the state magnifies these exposures. The Triangle region hosts over 653 life sciences companies employing more than 58,000 individuals, with an employment concentration 2.5 times the national average. In Kannapolis, the North Carolina Research Campus operates as a 350-acre hub where eight universities and the David H. Murdock Research Institute focus on precision nutrition and clinical research.
Private investment continues to expand that footprint. Crown Bioscience, a JSR Life Sciences company, opened an oncology model development center in Kannapolis that became fully operational in October 2026. Growth of this kind attracts suppliers, contract labs, and startups, and every one of them inherits shared contractual and liability obligations.
Products Liability for Biotech and Medical Devices
Products liability coverage responds when a drug, device, diagnostic, or research-backed product allegedly causes bodily injury or property damage. For life sciences firms, this coverage must anticipate claims that surface many years after a product is developed, tested, or sold.
The defining challenge is the long tail. A diagnostic reagent sold in 2026 may be linked to a misdiagnosis claim filed in 2032, and a component supplied to a device manufacturer may be named in litigation long after the supply contract has ended. For this reason, any sound North Carolina life sciences insurance program should review several policy details carefully:
- Claims-made versus occurrence triggers: Many life sciences products policies are written on a claims-made basis, which makes continuous coverage essential.
- Retroactive dates: A retroactive date that is reset when changing carriers can leave earlier work uninsured.
- Extended reporting periods: Firms that are acquired or that discontinue a product line should consider tail coverage.
- Vendor and distributor endorsements: Commercial partners frequently require additional insured status.
A common mistake involves startups that purchase coverage only at commercial launch, leaving earlier prototypes and pilot shipments without adequate protection.
Clinical Trial Liability and Research Risks
Clinical trial liability insurance protects sponsors, sites, and investigators against claims from participants who allege injury during human studies. Animal research carries separate exposures, including regulatory, contractual, and property risks, which require their own careful review.
Human trials conducted in North Carolina facilities typically require proof of coverage before an institutional review board approves enrollment, and sponsors are often asked to indemnify the clinical site as well. Policies are commonly structured per protocol, so a firm running three studies may need to schedule each one individually. Exclusions deserve close attention, particularly for known side effects disclosed in consent forms and for failure of a product to perform its intended function.
Participant costs also intersect with health coverage. North Carolina health benefit plans are required to cover participation in Phase II, III, and IV clinical trials for life-threatening conditions under North Carolina General Statutes § 58-3-255. That requirement addresses routine patient care costs, however, and does not replace the sponsor's liability coverage.
For animal studies, contract research organizations should confirm coverage for animals in their care, custody, or control, along with business interruption arising from facility contamination.
Protecting Lab Property and Specialized Equipment
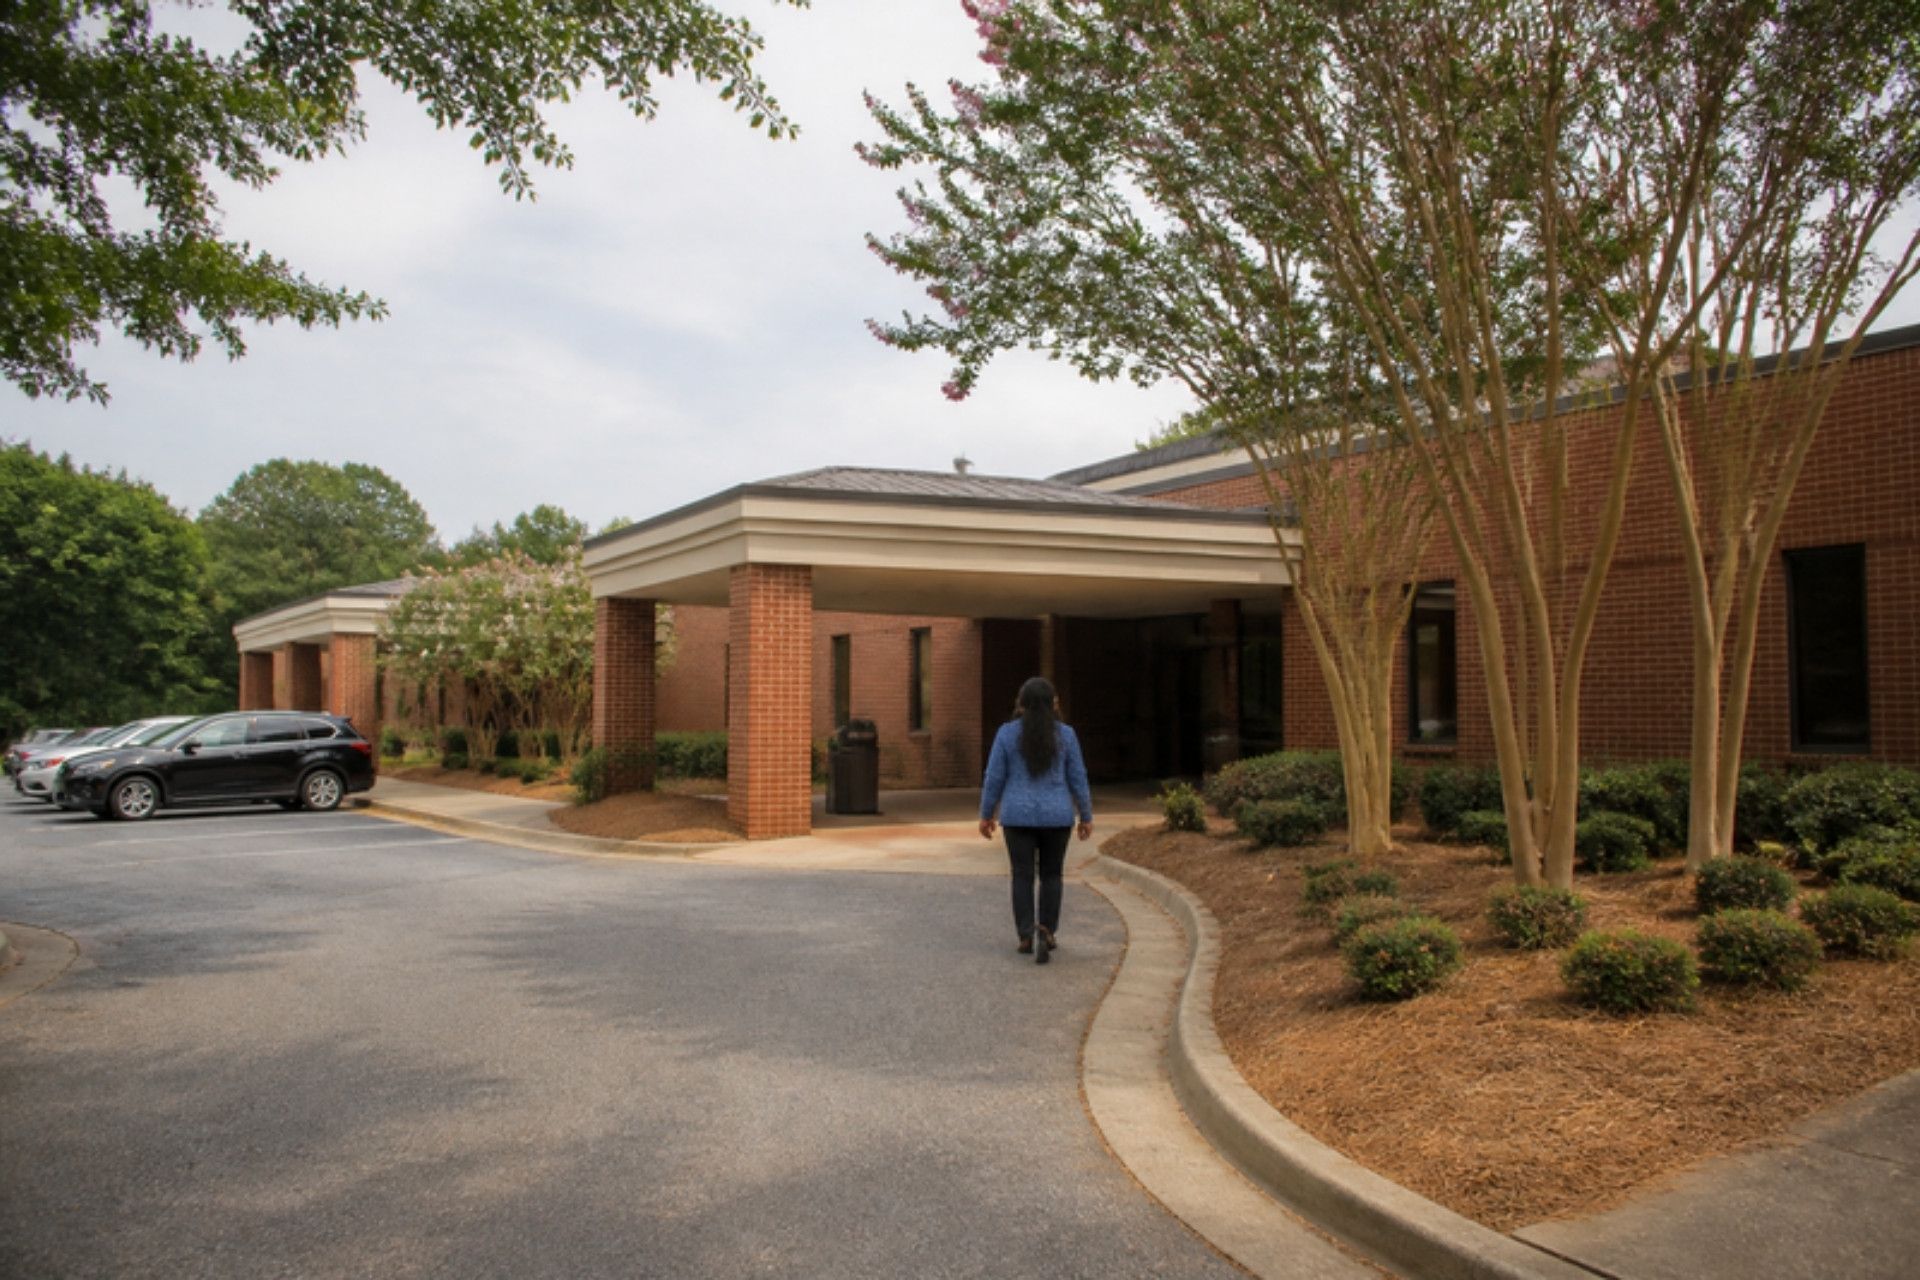
Lab property coverage protects the buildings, equipment, and contents that make research possible, including freezers, sequencers, mass spectrometers, and biological materials. Standard property forms frequently exclude or limit spoilage, mechanical breakdown, and the value of research samples, so specific endorsements are required.
The most significant loss in a Triangle-area lab is often not the equipment itself but what the equipment protects. When an ultra-low temperature freezer fails over a holiday weekend, the replaceable unit may represent a small portion of the loss, while years of cell lines, patient samples, and compound libraries are destroyed. Key provisions to review include:
- Spoilage coverage: This responds to temperature change caused by power outage or equipment failure.
- Equipment breakdown: This addresses electrical and mechanical failure, which standard property policies generally exclude.
- Valuable papers and research records: This covers the cost of recreating data.
- Business income and extra expense: This replaces lost revenue and funds temporary lab space during repairs.
Valuation methods matter considerably. Firms should document how biological materials will be valued, whether by replacement cost, cost to recreate, or another agreed method, before a loss occurs.
Directors and Officers (D&O) Insurance for Research Firms
Directors and officers insurance protects the personal assets of company leaders, and the company itself, when they are sued over management decisions. North Carolina biotech firms need this coverage during funding rounds, mergers, and regulatory scrutiny, when allegations of misrepresentation become more likely.
Venture capital and private equity investors routinely require D&O coverage as a condition of closing a funding round, and board candidates frequently decline seats without it. Typical claims involve shareholders alleging that trial results were overstated, that regulatory timelines were misrepresented, or that leadership mishandled a failed study. Government investigations and employment disputes may also trigger coverage, depending on policy wording.
Established firms should evaluate Side A coverage, which protects individual directors when the company cannot indemnify them. Startups should confirm that the policy definition of "claim" includes regulatory inquiries and that the investor-versus-insured exclusion does not unintentionally bar claims brought by their own venture backers.
Comparing Professional vs. Products Liability
Professional liability, also called errors and omissions, responds to financial loss caused by a service performed incorrectly, such as a contract lab reporting flawed assay data. Products liability responds to bodily injury or property damage caused by a physical product. A contract research organization often needs both, because its services and its deliverables carry different exposures.
Essential Life Sciences Coverage Comparison
General liability, products liability, and errors and omissions each answer a different question about who was harmed and how. The table below summarizes the distinctions that matter most for North Carolina research and biotech firms.
| Coverage | What It Covers | Typical Claim | Common Gap |
|---|---|---|---|
| General Liability | Premises injuries, third-party property damage | Visitor injured in a lab hallway | Excludes professional services |
| Products Liability | Injury or damage caused by a product | Patient harmed by a device component | Long-tail claims after coverage ends |
| Errors & Omissions | Financial loss from faulty services or advice | Sponsor sues over inaccurate study data | Often excludes bodily injury |
Market conditions also influence how these lines are priced. The North Carolina property and casualty market grew by 4.3% in 2026, signaling a transition from rapid repricing to more moderate growth. Firms that prepare detailed underwriting submissions are generally better positioned in that environment.
Common Questions About North Carolina Life Sciences Insurance
The questions below reflect concerns that research firms and biotech founders raise most often when reviewing coverage for the first time.
Does my lab property cover spoilage?
Usually not without an endorsement. Spoilage and equipment breakdown coverage are commonly added separately, and sublimits should reflect the true value of stored samples.
Do I need clinical trial insurance before recruiting participants?
Yes. Most institutional review boards and clinical sites require proof of coverage before enrollment begins.
Will general liability cover a defective product claim?
Some general liability policies include products coverage, but many life sciences firms require a dedicated products policy with higher limits and terms suited to the industry.
When should a startup buy D&O insurance?
Ideally, coverage should be in place before the first institutional funding round, because investors often require it at closing.
Does a university affiliation in Kannapolis cover my company?
University coverage generally protects the university, not a separate private company operating nearby or within the campus.
Why Partner With an Independent Agency
An independent agency represents multiple insurance carriers rather than one, which allows a life sciences firm to compare specialized products, clinical trial, and D&O markets in a single review. Going direct to a carrier limits options to that carrier's appetite and policy forms.
Life sciences risks are written by a relatively small group of specialty underwriters, and appetites vary considerably by product stage, trial phase, and revenue. Some carriers may decline early-stage device companies, while others may focus on contract research organizations. An independent agent can present one submission to several markets and explain differences in exclusions, retroactive dates, and sublimits that are difficult to identify by comparing quotes alone.
O'Connor Insurance Associates has operated as an independent agency in Charlotte, North Carolina, since 2000 and has been recognized as an IIABA Best Practices Agency since 2010. The agency follows an educational approach, asking detailed questions about research operations before recommending a customized program, and it does not act as the insurance carrier.
Your Next Steps for Secure Research
Securing a research operation begins with an inventory of products, active and planned trials, lab assets, and board structure, followed by a review of how current policies respond to each exposure. Gaps are most often found in spoilage limits, retroactive dates, and trial scheduling.
Firms in Research Triangle Park, Kannapolis, Concord, Harrisburg, and the greater Charlotte area should gather current policies, investor agreements, clinical site contracts, and an equipment schedule before a coverage review. Those documents allow a thorough comparison of available markets and reveal where existing protection falls short.
O'Connor Insurance Associates is a licensed North Carolina insurance agency (license #7014004) located in Charlotte, North Carolina, at 1973 JN Pease Place, Suite 203, Charlotte, North Carolina 28262. To schedule a life sciences coverage review, contact the agency at 704-510-8884. Research creates value that takes years to build, and the right insurance program helps ensure a single claim or freezer failure does not undo that work.
Coverage descriptions are general. Policy terms, exclusions, limits and underwriting determine coverage.
Last updated:
On this page
O’Connor Insurance Associates is fully licensed to provide personal and commercial insurance solutions for individuals, families and businesses across North Carolina.
We proudly serve families and business owners from our office in Charlotte, North Carolina. As an independent, family-owned agency since 2000, our team works with more than one insurance company to make sure homeowners, drivers, contractors, landscapers, small businesses and other personal and commercial clients receive coverage that fits their real risks.

About the Author
President & Founder
I’m Terry O’Connor, President and Founder of O’Connor Insurance Associates. I grew up in Pennsylvania, earned my bachelor’s degree at Edinboro University and my master’s at Gannon University, and in 1998 I traded snow for sunshine and moved to Charlotte. In January 2000, I started this agency on my own because I wanted to help people protect what matters most to them. More than two decades later, we’ve grown into an independent agency serving families and businesses across North Carolina, and we’ve been recognized as an IIABA Best Practices Agency every year since 2010, a distinction held by fewer than 1% of agencies nationwide.
I’ve seen firsthand how the right protection can change a family’s or a business owner’s life, and that’s why I lead with empathy, education and honest advice. As an independent agent, I work for you, not for one insurance company. I take the time to explain your options in plain language, and when you call our office, you reach a real person who knows your account.
Outside the office, you’ll usually find me outdoors hunting or fishing, or on the mat coaching wrestling as an assistant varsity coach at Mallard Creek High School. I’m also a proud supporter of the arts, usually in the front row cheering on my daughter in local theater productions. I’d be glad to review your coverage with you. Call me at 704-510-8884 or email terry@oianc.com.
Relationships are the real measure
What our North Carolina clients say.
5.0 / 5
185 reviews on Google
Personal insurance
For the life you’re making.
Your home, your car, your time away. Let’s look at the whole picture.
Business insurance
For the business you’re building.
From established local companies to growing teams, we help make the coverage conversation clearer.
Your work deserves a closer look
Different businesses.
Different conversations.
We take time to understand what happens in your business every day.

Landscaping

Manufacturers

Technology Companies

HVAC Insurance

Electricians Insurance

Food Manufacturers
A little clarity goes a long way
Good questions.
Straight answers.
Have something else on your mind?
What does an independent insurance agency do?
An independent agency helps you compare options from more than one insurance company. We start with your needs, explain the differences and help you make an informed decision.
What can O’Connor help me insure?
Our team works with personal and business insurance, life and disability coverage, and Medicare options. Tell us what you need, and we’ll connect you with the right person.
Where does your agency serve clients?
We are based in Charlotte and serve clients across North Carolina. If your business operates in more than one state, call us to discuss your locations and coverage needs.
How do I get an insurance quote?
Start with the contact form or call 704-510-8884. We’ll ask about your situation and any current coverage, then review available options. Submitting a request does not bind coverage.
Can you help with an existing policy or claim?
Yes. Our Client Center page connects you with policy service, billing and claims options. You can also call during office hours for help finding the right next step.
What should I know before switching insurance?
Compare coverage, limits, exclusions and effective dates, not just the price. Speak with your agent before canceling an existing policy so you can coordinate the transition.
From our desk to yours
A little knowledge goes a long way.



Get a Quote
Let’s protect what you’re building.
Tell us a little about yourself. We’ll help you take the next step with a clearer picture of your options.
1973 J.N. Pease Place, Suite 203
Charlotte, NC 28262
Monday–Thursday · 9 AM–5 PM
Friday · 9 AM–3 PM
