



Ballantyne, North Carolina Home Insurance

185+ five-star Google reviews for O'Connor Insurance Associates

Homeowners in Ballantyne often own executive homes inside gated golf communities, where a single policy must address high dwelling values, HOA obligations, and significant personal liability exposure. Ballantyne, North Carolina home insurance works well when replacement cost is calculated accurately, coverage reflects the luxury features of newer construction, and home, auto, and umbrella policies are coordinated. Each of these decisions affects how fully a South Charlotte family recovers after a serious claim.

Insuring Executive Homes in Ballantyne North Carolina Golf Communities

Executive homes in neighborhoods such as Ballantyne Country Club usually require higher dwelling limits, broader personal property protection, and stronger liability coverage than a standard policy provides. Wind and hail deductibles are mainly a coastal concern and are rarely used in this part of North Carolina, so other coverage details deserve more attention.

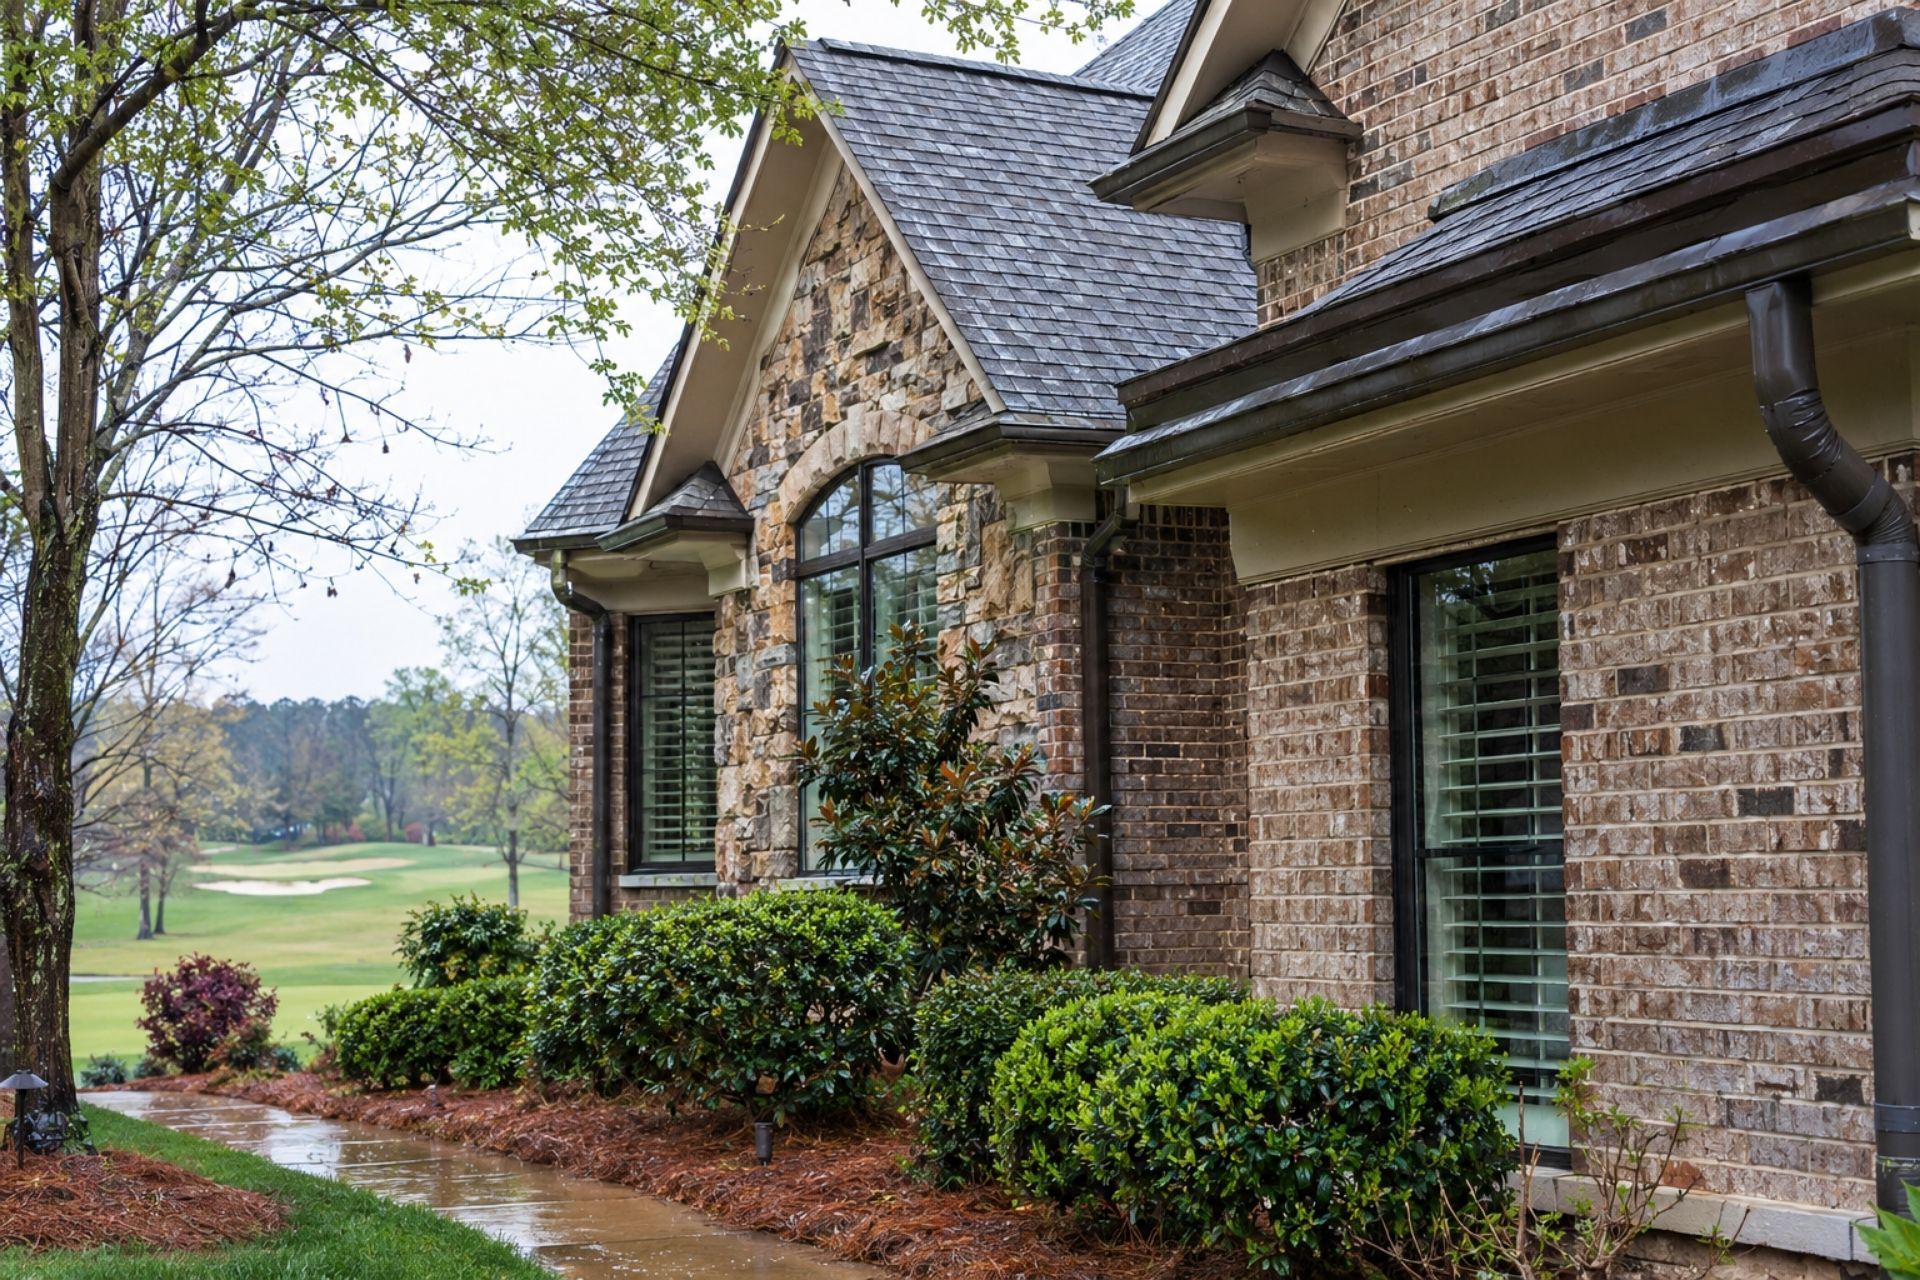
Properties along South Charlotte fairways often include custom millwork, wine rooms, outdoor kitchens, and pool areas. Each of these features increases rebuilding costs and adds liability exposure. Homes near a course can also take stray golf balls, which can crack windows or damage siding. Claims of this kind are common enough that homeowners should confirm how their policy and their HOA divide responsibility for exterior repairs.

Couple at a kitchen table in a Charlotte home reviewing their homeowners insurance declarations page

Meeting HOA Requirements and Replacement Cost for New Construction

Mecklenburg County HOA covenants determine which parts of the property the association insures and which parts the homeowner must insure. For newer luxury builds, an accurate replacement cost estimate determines whether a total loss is fully rebuilt or leaves the owner with a large shortfall.

Single-family HOAs in Ballantyne usually insure only the common areas, so the full structure remains the owner's responsibility. Townhome and condominium arrangements work differently. Under North Carolina law, condo associations must carry property insurance for at least 80% of replacement cost. The individual owner still needs coverage for interior finishes and improvements that the master policy does not include.

A common mistake on new construction is using the purchase price as the dwelling limit. Purchase price includes land value and does not reflect what it costs to rebuild. Custom finishes, rising material costs, and current building code upgrades can all push actual rebuilding costs higher.

Comparing Coverage Options for South Charlotte Homeowners

The table below shows how basic and extended coverage forms differ for higher-value homes in South Charlotte. The extended HE-7 form typically offers broader personal property protection and higher limits for valuables.

Feature Basic (HO-3) Extended (HE-7)
Personal property Named perils only All-risk coverage
Jewelry and fur sub-limit $1,500 $5,500
Best fit Standard homes Executive homes
Scheduled valuables Often required for most items Fewer gaps before scheduling

Even with an extended form, high-value jewelry, art, and collections usually need to be scheduled separately to receive full protection.

Frequently Asked Questions About Ballantyne Home Insurance

The following answers address common questions from South Charlotte homeowners about bundling, golf carts, and North Carolina requirements.

  • Can I bundle my home and auto insurance?

    Yes. Many carriers offer multi-policy pricing, and placing both policies with one company also simplifies claims and renewals.

  • Does my homeowners policy cover my golf cart?

    Coverage is usually limited to use on your own property. If you drive the cart on community streets, you may need a separate golf cart policy or an endorsement.

  • Is home insurance required in North Carolina?

    No state law requires it. However, mortgage lenders almost always require it, and many HOAs require proof of coverage.

  • How much does an umbrella policy cost?

    A $1 million personal umbrella policy in North Carolina currently starts at roughly $210 to $380 per year, depending on your household and the vehicles you own.

  • Why would an umbrella policy matter in Ballantyne?

    Pools, teen drivers, and frequent entertaining all increase liability exposure, and a serious lawsuit can exceed the liability limits on your home and auto policies.

Couple at a kitchen table in a Charlotte home reviewing their homeowners insurance declarations page

Making the Right Choice for Your Ballantyne Property

Choosing the right coverage for a Ballantyne executive home starts with comparing several carriers on replacement cost, coverage form, and how well the home, auto, and umbrella policies work together. An independent agency can review these options side by side.

O'Connor Insurance Associates has served Charlotte since 2000 and has been recognized as an IIABA Best Practices Agency since 2010. The agency can compare options from carriers such as Erie, Travelers, Cincinnati, Progressive, National General, Utica, and Foremost. Features and eligibility vary by carrier and by property, so each recommendation depends on the details of your home.

To request a review of your current South Charlotte coverage, call 704-510-8884 or visit 1973 JN Pease Place, Suite 203, Charlotte, NC 28262. O'Connor Insurance Associates is a licensed North Carolina insurance agency (license #7014004).

Terry O'Connor, CIC, President and Founder of O'Connor Insurance Associates

Written By

President


Last updated:

O’Connor Insurance Associates is fully licensed to provide personal and commercial insurance solutions for individuals, families and businesses across North Carolina.

We proudly serve families and business owners from our office in Charlotte, North Carolina. As an independent, family-owned agency since 2000, our team works with more than one insurance company to make sure homeowners, drivers, contractors, landscapers, small businesses and other personal and commercial clients receive coverage that fits their real risks.

Terry O'Connor, CIC, President and Founder of O'Connor Insurance Associates

About the Author

President & Founder


I’m Terry O’Connor, President and Founder of O’Connor Insurance Associates. I grew up in Pennsylvania, earned my bachelor’s degree at Edinboro University and my master’s at Gannon University, and in 1998 I traded snow for sunshine and moved to Charlotte. In January 2000, I started this agency on my own because I wanted to help people protect what matters most to them. More than two decades later, we’ve grown into an independent agency serving families and businesses across North Carolina, and we’ve been recognized as an IIABA Best Practices Agency every year since 2010, a distinction held by fewer than 1% of agencies nationwide.

I’ve seen firsthand how the right protection can change a family’s or a business owner’s life, and that’s why I lead with empathy, education and honest advice. As an independent agent, I work for you, not for one insurance company. I take the time to explain your options in plain language, and when you call our office, you reach a real person who knows your account.

Outside the office, you’ll usually find me outdoors hunting or fishing, or on the mat coaching wrestling as an assistant varsity coach at Mallard Creek High School. I’m also a proud supporter of the arts, usually in the front row cheering on my daughter in local theater productions. I’d be glad to review your coverage with you. Call me at 704-510-8884 or email terry@oianc.com.

Relationships are the real measure

What our North Carolina clients say.

5.0 / 5

185 reviews on Google

Personal insurance

For the life you’re making.

Your home, your car, your time away. Let’s look at the whole picture.

Home

A place of your own deserves a thoughtful look at coverage.

Auto

Understand your options before you get behind the wheel.

Umbrella

Explore an extra layer of personal liability protection.

Flood

Talk through water risks that need a separate conversation.

Condo

Make sense of your unit’s coverage and your association’s policy.

Boat

Enjoy time on the water with coverage in mind.

Business insurance

For the business you’re building.

From established local companies to growing teams, we help make the coverage conversation clearer.

General Liability

Start with the risks your day-to-day operations can create.

Business Owners

Review property and liability needs together.

Workers Compensation

Help protect the people who keep your business moving.

Commercial Auto

Coverage conversations for your vehicles and drivers.

Commercial Property

Consider the building, equipment and inventory you rely on.

Cyber Insurance

Explore protection for the digital side of your business.

Your work deserves a closer look

Different businesses.
Different conversations.

We take time to understand what happens in your business every day.

A little clarity goes a long way

Good questions.
Straight answers.

Have something else on your mind?

  • What does an independent insurance agency do?

    An independent agency helps you compare options from more than one insurance company. We start with your needs, explain the differences and help you make an informed decision.

  • What can O’Connor help me insure?

    Our team works with personal and business insurance, life and disability coverage, and Medicare options. Tell us what you need, and we’ll connect you with the right person.

  • Where does your agency serve clients?

    We are based in Charlotte and serve clients across North Carolina. If your business operates in more than one state, call us to discuss your locations and coverage needs.

  • How do I get an insurance quote?

    Start with the contact form or call 704-510-8884. We’ll ask about your situation and any current coverage, then review available options. Submitting a request does not bind coverage.

  • Can you help with an existing policy or claim?

    Yes. Our Client Center page connects you with policy service, billing and claims options. You can also call during office hours for help finding the right next step.

  • What should I know before switching insurance?

    Compare coverage, limits, exclusions and effective dates, not just the price. Speak with your agent before canceling an existing policy so you can coordinate the transition.

From our desk to yours

A little knowledge goes a long way.

House framing under construction, illustrating North Carolina general contractor license requirements
by Michelle O'Connor • 2 November 2026
What North Carolina requires for a general contractor license: the Licensing Board threshold, financial requirements, exams, and insurance.

Small Charlotte office with client files and a server cabinet, subject to the North Carolina data breach law
by Michelle O'Connor • 2 November 2026
What North Carolina's Identity Theft Protection Act requires of businesses after a data breach, including notice deadlines and cyber insurance.

Warehouse loading dock with forklift in North Carolina, illustrating workers comp experience mods in North Carolina
by Michelle O'Connor • 2 November 2026
How the NC Rate Bureau calculates your North Carolina workers comp experience mod, why one claim can raise premiums for three years, and how to bring it down.

Get a Quote

Let’s protect what you’re building.

Tell us a little about yourself. We’ll help you take the next step with a clearer picture of your options.


1973 J.N. Pease Place, Suite 203
Charlotte, NC 28262

Monday–Thursday · 9 AM–5 PM
Friday · 9 AM–3 PM

Speak with a Charlotte agent today.





